Which States Fully Exempt Retirement Income?
Planning for retirement often comes with a whole host of questions, and frankly, some anxieties, especially when it comes to money. One of the biggest concerns I hear from folks nearing or in retirement is how state income taxes might eat into their hard-earned savings and fixed income. It’s absolutely frustrating to think you’ve planned everything out, only to realize a significant chunk of your pension or 401(k) withdrawals could be subject to state taxes. This guide is here to shed light on which states truly offer a full exemption on retirement income, helping you understand where your retirement nest egg can stretch the furthest without state-level interference.
Navigating the Labyrinth of Retirement Income Taxation
When we talk about retirement income, it’s not just one big bucket. It encompasses a variety of sources, and states can treat each of them differently. This is where the confusion often begins. One state might not tax your Social Security, but it'll take a slice of your pension. Another might be perfectly fine with your IRA withdrawals but hit you on capital gains. It's a patchwork quilt of rules, and understanding these nuances is crucial for savvy retirement planning.
Deconstructing "Retirement Income" for Tax Purposes
What exactly do we mean by "retirement income"? From a state tax perspective, this can include several distinct categories. The most common ones you'll encounter are:
- Social Security Benefits: For many, this is a foundational piece of their retirement income puzzle. While the federal government taxes a portion of Social Security for some higher earners, states have their own rules.
- Pension Income: This refers to income from defined benefit plans, often provided by former employers (private or public sector). The tax treatment can vary widely depending on whether it's a private, government, or military pension.
- 401(k) and IRA Distributions: These are the workhorses of many retirement savings plans. Withdrawals from traditional 401(k)s and IRAs are generally taxed as ordinary income at the federal level, but state rules can differ dramatically. Roth IRA withdrawals, because they are funded with after-tax dollars, are typically tax-free at both federal and state levels, provided certain conditions are met (like being over 59.5 and the account being open for at least five years).
- Other Investment Income: This can include capital gains from selling investments, dividends, and interest income. While not strictly "retirement income," it's often a significant component of a retiree's overall financial picture.
The challenge is that a state might be "friendly" to one type of income but not another. For instance, many states don't tax Social Security benefits, but only a handful truly offer a blanket exemption for all forms of retirement income. This distinction is key when you're looking for states that truly "fully exempt" retirement income.
How States Apply Taxes to Your Golden Years
States generally fall into a few broad categories when it comes to taxing retirement income:
- States with No Income Tax at All: These are the ultimate "fully exempt" states for retirement income, simply because they don't have an income tax system to begin with. If there's no state income tax, there's no tax on any income, including retirement income. This is often the first place people look when trying to minimize their tax burden in retirement.
- States with Broad Exemptions or Exclusions: These states might have an income tax, but they offer significant deductions or exemptions specifically for retirement income. This could mean they don't tax Social Security, certain types of pensions, or a portion of 401(k)/IRA withdrawals, especially after a certain age or up to a specific income threshold. While not truly "fully exempting" all income, they can be very tax-friendly.
- States with Partial Exemptions or Deductions: These states tax most retirement income but might offer limited deductions or exemptions for specific circumstances. For example, they might exempt military pensions or offer a small deduction for all retirement income up to a certain dollar amount.
- States that Tax Most Retirement Income: These states treat retirement income similarly to regular earned income, though they might still exempt Social Security benefits. This means your pensions, 401(k), and IRA withdrawals will likely be subject to their standard income tax rates.
Understanding these categories helps set the stage for identifying those rare gems that genuinely leave your entire retirement income untouched by state income taxes.
The True Champions: States That Fully Exempt All Retirement Income
When you hear "fully exempt retirement income," what you're really looking for are states that either don't have a state income tax at all, or those that have explicit provisions to exempt all common forms of retirement distributions from any income taxation. Let's dive into the states that fit this description.
The No-Income-Tax States: The Ultimate Exemption
These are the most straightforward answers to the question of which states fully exempt retirement income. If a state doesn't have an income tax, it naturally doesn't tax any form of income, including your retirement distributions. This means your Social Security benefits, private and public pensions, and withdrawals from 401(k)s and IRAs are all untouched by state income tax.
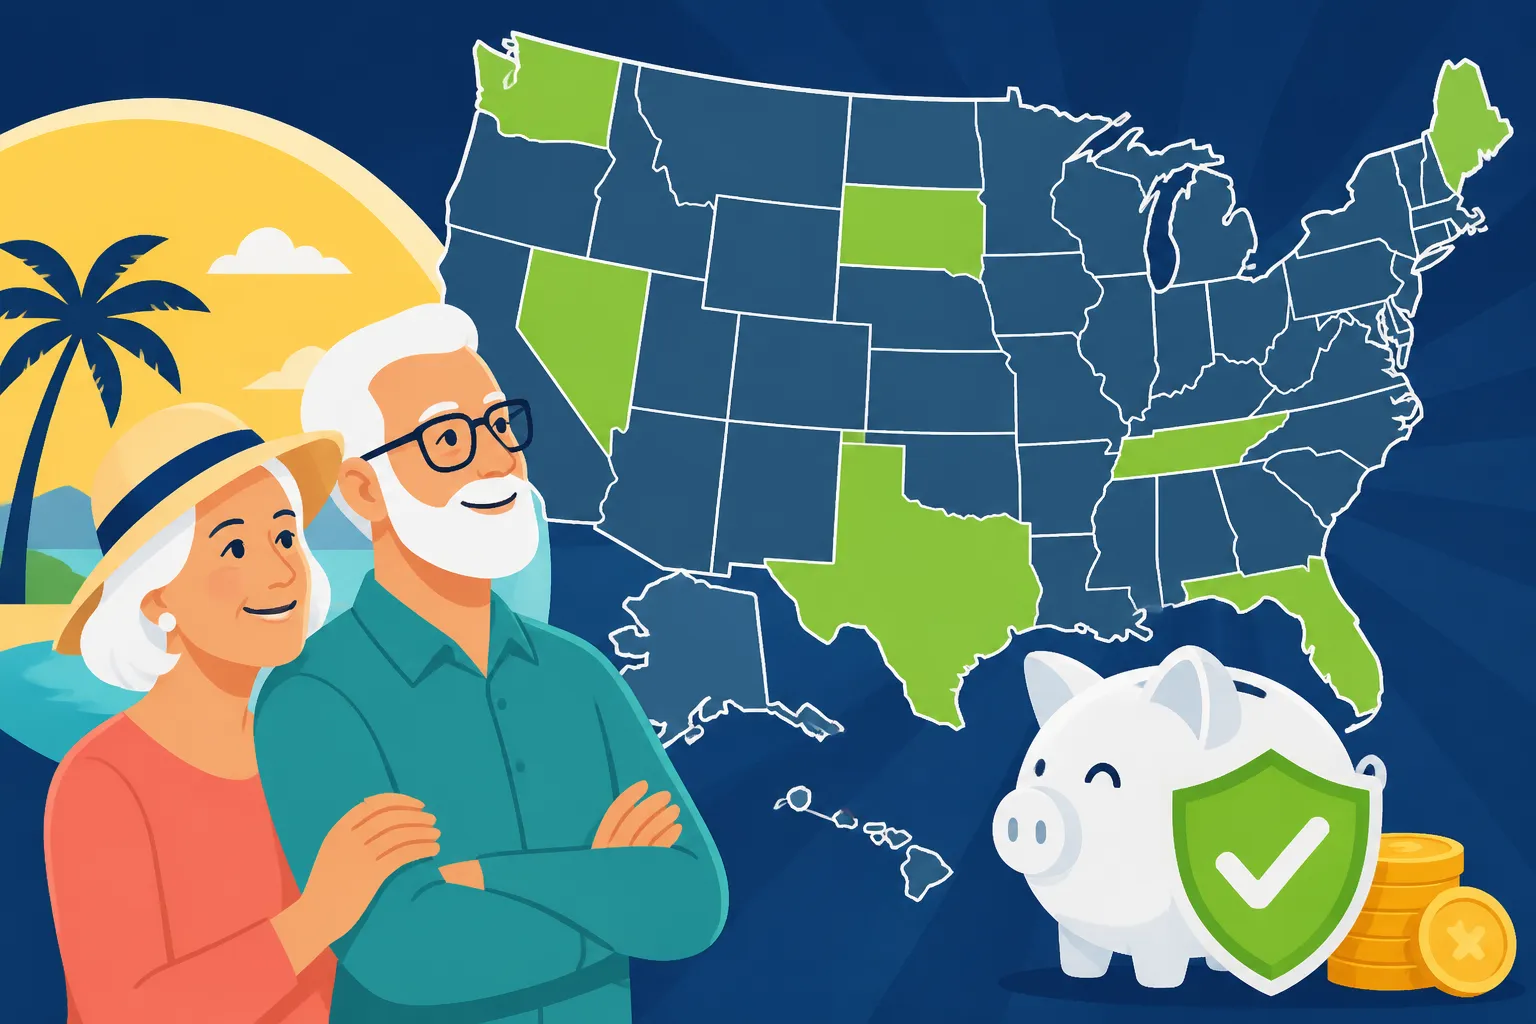
As of 2026, there are nine states that don't collect a broad-based state income tax on wages:
- Alaska
- Florida
- Nevada
- South Dakota
- Tennessee
- Texas
- Washington
- Wyoming
- New Hampshire (with a crucial caveat)
Let’s break down these states a little more:
- Alaska, Florida, Nevada, South Dakota, Texas, Washington, Wyoming: These seven states are the undisputed champions. They have no individual state income tax whatsoever, meaning your retirement income, from Social Security to 401(k) distributions, is completely exempt from state income tax. This makes them highly attractive destinations for retirees looking to maximize their income. When considering a move to Florida, for example, many retirees are drawn by the complete absence of state income tax, making it a powerful financial incentive. Similarly, the growing popularity of Texas for retirees often comes down to this significant tax advantage.
- Tennessee: Historically, Tennessee had what was known as the "Hall Tax," which taxed income from interest and dividends. However, this tax has been fully phased out and repealed as of January 1, 2021. So, for the 2026 tax year and beyond, Tennessee joins the ranks of states with no broad-based income tax, meaning it also fully exempts all retirement income. This makes Tennessee an even more attractive option for retirees, as explored in articles like Does Tennessee Have State Income Tax?.
- New Hampshire: This state is a unique case. For a long time, New Hampshire only taxed interest and dividend income, not earned income or traditional retirement distributions like pensions or 401(k) withdrawals. However, even this interest and dividends tax is currently being phased out and is set to be fully repealed by 2027. So, while technically in a transition period for some types of investment income, New Hampshire effectively does not tax the core retirement income streams most people think of (pensions, 401k/IRA withdrawals, Social Security). You can read more about the New Hampshire Interest & Dividends Tax Repeal for specific details on this transition.
So, when people talk about "States With No Income Tax (2026 Full List)," these are the places where your retirement income is truly free from state income tax. It's a significant advantage that can translate into thousands of dollars saved annually, depending on your income level.
Pennsylvania: A Standout with Unique Exemptions
Beyond the states with no income tax at all, Pennsylvania is another major contender that effectively provides a full exemption for most common types of retirement income. While Pennsylvania does have a flat income tax (currently 3.07% as of 2026), it has very broad exemptions for retirement income.
Here’s the breakdown for Pennsylvania:
- Pensions and Retirement Account Withdrawals: Generally, income from qualified retirement plans, such as 401(k)s, IRAs, Roth IRAs, and traditional pensions, is exempt from Pennsylvania state income tax once you reach a certain age (usually 59.5, or if certain other conditions are met, such as separation from service with no intent to return to that employer). This is a huge benefit, meaning the vast majority of your pension checks and withdrawals from your retirement savings are not taxed.
- Social Security Benefits: Like most states, Pennsylvania does not tax Social Security benefits.
- Military Retirement: Military retirement pay is also exempt from Pennsylvania state income tax.
The key here is "qualified." For most retirees, their pension and 401(k)/IRA withdrawals will be considered qualified and thus exempt. However, it's always wise to confirm with a financial advisor or the Pennsylvania Department of Revenue if you have a particularly unusual or complex retirement income setup. But for the vast majority, Pennsylvania functions as a state that largely exempts retirement income. This makes it quite attractive, despite having a statewide income tax, which is a nuance that often surprises people.
Summary Table of States Fully Exempting Retirement Income
To make things a bit clearer, here's a quick reference for the states that offer full exemption from state income tax on retirement income:
| State | Has State Income Tax? | Taxes Social Security? | Taxes Pensions/401k/IRA Withdrawals? | Full Retirement Income Exemption? | Notes |
|---|---|---|---|---|---|
| Alaska | No | No | No | Yes | No state income tax at all. |
| Florida | No | No | No | Yes | No state income tax at all. |
| Nevada | No | No | No | Yes | No state income tax at all. |
| South Dakota | No | No | No | Yes | No state income tax at all. |
| Tennessee | No | No | No | Yes | Hall Tax on interest/dividends repealed (effective 2021). |
| Texas | No | No | No | Yes | No state income tax at all. |
| Washington | No | No | No | Yes | No state income tax (but capital gains tax exists for some high earners). |
| Wyoming | No | No | No | Yes | No state income tax at all. |
| New Hampshire | No (on earned income) | No | No | Yes (mostly) | Phasing out interest/dividends tax, no tax on earned income/pensions/401k/IRAs. |
| Pennsylvania | Yes (flat rate) | No | No (for qualified plans) | Yes (for most common types) | Broad exemptions for qualified retirement income. |
Note: The Washington Capital Gains Tax Explained (7% / 9.9%) is a specific tax on high-value long-term capital gains for very high earners and does not affect typical retirement income like pensions or 401(k) distributions, making it still a no-income-tax state for most.
Other Highly Tax-Friendly States for Retirees (But Not Fully Exempt)
While the list above represents the states that truly offer a full exemption on all, or nearly all, traditional retirement income, it’s important to acknowledge that many other states are still very tax-friendly for retirees. They just don't meet the strict "fully exempt" criteria because they tax at least one form of retirement income. However, their generous exclusions and deductions can still make them excellent choices for your golden years.
These states often take a hybrid approach, exempting certain types of retirement income or offering significant deductions that can greatly reduce your overall tax burden. This is where researching beyond the "no income tax" label becomes invaluable. Financial platforms like SmartAsset often publish guides and calculators that can help you compare the full tax picture in various locations, taking into account property and sales taxes, not just income tax.
States with Generous Exclusions and Deductions
Many states that impose an income tax still go to great lengths to make life easier for retirees. Here are a few examples of states that are notably retirement-income-friendly due to their broad exemptions or substantial deductions:
- Illinois: Illinois is a fantastic example of a state with a flat income tax (currently 4.95% as of 2026) that is incredibly kind to retirees. The state does not tax Social Security benefits, private pensions, public pensions, or income from 401(k)s, IRAs, and other qualified retirement plans. So, while it has an income tax, it essentially functions as a "fully exempt" state for most traditional retirement income sources. The only reason it's not in the previous list is that it technically has an income tax on other types of income.
- Mississippi: This state is another pleasant surprise for retirees. Mississippi does not tax Social Security benefits, public or private pension income, or withdrawals from 401(k)s and IRAs. Like Illinois, it has a state income tax on other income, but its comprehensive exemption for retirement income makes it incredibly attractive.
- Massachusetts: While Massachusetts has a flat income tax rate, it generally exempts Social Security benefits. For other retirement income like pensions and 401(k)/IRA distributions, it provides various exemptions, especially for lower and middle-income retirees. The rules can be a bit more complex than Illinois or Mississippi, often tied to age and income levels, but it can still be very beneficial.
- New Jersey: New Jersey offers a significant income exclusion for retirement income for those who meet certain age and income qualifications. For 2026, eligible seniors can exclude a substantial portion of their pension, annuity, and IRA income. For example, individuals filing jointly can exclude a significant amount of retirement income, making New Jersey much more retirement-friendly than its high overall tax reputation might suggest. This is a great example of a state that makes an effort to be appealing, as detailed in New Jersey Retirement Income Exclusion.
- Georgia: Georgia offers a generous exclusion for retirement income for individuals aged 65 or older. For 2026, seniors can exclude up to $65,000 per person (or $130,000 for a married couple) of most types of retirement income, including pensions, annuities, interest, dividends, and net rentals. This substantial exclusion means that many retirees will pay little to no state income tax on their retirement earnings. You can learn more about the Georgia $65,000 Retirement Exclusion (2026) and how it can benefit you.
- Colorado: Colorado also exempts Social Security benefits for most taxpayers. Additionally, it offers a significant subtraction for other retirement income (pensions, annuities, IRA distributions) depending on age. For those aged 65 and older, the exclusion can be quite substantial, significantly reducing taxable retirement income. This is often referred to as the Colorado Retirement Subtraction ($20k/$24k).
These states demonstrate that even with a state income tax, thoughtful legislation can create a very favorable environment for retirees. It's not just about a "no income tax" label; sometimes, the exemptions and deductions are so robust that the effect is nearly the same for your retirement income.
The Bigger Picture: Beyond Income Tax
When evaluating the tax-friendliness of a state for retirement, it's a mistake to look only at income tax. A state might have no income tax, but compensate for it with higher property taxes or sales taxes. This is why a holistic view is essential.
For example, while Florida and Texas have no state income tax, their property taxes can be higher than in some states with income tax, especially in desirable coastal or metropolitan areas. Similarly, sales taxes can add up, particularly if you're a consumer who frequently makes large purchases.
Key factors to consider beyond just income tax include:
- Property Taxes: These can be a substantial burden, especially if you own a home. Some states offer homestead exemptions or property tax breaks for seniors, which can help offset these costs.
- Sales Taxes: How much do you spend on goods and services? High sales taxes can quickly erode your savings, even if your income isn't taxed.
- Estate or Inheritance Taxes: A few states still impose these taxes, which can impact what you leave behind for your heirs.
- Cost of Living: Beyond taxes, the overall cost of living – housing, groceries, healthcare, transportation – varies wildly from state to state. A state with low taxes but an extremely high cost of living might not be as financially beneficial as a state with moderate taxes and a lower cost of living. This interplay between Cost of Living vs Taxes by State is crucial for truly understanding your financial outlook.
Organizations like SmartAsset frequently publish comprehensive studies on the most tax-friendly states for retirees, taking into account all these factors. Their detailed analysis often highlights that the "best" state for one retiree might not be the best for another, depending on their income, spending habits, and asset profile. It's about finding the balance that works for your specific situation.
Ultimately, the goal is to How to Minimize State Taxes in Retirement by strategically choosing a location that aligns with your financial goals and lifestyle preferences. Whether it’s one of the pure no-income-tax states or a state with very generous exemptions, doing your homework will save you a lot of financial heartache down the road.
Disclaimer
Please remember that tax laws are complex and can change. The information provided in this guide is for informational purposes only and does not constitute professional tax advice. Always consult with a qualified tax professional or financial advisor for personalized advice regarding your specific tax situation and retirement planning. State tax regulations can be intricate, and residency rules, in particular, can have a significant impact on your tax obligations.