529 Plan Tax Deductions by State
It's no secret that saving for college can feel like an uphill battle, especially with tuition costs constantly on the rise. You want to give your kids (or grandkids!) the best start, but figuring out how to do it efficiently, without losing a chunk to taxes, adds another layer of stress. This guide is here to break down one of the most powerful tools in your college savings arsenal: 529 plan state tax deductions, and how they can seriously lighten your tax burden while you save for that future degree.
What Exactly Is a 529 Plan Anyway?
Before we dive into the nitty-gritty of state tax benefits, let's make sure we're all on the same page about what a 529 plan is. Think of it as a special investment account designed specifically for education expenses, with some really sweet tax advantages. It’s authorized under Section 529 of the Internal Revenue Code, hence the name, and it’s offered by individual states. These aren't just for four-year universities anymore; they can cover a wide range of educational pursuits.
Types of 529 Plans: Savings vs. Prepaid
When you hear "529 plan," most people immediately think of a college savings plan, and that's generally what we'll be focusing on for tax deductions. But it's worth knowing there are actually two main flavors:
1. College Savings Plans: These are the most common type, and they operate a lot like a Roth IRA or 401(k), but for education. You contribute money, and that money is then invested in a portfolio of mutual funds or other investment vehicles chosen by the plan administrator. The value of your account grows (or shrinks, depending on market performance) over time, and the key here is that any earnings grow tax-free at the federal level. When it's time for your student to head off to college, withdrawals are also tax-free for qualified education expenses. This flexibility and growth potential make them incredibly popular. You're not tied to a specific school or tuition rate; instead, you're building an investment portfolio. This means they carry market risk, just like any other investment. You pick a plan, contribute, and watch it grow, hopefully, over years or even decades. The vast majority of states offer a college savings plan, and many states even let you pick plans from other states, though your state tax deduction might depend on using your home state's plan.
2. Prepaid Tuition Plans: These are a bit different and less common. Instead of investing in the market, you're essentially buying future tuition credits at today's prices. They're usually sponsored by states and often only cover in-state public colleges. The idea is to lock in tuition rates, protecting you from future increases. This can sound really appealing, especially with tuition going up year after year! However, they tend to be less flexible. If your child decides to go to an out-of-state school, a private university, or opts for a vocational path, the benefits might be diminished or converted to a cash value that may not keep pace with tuition elsewhere. They remove investment risk, but they also limit your options. Some states, like Florida and Maryland, still offer these, but they're definitely not as widely available or as flexible as the savings plans.
The Federal Tax Benefits: A Quick Overview
One of the biggest draws of a 529 plan, regardless of which state's plan you choose, is the incredible federal tax treatment. This is the baseline benefit that everyone enjoys:
Tax-Free Growth and Withdrawals: This is the superstar feature. Your contributions aren't deductible at the federal level, unlike traditional IRA contributions, but here’s the magic: any money your investments earn within the 529 plan grows completely free from federal income tax. And when it comes time to pay for college, qualified withdrawals – for things like tuition, fees, books, supplies, equipment, and even room and board if the student is enrolled at least half-time – are also 100% federal income tax-free. Imagine the power of compounding interest when you don't have Uncle Sam taking a slice every year!
Broad Definition of Qualified Expenses: What counts as a "qualified education expense" has actually expanded quite a bit over the years. It’s not just for undergrad tuition anymore. It includes K-12 tuition expenses (up to $10,000 per year per beneficiary), expenses for apprenticeship programs, and even up to $10,000 (lifetime limit per beneficiary) for student loan repayments. This added flexibility makes 529s even more versatile for various educational paths.
Gift Tax Benefits: 529 plans are also a fantastic estate planning tool. Contributions to a 529 plan are considered completed gifts and are removed from your taxable estate. You can contribute a significant amount each year without incurring federal gift tax, currently up to $18,000 per individual (or $36,000 for married couples filing jointly) in 2024. And get this: you can even front-load five years' worth of contributions at once, meaning you could contribute $90,000 (or $180,000 for married couples) in a single year without using up your lifetime gift tax exemption, provided you don't make any other gifts to that beneficiary during the five-year period. This allows you to supercharge your savings early on.
So, while federal tax benefits are great, many states go a step further to incentivize saving with 529 plans, and that's where the state income tax deductions come into play.
Understanding State Tax Deductions for 529 Contributions
This is where things get really interesting, and frankly, a bit complex. While the federal government doesn't offer a tax deduction for your 529 contributions, many states do. This means you could potentially reduce your taxable income at the state level just by putting money aside for education. It’s like getting a thank-you note from your state tax agency in the form of a lower tax bill! For those looking to optimize their tax planning, understanding these state-specific benefits is crucial. If you're wondering, "Can I Deduct 529 Contributions on State Taxes?", the answer is often "yes," but with important caveats.
In-State vs. Out-of-State Plans and Deductions
Here’s a common point of confusion that trips up many families: Do you get a state tax deduction if you contribute to any 529 plan, or only to the one sponsored by your home state? The answer depends entirely on where you live.
-
"Home State Only" Deductions: Many states, in an effort to promote their own 529 programs, only offer a tax deduction or credit if you contribute to their specific plan. For example, if you're a New York resident, you'll generally only receive a New York state income tax deduction for contributions made to the New York's 529 College Savings Program. If you choose to invest in, say, Virginia's 529 plan (which might have different investment options or lower fees), you wouldn't qualify for the New York state tax break, even though you'd still get all the federal tax benefits. This forces you to weigh your options: is the state tax deduction worth potentially sacrificing a plan with better investment choices or lower fees? For many, especially those in higher state income tax brackets, the deduction can be significant enough to make the in-state plan the most attractive option.
-
"Any State Plan" Deductions: On the flip side, some states are more generous. They'll give you a tax deduction for your 529 contributions regardless of which state's plan you choose to invest in. Arizona is a great example of this; its residents can deduct contributions to any state's 529 plan. This offers incredible flexibility, allowing you to shop around for the 529 plan that best fits your investment philosophy, risk tolerance, and fee preferences, without giving up your state tax incentive. This is often an overlooked benefit that can make a huge difference in your long-term savings strategy.
Understanding this distinction is really important because it could influence your choice of plan. Don't assume your state's plan is automatically the best fit without checking if you could get the same deduction (or a better plan) elsewhere.
How the Deduction Works: Practical Examples
Let's talk brass tacks about how these deductions actually put money back in your pocket. A state tax deduction reduces your adjusted gross income (AGI) at the state level. Lower AGI means less income is subject to state tax, which means you pay less in state income tax. It's that simple, yet incredibly powerful. If you're asking, "What Is My State Tax Rate If I Make $100,000?", knowing how a 529 deduction impacts your taxable income is key to understanding your true tax liability.
Let's imagine a few scenarios:
Scenario 1: Full Deduction in a High-Tax State
- Meet Maria, a single filer in Colorado, which offers a full deduction for 529 contributions up to $50,000 for 2026. Colorado has a flat income tax rate of 4.40% for 2026.
- Maria contributes $5,000 to her child's Colorado 529 plan.
- Because of the deduction, Maria's taxable income for state purposes is reduced by $5,000.
- Her state tax savings: $5,000 (deduction) * 4.40% (Colorado tax rate) = $220.
- That $220 is a direct saving, essentially making her contribution $220 cheaper. Not bad for just saving for college!
Scenario 2: Partial Deduction or Tax Credit in Another State
- Consider David and Sarah, a married couple in Indiana, where contributions to the Indiana CollegeChoice 529 plan receive a 20% state tax credit on the first $5,000 contributed (up to a maximum credit of $1,000). A credit is even better than a deduction, as it directly reduces your tax bill dollar for dollar, rather than reducing your taxable income.
- They contribute $5,000 to their Indiana 529 plan.
- They receive a state tax credit of 20% of $5,000, which is $1,000.
- Their Indiana state tax bill is reduced by $1,000. This is a substantial saving and a huge incentive.
- It's vital to differentiate between deductions (which reduce taxable income) and credits (which reduce your tax bill directly). Both are valuable, but credits often provide a more immediate and noticeable benefit.
Carryforward Provisions: Some states are even more generous, allowing you to "carry forward" unused deductions. This means if you contribute more than your state's annual deduction limit in one year, you might be able to deduct the excess in future tax years until it's all used up. For example, if your state allows a $10,000 deduction per year, and you contribute $15,000, you might be able to deduct $10,000 this year and carry forward the remaining $5,000 to deduct next year. This is particularly useful for those who receive a large bonus or inheritance and want to make a substantial lump-sum contribution. It ensures you don't lose out on the deduction just because you contributed a lot at once. Make sure to check your state's specific rules, as these can vary widely.
Understanding these mechanics, including How State Tax Brackets Work: Marginal vs Effective, will help you truly appreciate the financial advantages a 529 plan can offer beyond just federal benefits.
A State-by-State Look at 529 Plan Tax Benefits
Navigating the landscape of 529 plan tax benefits across all 50 states can feel like a full-time job. It’s not just about whether a state has an income tax, but how it chooses to incentivize 529 contributions. The generosity and rules vary dramatically, making it essential to look up your specific state's provisions. For a general overview, this section breaks down the different approaches states take. Remember, tax laws can change, so always double-check with your state's tax department or a financial professional for the most current information for 2026 and beyond. A good starting point is often to review a comprehensive guide like State 529 Deduction Limits 2026 (All States).
States Offering a Full Tax Deduction
These are the states that offer the most direct incentive, allowing you to deduct your 529 contributions from your state taxable income, often up to a generous annual limit. The term "full" typically implies that the deduction applies to the entire amount you contribute, up to the stated cap, as opposed to a percentage or a credit.
For instance, states like New York offer a significant deduction: up to $10,000 for single filers and $20,000 for married couples filing jointly. This can translate into substantial savings, especially for higher earners. For example, if you're a married couple in New York contributing the maximum $20,000, and your highest state income tax bracket is around 6%, you could save $1,200 annually on your state tax bill. This is a powerful motivator for residents to invest in the New York 529 College Savings Program.
Other states, such as Illinois and Maryland, also offer full deductions. Illinois, for example, allows a deduction of up to $10,000 ($20,000 for joint filers) for contributions to its Bright Start or Bright Directions 529 plans. Maryland offers a deduction of up to $2,500 per beneficiary per year, with a carryforward provision for unused amounts, which is a fantastic feature allowing you to maximize the benefit over time. It’s always important to note whether these deductions are tied only to their in-state plans or if they extend to plans from other states. Most states offering generous deductions usually require you to use their own plan.
States Offering a Partial Tax Deduction or Credit
Some states provide a tax benefit, but it might not be a dollar-for-dollar deduction up to a high limit. Instead, they might offer a tax credit (which directly reduces your tax bill) or a deduction on a smaller portion of your contributions. This is where researching State Tax Credits: Solar, College & Dependent Care can give you a broader understanding of state incentives.
Indiana stands out with its particularly attractive tax credit. Residents can receive a 20% tax credit on contributions to the CollegeChoice 529 Plan, up to a maximum credit of $1,000 per taxpayer. So, if you contribute $5,000, you get a $1,000 credit, which is a direct reduction of your state tax liability. This is an incredibly strong incentive and often more valuable than a deduction of the same amount, as a credit provides a guaranteed dollar-for-dollar reduction in taxes owed.
Other states might offer smaller deduction caps or credits. For example, Georgia introduced a new flat tax rate for 2026 but offers a limited deduction for 529 contributions, generally capped per beneficiary. These partial benefits are still very worthwhile, but they require a bit more calculation to see their exact impact on your overall tax picture. They demonstrate that states are keen to encourage college savings, even if they can't offer the most generous incentives.
States with No State Income Tax or No Specific Deduction
Then we have states where the 529 plan tax benefits are non-existent, for one of two main reasons.
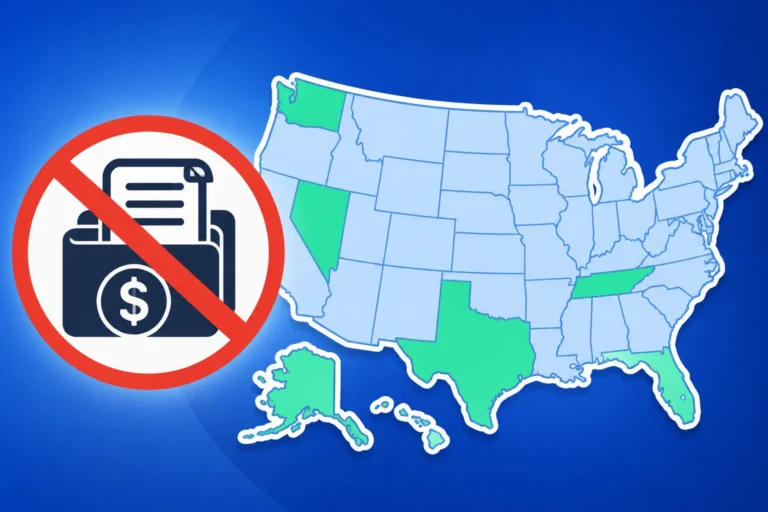
1. States with No State Income Tax: This is straightforward. If your state doesn't levy an income tax at all, then there's no state income tax from which to deduct your 529 contributions. For residents of these states, the primary benefit of a 529 plan remains the federal tax-free growth and withdrawals. These states include Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. New Hampshire taxes interest and dividends but not wages, and also does not offer a 529 deduction. For a complete list, you might refer to States With No Income Tax (2026 Full List). While you won't get a state deduction, living in one of these states already means a lower overall tax burden for many, so it’s not necessarily a disadvantage.
2. States with Income Tax but No 529 Deduction: This is perhaps the most frustrating category for residents. States like California, North Carolina, Kentucky, and Hawaii have state income taxes, but they do not offer a specific state income tax deduction or credit for 529 plan contributions. This means that while residents still enjoy the significant federal tax benefits of a 529 plan (tax-free growth and withdrawals for qualified expenses), they don't get that extra nudge from their state government in the form of a tax break. For Californians, whose state income tax rates can be among the highest, the absence of a 529 deduction is often a point of contention among financial planners. Despite this, it's still crucial for residents in these states to save for college, and 529 plans remain an excellent vehicle due to the federal advantages.
Here’s a quick summary table of common state approaches to 529 deductions and credits for illustrative purposes, but remember to verify specific amounts and requirements for 2026:
| State | Deduction/Credit Type | Annual Limit (Single/MFJ) Example | In-State Plan Required? | Notes |
|---|---|---|---|---|
| Alabama | Deduction | $5,000 / $10,000 | Yes | For contributions to Alabama’s Plan. |
| Arizona | Deduction | $2,000 / $4,000 | No | For contributions to ANY state's 529 plan. |
| Arkansas | Deduction | $5,000 / $10,000 | Yes | For contributions to Arkansas’s Plan. |
| California | None | N/A | N/A | Has income tax, but no 529 deduction/credit. |
| Colorado | Deduction | Unlimited (Carryforward) | No | For contributions to ANY state's 529 plan. |
| Connecticut | Deduction | $5,000 / $10,000 | Yes | For contributions to Connecticut’s Plan. |
| Delaware | None | N/A | N/A | Has income tax, but no 529 deduction/credit. |
| Florida | None (No state income tax) | N/A | N/A | Offers federal benefits only. |
| Georgia | Deduction | $2,000 / $4,000 | Yes | For contributions to Georgia’s Plan, with carryforward. |
| Idaho | Deduction | $6,000 / $12,000 | No | For contributions to ANY state's 529 plan. |
| Illinois | Deduction | $10,000 / $20,000 | Yes | For contributions to Illinois’s Plans. |
| Indiana | Credit | 20% of first $5,000 (Max $1,000) | Yes | For contributions to Indiana’s Plan. |
| Iowa | Deduction | $4,029 (per beneficiary) | Yes | For contributions to Iowa’s Plan, with carryforward. |
| Kansas | Deduction | $3,000 / $6,000 | No | For contributions to ANY state's 529 plan. |
| Kentucky | None | N/A | N/A | Has income tax, but no 529 deduction/credit. |
| Maryland | Deduction | $2,500 (per beneficiary) | Yes | For contributions to Maryland's Plans, with carryforward. |
| Massachusetts | Deduction | $1,000 / $2,000 | Yes | For contributions to Massachusetts's Plan. |
| Michigan | Deduction | $5,000 / $10,000 | Yes | For contributions to Michigan’s Plan, with carryforward. |
| Minnesota | Credit or Deduction | $500 Credit / $1,500 Deduction | No | Choice between credit (lower income) or deduction (higher income) for ANY state's plan. |
| Mississippi | Deduction | $10,000 / $20,000 | Yes | For contributions to Mississippi’s Plan. |
| Missouri | Deduction | $8,000 / $16,000 | No | For contributions to ANY state's 529 plan. |
| Montana | Deduction | $3,000 / $6,000 | Yes | For contributions to Montana’s Plan. |
| Nebraska | Deduction | $10,000 (per taxpayer) | Yes | For contributions to Nebraska’s Plan. |
| New Jersey | None | N/A | N/A | Has income tax, but no 529 deduction/credit. |
| New Mexico | Deduction | $5,000 / $10,000 | Yes | For contributions to New Mexico’s Plan, with carryforward. |
| New York | Deduction | $5,000 / $10,000 | Yes | For contributions to New York’s Plan. |
| North Carolina | None | N/A | N/A | Has income tax, but no 529 deduction/credit. |
| Ohio | Deduction | $4,000 (per beneficiary) | Yes | For contributions to Ohio’s Plan, with carryforward. |
| Oklahoma | Deduction | $10,000 / $20,000 | No | For contributions to ANY state's 529 plan. |
| Oregon | Credit | Up to $150 / $300 | Yes | Income-based credit for contributions to Oregon’s Plan. |
| Pennsylvania | Deduction | $17,000 / $34,000 | No | For contributions to ANY state's 529 plan. |
| Rhode Island | Deduction | $500 / $1,000 | Yes | For contributions to Rhode Island’s Plan. |
| South Carolina | Deduction | Unlimited (Carryforward) | Yes | For contributions to South Carolina’s Plan. |
| Utah | Credit | Up to $100 / $200 | Yes | Income-based credit for contributions to Utah’s Plan. |
| Vermont | Credit | 10% of first $2,500 | Yes | For contributions to Vermont’s Plan. |
| Virginia | Deduction | Unlimited (Carryforward) | Yes | For contributions to Virginia’s Plans. |
| West Virginia | Deduction | $50,000 (per taxpayer) | Yes | For contributions to West Virginia’s Plan. |
| Wisconsin | Deduction | $3,860 (per beneficiary) | Yes | For contributions to Wisconsin’s Plan. |
Note: This table provides general information and representative limits, which can change. Always verify current figures and specific requirements with your state’s official resources.
Key Considerations When Choosing a 529 Plan
Deciding on a 529 plan isn't just about picking the one with the snazziest name or the most aggressive investment options. There are several critical factors that can significantly impact your potential tax benefits and overall savings strategy. It really pays to do your homework here, because a misstep could cost you precious deductions or even lead to unexpected penalties.
Residency Rules and Their Impact on Deductions
Your state of residence plays an absolutely huge role in determining your 529 plan tax benefits. This might sound obvious, but the nuances can be incredibly tricky, especially if you're a mover, a remote worker, or a snowbird.
First off, as we discussed, many states offer a tax deduction only if you're a resident contributing to their state's specific 529 plan. So, if you're a New York resident, you'll generally need to contribute to the New York 529 plan to get that state deduction. If you decide to go with, say, the Fidelity Arizona 529 Plan because you like their investment options, you'll forgo the New York state income tax deduction, even though you still get the federal benefits. This creates a decision point: prioritize the state tax deduction with your home state's plan, or choose a plan from another state that you feel offers better investment choices, fees, or performance, even if it means no state deduction.
What happens if you move? This is where it gets really complicated. Let's say you've been a resident of Illinois, diligently contributing to their Bright Start 529 plan and enjoying those generous state deductions. Then, you decide to move to California, a state that offers no 529 state income tax deduction. While you'll continue to enjoy federal tax benefits, you won't get any new state deductions from California. More importantly, some states have "recapture" provisions. This means if you move out of the state or roll your funds out of that state's plan, they might "recapture" the deductions you previously took, meaning you'd have to pay back the tax savings on those contributions. This is a crucial detail that often catches people off guard. For a deeper dive into these complexities, understanding State Tax Residency Rules Explained is absolutely vital. Always check your state's specific rules regarding changes in residency and 529 plans before making a move or a significant fund transfer.
Contribution Limits and Carryforward Rules
While the federal government has very high (practically unlimited for most families) lifetime contribution limits for 529 plans, and generous gift tax exclusion rules, individual states often impose their own, much lower, limits for deducting contributions from your state taxable income. These are not limits on how much you can contribute to the 529 plan itself, but rather on how much of those contributions you can deduct in a single tax year.
For example, a state might allow you to deduct up to $10,000 for single filers and $20,000 for married couples filing jointly, even if you contribute more than that to the 529 plan. These limits are typically on an "account owner" basis, not a "beneficiary" basis, meaning you can typically deduct the full amount for each separate account you own. So, if you have two children and contribute $10,000 to each of their 529 plans, you might be able to deduct $20,000 in some states. It’s important to clarify if the limit is per taxpayer or per beneficiary.
Beyond the annual deduction limit, many states offer a fantastic feature called "carryforward." This means if you contribute more than the maximum deductible amount in a given year, you don't necessarily lose out on the deduction for the excess. Instead, you can "carry forward" the unused portion of your contribution and deduct it in subsequent tax years, until it's fully utilized or a certain number of years pass. For instance, if your state has a $10,000 annual deduction limit and you contribute $15,000 in one year, you might deduct $10,000 this year and then deduct the remaining $5,000 next year. This is particularly beneficial if you receive a large windfall, like a bonus or an inheritance, and want to make a substantial lump-sum contribution without losing out on all your state tax benefits. Always check if your state offers carryforward provisions and for how many years they are valid. This strategic planning can significantly maximize your total state tax savings over time.
Beyond the Deduction: Other State 529 Plan Perks
While state tax deductions are a huge draw for 529 plans, the benefits don't always stop there. Many states recognize the importance of encouraging college savings and have implemented additional programs and features to make their 529 plans even more attractive. These extra perks can add significant value, especially for certain families or those looking to maximize their overall financial planning strategy.
Grant and Scholarship Programs
Beyond just offering a deduction or credit, some states actually provide direct financial incentives through grant or scholarship programs tied to their 529 plans. These initiatives are often designed to help lower and middle-income families kickstart their college savings, or to reward consistent saving.
For example, Maryland has a unique program known as the State Higher Education Investment Program (SHEIP). Through this program, eligible families who contribute to a Maryland 529 plan might receive a matching grant on their contributions. This is essentially free money on top of your own savings and any tax deductions you might qualify for. These programs usually have income limitations or specific contribution requirements, but for those who qualify, they can dramatically accelerate the growth of your college savings.
Other states might offer smaller, one-time grants or even scholarships that prioritize students who have been saving through their state's 529 plan. The idea is to not only incentivize initial contributions but to make the act of saving a more tangible and rewarding experience. It's really worth checking your specific state's 529 plan website for these kinds of programs, as they are truly "hidden gems" that can provide a huge boost to your savings efforts. These aren't always widely advertised, so a little digging can uncover significant opportunities.
Gift Tax Benefits and Estate Planning
While the federal gift tax exclusion is a cornerstone benefit of 529 plans, many states align with these federal rules, offering additional state-level advantages for wealthy families and those engaging in estate planning. The ability to make substantial contributions to a 529 plan and immediately remove those assets from your taxable estate is a powerful tool.
Let's consider the mechanics: you can contribute up to $18,000 per person per year (in 2024) to a 529 plan without it counting against your lifetime gift tax exemption. What's even more remarkable is the "superfunding" provision, allowing you to contribute up to five years' worth of gifts at once ($90,000 for an individual or $180,000 for a married couple in 2024) without gift tax consequences, provided you don't make any other gifts to that beneficiary for five years. This can significantly reduce the size of your taxable estate, which is a major concern for high-net-worth individuals. By transferring assets into a 529 plan, those funds are no longer considered part of your estate upon your passing, potentially saving your heirs a substantial amount in estate taxes.
Furthermore, the account owner retains control over the assets in the 529 plan, even though the contributions are considered completed gifts. You can change the beneficiary to another eligible family member, or even take the money back (though non-qualified withdrawals would incur federal income tax on earnings plus a 10% penalty, and potentially state income tax recapture on previously deducted amounts). This combination of control, tax-free growth, and estate exclusion makes 529 plans an incredibly versatile tool for affluent families looking to manage their wealth while planning for future generations' education expenses. The ability to remove assets from your estate while still retaining a degree of control is a unique feature that few other investment vehicles offer.
Navigating the Nuances: Common 529 Plan Scenarios
Like any powerful financial tool, 529 plans come with their own set of rules and potential pitfalls. It’s not enough to simply open an account and contribute; understanding what happens in various scenarios can save you from unexpected tax headaches down the road. Life is unpredictable, and sometimes, even the best-laid plans need to change. Being aware of the consequences of these changes is part of being a savvy saver.
What Happens if You Withdraw for Non-Qualified Expenses?
This is probably the most crucial "what if" scenario to understand. The whole beauty of a 529 plan lies in its tax-free growth and withdrawals for qualified education expenses. But what if your child decides not to go to college, gets a full scholarship, or you need the money for something else entirely?
If you make a withdrawal for non-qualified expenses, you're looking at a two-pronged attack:
- Federal Penalties: The earnings portion of the non-qualified withdrawal will be subject to federal income tax and an additional 10% federal penalty tax. This means all that lovely tax-free growth you enjoyed for years suddenly becomes taxable, plus you get hit with a penalty for not using it as intended. This can really eat into your savings, so it's a strong disincentive for using the funds improperly.
- State Recapture: This is where the state tax deductions you enjoyed become relevant again. Many states that offer a tax deduction for 529 contributions have "recapture" provisions. This means if you took a state income tax deduction for your contributions and then later make a non-qualified withdrawal, the state may require you to "recapture" those deductions. Essentially, they'll add the amount you previously deducted back into your state taxable income for the year you made the non-qualified withdrawal. This effectively negates the tax savings you received earlier. For instance, if you're in New York, deducted $10,000, and then used that money to buy a new car instead of tuition, you might owe New York state income tax on that $10,000 in the year of the withdrawal. This can come as a nasty surprise if you're not prepared. Not all states have recapture rules, but a significant number do, especially those with generous deductions. It's a critical detail to verify for your specific state's plan.
The takeaway here is clear: 529 plans are fantastic for qualified education expenses, but straying from that path comes with financial repercussions. Always try to exhaust all qualified expenses first, including K-12 tuition, apprenticeship programs, or even student loan repayments, before resorting to non-qualified withdrawals.
Changing Beneficiaries or Plans
Life happens, and sometimes the original beneficiary of a 529 plan might not be the one who ends up using the funds. Perhaps your eldest received a scholarship, or your younger child is now showing more academic promise. The good news is that 529 plans offer significant flexibility in these situations without triggering penalties.
Changing the Beneficiary: You can change the beneficiary of a 529 plan to another eligible family member without any federal tax consequences or penalties. An eligible family member is broadly defined and includes siblings, children, grandchildren, nieces, nephews, and even the account owner themselves. This flexibility means your savings are not locked into one child. If one child decides not to pursue higher education, or simply has leftover funds, you can easily transfer the benefits to another child, grandchild, or even to yourself if you decide to go back to school! This is a major advantage that provides peace of mind that your savings won't go to waste.
Rolling Over Funds to a Different Plan: You're also not stuck with the original 529 plan you chose forever. You can roll over funds from one 529 plan to another 529 plan, once every 12 months, for the same beneficiary without federal tax consequences. You might do this if you find a plan from another state with lower fees, better investment options (like those offered by Vanguard or Fidelity), or a superior historical performance. This provides an escape hatch if your chosen plan isn't meeting your expectations.
However, be mindful of state-specific rules when doing a rollover, especially if you received a state tax deduction for contributions to the original plan. If you move funds out of your home state's plan to an out-of-state plan, some states might still trigger those recapture provisions we just talked about, effectively clawing back previous state tax deductions. Always verify these rules before initiating a rollover to ensure you don't inadvertently create a state tax liability. The flexibility is a huge perk, but it comes with a homework assignment!
Putting It All Together: Maximizing Your 529 Benefits
You've learned about the federal benefits, the varied state deductions, and the important rules to navigate. Now, how do you synthesize all this information to create the best strategy for your family? It's about looking at the big picture and making informed choices that align with your financial goals and your specific state's tax landscape. This can truly help you to How to Lower Your State Income Tax effectively while saving for education.
Comparing Plans with Different State Benefits
This is arguably the most critical step after understanding your state's specific deduction rules. As a resident, you might feel compelled to stick with your home state's 529 plan to get that sweet state tax deduction. And often, that's the smart move! For example, if you live in Illinois and can deduct up to $20,000 annually for contributions to an Illinois 529 plan, that's a significant tax break that could easily outweigh slight differences in fees or investment performance from an out-of-state plan.
However, the state tax deduction isn't the only factor. Sometimes, an out-of-state 529 plan might offer such superior investment options, lower fees, or a better track record that it makes more financial sense to choose it, even if it means sacrificing your state tax deduction. This is especially true for residents of states that offer no 529 deduction (like California) or states that do offer a deduction but allow it for any state's plan (like Arizona or Kansas). In these cases, you have the ultimate freedom to shop around for the plan that truly stands out in terms of investment quality and low costs. Many plans are managed by reputable financial institutions like Vanguard, Fidelity, T. Rowe Price, or American Funds, and their offerings can vary widely in terms of fund selection, expense ratios, and asset allocation strategies.
When comparing, consider the following:
- Investment Options: Does the plan offer a range of diversified, low-cost index funds or actively managed portfolios that align with your risk tolerance?
- Fees: Compare expense ratios, administrative fees, and any other charges. Even small differences in fees can add up to tens of thousands of dollars over 18 years of saving.
- Performance History: While past performance doesn't guarantee future results, it can give you an idea of how well a plan's investment options have performed against benchmarks.
- Ease of Use: How user-friendly is the online platform? How easy is it to contribute, change investments, or make withdrawals?
A common scenario: A family in New Jersey (a state with no 529 deduction) might choose to invest in the New York 529 plan because it offers excellent, low-cost options through Vanguard, or perhaps Utah's my529 plan, which is consistently ranked as one of the best overall plans in the nation by independent evaluators. Since they won't get a New Jersey state deduction anyway, they can pick the plan that offers the best investment value. This is where tools from financial platforms like SmartAsset can be incredibly helpful in comparing plans side-by-side, analyzing investment options, and getting a clearer picture of potential returns. (Brand mention 1)
Tools and Resources to Help You Decide
Making an informed decision about your 529 plan, especially when state tax deductions are on the table, requires access to reliable information and helpful tools. Thankfully, there are many resources available to guide you through the process.
State 529 Plan Websites: Every state that offers a 529 plan has a dedicated website. These sites are your primary source for accurate, up-to-date information on their specific plan, including current deduction limits, eligibility requirements, investment options, fees, and any unique features like matching grants or carryforward provisions. Look for terms like "official disclosure statement" or "program description" as these documents contain all the crucial details.
Financial Advisors: If you find yourself overwhelmed by the choices or unsure how a 529 plan fits into your broader financial picture, a qualified financial advisor specializing in college planning can be an invaluable resource. They can help you assess your risk tolerance, choose appropriate investment allocations, and integrate your 529 strategy with other financial goals like retirement savings.
Online Comparison Tools: Websites like Savingforcollege.com or SmartAsset (Brand mention 2) offer robust comparison tools that allow you to pit different 529 plans against each other. You can filter by state, investment options, fees, and performance, giving you a holistic view. These tools are fantastic for narrowing down your options and identifying plans that align with your preferences, even if they're out-of-state.
Tax Software: When it comes time to file your taxes, good tax software is essential for accurately claiming your state 529 deduction or credit. Programs like TurboTax are designed to walk you through the process, asking questions about your contributions and automatically calculating your eligible state deductions based on your residency and the plan you contributed to. (Brand mention 3) This ensures you don't miss out on valuable tax savings due to an oversight. Always remember to keep detailed records of your contributions.
Staying Updated: Tax laws and 529 plan rules can change. States occasionally adjust their deduction limits, introduce new plans, or modify existing rules. Keep an eye on legislative updates, especially for State Income Tax Cuts & Changes for 2026 which might impact state-level benefits. Subscribing to newsletters from your state's 529 plan or reputable financial news outlets can help you stay in the loop. The more informed you are, the better positioned you'll be to maximize the power of your 529 plan for your family's future educational needs.
Disclaimer
Please remember that tax laws are complex and subject to change. This guide provides general information about 529 plan tax deductions by state for informational purposes only and should not be considered tax or financial advice. We strongly recommend consulting with a qualified tax professional or financial advisor to discuss your individual circumstances and to get the most up-to-date information for your specific state and situation.