13 States With No Retirement Income Tax
It's a common worry for many people as they approach their golden years: how much of their hard-earned retirement savings will be eaten away by state taxes? This guide is designed to cut through the confusion and highlight the 13 states where your pension, 401(k), IRA, or Social Security distributions won't face a state income tax, helping you make informed decisions about where to enjoy your retirement.
The Retirement Income Tax Landscape: Why It Matters
When you're planning for retirement, every dollar truly counts. You've spent decades diligently saving, perhaps contributing to a 401(k), IRA, or a traditional pension plan, and looking forward to drawing from that nest egg. The last thing you want is for a significant chunk of it to vanish into state coffers simply because you chose the wrong place to live out your retirement dreams. Understanding the nuances of state income tax, especially as it pertains to retirement income, is absolutely crucial for maximizing your financial well-being in your later years.
Understanding the Impact on Your Nest Egg
Imagine you've saved a healthy sum, and you're projecting a certain annual income from your retirement accounts. If your chosen state levies a tax on that income, your purchasing power immediately diminishes. This isn't just a minor inconvenience; it can significantly alter your lifestyle, affect your ability to travel, enjoy hobbies, or cover unexpected medical expenses. For example, if you're drawing $60,000 annually and your state has a 5% income tax on retirement distributions, that's $3,000 less in your pocket each year – money that could have gone towards living expenses or a well-deserved cruise.
Furthermore, state taxes can indirectly influence other financial decisions. High income taxes might make you rethink converting a traditional IRA to a Roth IRA, for instance, if the state also taxes that conversion. Or it might compel you to adjust your withdrawal strategy to minimize your taxable income each year. It’s not just about what you pay, but how it shapes your entire financial planning process. Resources that help you compare various tax burdens, like those offered by SmartAsset, can be particularly valuable in illustrating these impacts.
Distinguishing "No Income Tax" from "No Retirement Income Tax"
This is where things can get a little tricky, and it's important to clarify the terminology. When we talk about "states with no income tax," we're generally referring to the states that don't tax any form of earned income, investments, or general income. However, some states do have a general income tax, but they offer specific, robust exemptions for retirement income —meaning pensions, 401(k) withdrawals, IRA distributions, and Social Security benefits might be completely untaxed at the state level.
Our focus today is on the broader group: states that will not tax your retirement income, whether that's because they have no income tax at all, or because they have specific policies to exempt those golden-year earnings. This distinction is vital because a state might look tax-friendly on paper if it doesn't have a high general income tax, but still ding you on retirement distributions. Conversely, a state with a seemingly high income tax might be surprisingly kind to retirees. We'll explore both categories to give you the full picture. For a broader overview, you might want to read about the full list of states with no income tax.
States with No General Income Tax: The Core Eight
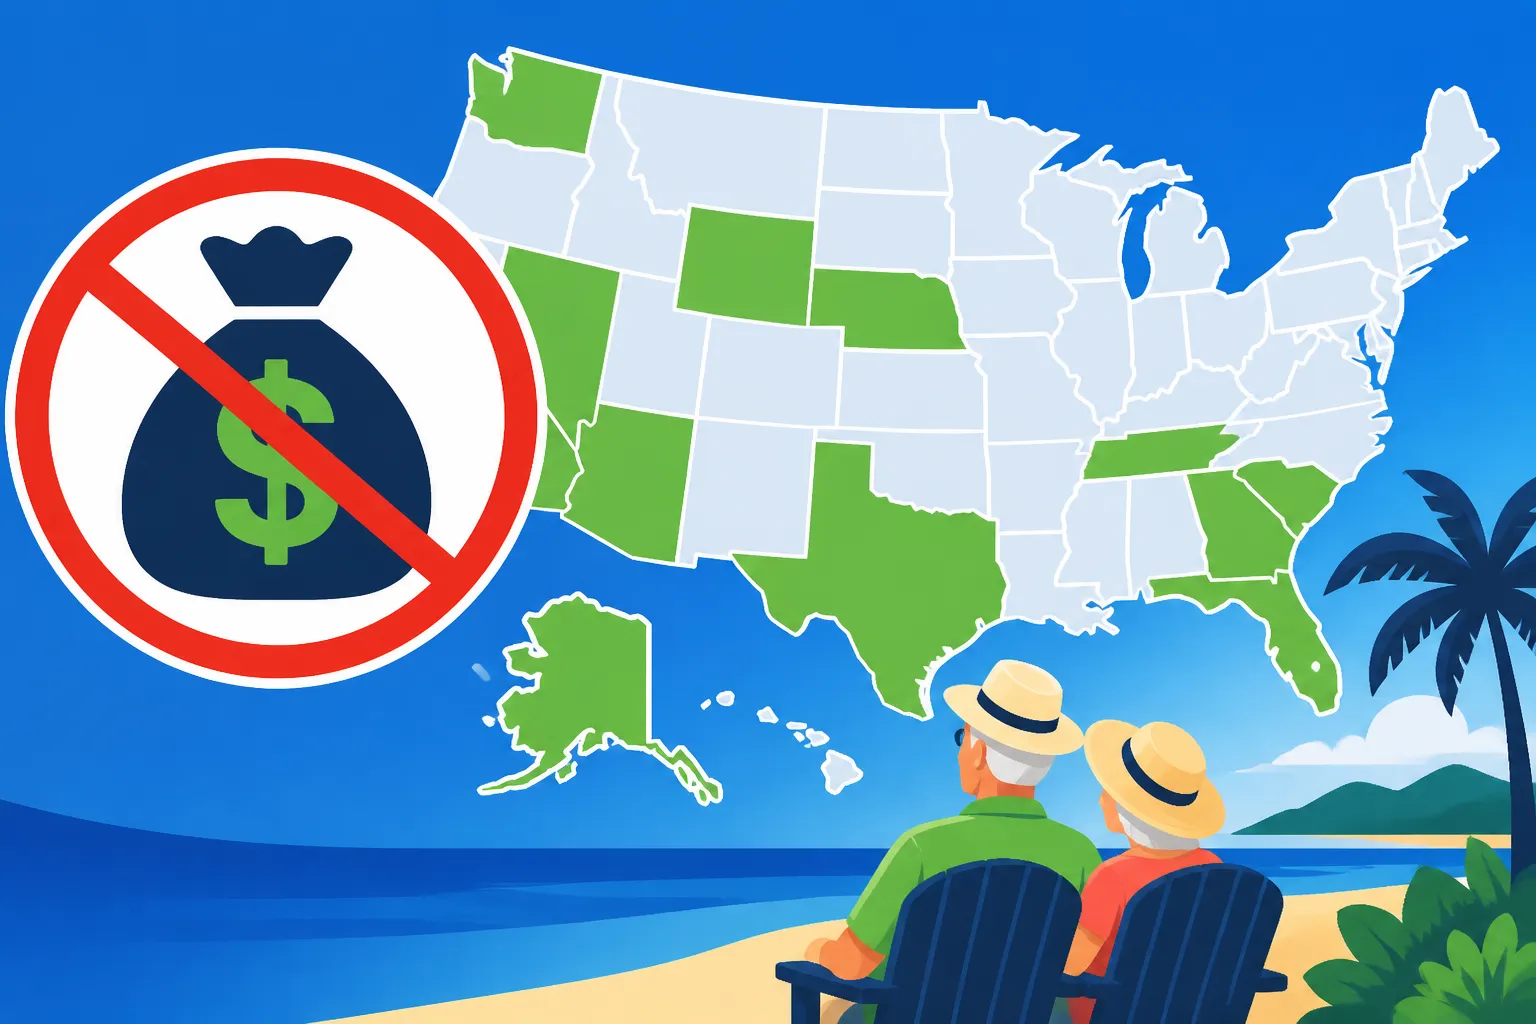
These eight states are often the first ones people think of when discussing tax-friendly places to retire, and for good reason. They simply do not impose a state income tax on any earnings, which naturally includes all forms of retirement income like pensions, 401(k) and IRA withdrawals, and Social Security benefits. This straightforward approach eliminates a major tax burden right off the bat, making financial planning much simpler for retirees.
Alaska: A Unique Tax Picture
The Last Frontier offers a truly unique tax environment. Not only does Alaska not have a state income tax, but it also has no statewide sales tax (though local sales taxes can apply) and no state property tax (again, local property taxes are collected). What really sets Alaska apart is its Permanent Fund Dividend, which pays residents an annual dividend from the state's oil revenues. While not directly a retirement benefit, it's an additional source of income that is also untaxed by the state.
Living in Alaska certainly comes with its own set of challenges, from the harsh winters to the remote locations. However, for those who embrace the rugged beauty and unique lifestyle, the tax benefits are undeniable. Retirees here can enjoy their pension and investment income without worrying about a state income tax deduction, leaving more money for exploring the vast wilderness or enjoying local cultural events. It’s a compelling option for the adventurous, tax-conscious retiree.
Florida: The Sunshine State's Appeal
Florida is practically synonymous with retirement, and its tax policies are a huge part of its allure. The state boasts no state income tax, meaning your retirement pensions, 401(k) distributions, and IRA withdrawals are all entirely exempt. This, coupled with its warm climate and abundant beaches, makes it a perennial favorite for those looking to stretch their retirement dollars. Many people ponder, "Does Florida tax retirement income?" and the simple answer is no.
While Florida might be a haven from income tax, it’s important to remember that other taxes exist. Sales taxes are collected statewide and locally, and property taxes can be quite significant, especially in desirable coastal areas. However, the lack of an income tax still provides a substantial advantage for many retirees, especially those with considerable retirement savings. It's a common destination for those moving from high-tax states, often prompting questions like, "How to establish Florida domicile?" to ensure those tax benefits are fully realized.
Nevada: Desert Oasis for Retirees
Another popular destination, Nevada, offers the dry heat of the desert alongside a very dry tax climate for retirees. There is no state income tax, which means all forms of retirement income are free from state-level taxation. This extends to pensions, 401(k) and IRA distributions, and Social Security benefits. For retirees looking for entertainment, golf, or simply a relaxed pace, Nevada presents an attractive option.
Like Florida, Nevada does rely on other forms of taxation to fund state services, including sales tax and property tax. Sales tax rates can be relatively high in some areas, especially around tourist hubs like Las Vegas. However, the absence of an income tax remains a powerful incentive for retirees, allowing them to keep more of their monthly income. The tax savings can be substantial, especially for those with higher retirement incomes.
South Dakota: Great Plains, Low Taxes
Often overlooked, South Dakota is a hidden gem for tax-friendly retirement. It's one of the few states with no state income tax, making it a highly attractive option for retirees looking to protect their pensions, 401(k)s, and IRAs from state taxation. Social Security benefits are also completely untaxed by the state. The cost of living in South Dakota is generally lower than the national average, further enhancing its appeal for budget-conscious retirees.
The state also boasts relatively low property taxes compared to many other parts of the country, though sales taxes are present. For those who appreciate wide-open spaces, a slower pace of life, and a strong sense of community, South Dakota offers a fiscally prudent choice. It's an excellent example of a state that truly provides a low-tax environment across multiple categories, not just income.
Tennessee: The Volunteer State's Tax Freedom
Tennessee used to have a limited "Hall Tax" on interest and dividend income, but this tax was fully repealed as of January 1, 2021. This means Tennessee now officially has no state income tax on wages or investment income, including all forms of retirement income like pensions, 401(k) and IRA withdrawals, and Social Security benefits. Many prospective residents frequently ask, "Does Tennessee have state income tax?" and the answer is now a resounding no.
Beyond the income tax benefits, Tennessee offers a low cost of living, beautiful natural landscapes, and a rich cultural heritage, particularly in its music cities like Nashville and Memphis. While sales taxes are among the highest in the nation, and property taxes vary by county, the complete absence of an income tax makes Tennessee a very strong contender for retirees looking to make their retirement savings last longer.
Texas: Everything's Bigger, Except Income Tax
True to its reputation, everything in Texas might be bigger, but its state income tax rate is zero. This makes Texas a significant draw for retirees, who can rest assured that their pensions, 401(k)s, IRAs, and Social Security benefits will not be subjected to state income taxation. This allows retirees to enjoy their full distributions, whether they settle in the bustling cities or the tranquil countryside. People often wonder, "Does Texas tax retirement income?" The answer is no, making it highly attractive.
However, like many states without an income tax, Texas makes up for it with other levies, most notably property taxes, which are among the highest in the country. Sales taxes are also significant. Therefore, while the lack of income tax is a huge plus, potential residents need to factor in these other costs. For a comprehensive comparison, you might consider articles like "California vs Texas Taxes Compared" to see the full picture.
Washington: The Evergreen State's Income Tax Exception
Washington State is well-known for not having a personal income tax. This means all forms of retirement income, including Social Security, pensions, and withdrawals from 401(k)s and IRAs, are entirely exempt from state taxation. This is a significant benefit for retirees who want to enjoy the state's stunning natural beauty, from its rugged coastlines to its majestic mountains, without a state income tax burden.
It's worth noting that Washington recently implemented a 7% capital gains tax on high earners, which applies to certain long-term capital gains exceeding a high threshold. However, this tax generally does not apply to typical retirement income distributions like pensions or 401(k) withdrawals, and there are exemptions. For most retirees, this new tax will not impact their regular retirement income. Property and sales taxes are present and can be substantial, especially in metropolitan areas like Seattle, so it’s essential to consider the overall tax burden.
Wyoming: The Equality State's Tax Perks
Wyoming consistently ranks as one of the most tax-friendly states in the nation, and its lack of a state income tax is a primary reason. Retirees in Wyoming will not pay state income tax on any of their retirement income, including pensions, 401(k) and IRA distributions, or Social Security benefits. This straightforward tax policy, combined with a generally low cost of living, makes it a very appealing choice for those seeking financial peace of mind.
In addition to no state income tax, Wyoming also has no state sales tax on groceries and very low property taxes. The state generates much of its revenue from mineral extraction, which helps keep the burden on residents low. For those who love the outdoors, wide-open spaces, and a relaxed, uncrowded lifestyle, Wyoming offers a truly advantageous tax situation for retirees.
States That Fully Exempt Retirement Income (Even with General Income Tax)
While the previous eight states stand out for having no general income tax, this next group of five states is equally attractive to retirees because they specifically exempt most or all forms of qualified retirement income from their state income tax, even though they do have a broader income tax for other types of earnings. This distinction is crucial for many retirees, as it effectively means their pensions, 401(k)s, and IRAs are untaxed at the state level, just like in the no-income-tax states.
Illinois: The Prairie State's Retirement Exemption
Illinois is a prime example of a state with a general income tax that is exceptionally friendly to retirees. The Prairie State specifically exempts all qualified retirement income from state income tax. This includes income from private and public pensions, 401(k)s, IRAs, and Social Security benefits. So, despite having a flat income tax rate on wages, your distributions from retirement accounts are safe from state taxation here.
This broad exemption makes Illinois a very popular choice for retirees who want to remain in the Midwest or those moving to be closer to family in the region. While property taxes can be quite high in Illinois, particularly in the Chicago metropolitan area, the complete exemption of retirement income can still lead to substantial tax savings for many. It's a significant financial relief that often makes up for other tax burdens, especially for those with substantial retirement nest eggs.
Iowa: New Tax Benefits for Retirees
Iowa has recently made significant strides to become more tax-friendly for retirees. Starting in tax year 2023, the state began fully exempting retirement income for individuals aged 55 and older. This means pensions, annuities, 401(k) distributions, and IRA withdrawals are now completely excluded from state income tax for eligible retirees. This policy change dramatically improves Iowa's appeal as a retirement destination.
Prior to this change, Iowa did tax retirement income, making this a major shift in its tax landscape. Now, combined with a relatively low cost of living and a friendly community atmosphere, Iowa presents a compelling option. While the state still has a progressive income tax on other forms of income and sales and property taxes apply, the blanket exemption for retirement income provides substantial financial relief for eligible seniors.
Mississippi: Southern Comfort and Tax Relief
Mississippi, known for its Southern hospitality and charm, also offers a very generous tax policy for retirees. The state exempts all qualified retirement income from state income tax. This includes income from pensions, 401(k)s, IRAs, and Social Security benefits. Retirees can enjoy their distributions without a state tax liability, making their money go further in a state with a generally low cost of living.
While Mississippi has a progressive income tax on other forms of income, its comprehensive retirement income exemption makes it a highly attractive option for seniors. Sales taxes and property taxes are present, but the overall tax burden for retirees, particularly those with significant retirement income, can be quite favorable. For many, the combination of a warm climate, affordable living, and tax relief on retirement earnings makes Mississippi an appealing choice.
New Hampshire: Interest and Dividends Nuance
New Hampshire is often listed among states with no income tax, and it's true that it does not tax earned wages. However, it has historically taxed interest and dividend income, which could affect some retirees with specific investment portfolios. The good news is that New Hampshire's tax on interest and dividends is being phased out, with a full repeal slated for 2027. For 2026, the tax rate continues to decrease, making it less impactful. Crucially, New Hampshire does not tax income from pensions, 401(k)s, or IRA withdrawals, nor does it tax Social Security benefits.
This means that for the vast majority of retirees relying on distributions from traditional retirement accounts, New Hampshire is effectively a no-retirement-income-tax state. Its scenic beauty, charming towns, and proximity to major East Coast cities make it an attractive option for those looking for a New England retirement without the state income tax burden on their primary retirement funds. Property taxes in New Hampshire can be among the highest in the nation, so it's a significant factor to consider. If you’re considering moving, understanding something like the new New Hampshire interest & dividends tax repeal is essential.
Pennsylvania: Keystone State's Retirement Haven
Pennsylvania is another excellent example of a state that, despite having a flat income tax rate, provides a full exemption for most qualified retirement income. Specifically, distributions from Social Security, eligible pensions, and all retirement accounts (like 401(k)s and IRAs) are generally exempt from state income tax for individuals age 60 and older. This generous exemption makes Pennsylvania a top contender for retirees looking for tax relief on their golden-year earnings.
The state offers a diverse landscape, from bustling cities like Philadelphia to serene rural areas, providing a wide range of living environments. While sales taxes apply, and property taxes can vary significantly by locality, the comprehensive exemption of retirement income provides a substantial financial advantage. This policy makes Pennsylvania particularly appealing for those who wish to age in place or move to an area rich in history and culture without facing a state tax on their primary retirement funds.
| State | General State Income Tax | Taxes Pensions, 401(k), IRAs? | Taxes Social Security? | Average State Sales Tax Rate (Approx. 2026) | Average Effective Property Tax Rate (Approx. 2026) | Notes |
|---|---|---|---|---|---|---|
| Alaska | No | No | No | No statewide (local varies) | 1.02% | No general income tax, no statewide sales tax. |
| Florida | No | No | No | 6.00% | 0.98% | No general income tax. |
| Nevada | No | No | No | 6.85% | 0.52% | No general income tax. |
| South Dakota | No | No | No | 4.50% | 1.09% | No general income tax. |
| Tennessee | No (Hall Tax Repealed) | No | No | 7.00% | 0.65% | No general income tax since Hall Tax repeal (2021). |
| Texas | No | No | No | 6.25% | 1.69% | No general income tax, but relatively high property taxes. |
| Washington | No | No | No | 6.50% | 0.93% | No general income tax, but has a capital gains tax (with high threshold and exemptions for most retirees). |
| Wyoming | No | No | No | 4.00% | 0.61% | No general income tax, very low property taxes. |
| Illinois | Yes | No | No | 6.25% | 2.08% | Exempts all qualified retirement income (pensions, 401k, IRAs, SS). |
| Iowa | Yes | No (age 55+) | No | 6.00% | 1.54% | Fully exempts retirement income for those aged 55+ (effective 2023). |
| Mississippi | Yes | No | No | 7.00% | 0.82% | Exempts all qualified retirement income (pensions, 401k, IRAs, SS). |
| New Hampshire | No (Earned Income) | No | No | No statewide (local varies) | 1.89% | Taxes interest and dividends (phasing out, fully repealed 2027), but not pensions, 401k/IRAs, or SS. High property taxes. |
| Pennsylvania | Yes | No (age 60+) | No | 6.00% | 1.56% | Exempts qualified retirement income (pensions, 401k, IRAs, SS) for individuals age 60+. |
Note: Sales and property tax rates are approximate averages and can vary significantly by local jurisdiction. Always verify current rates for specific areas.
Looking Beyond Income Tax: A Comprehensive View
While the absence of a state tax on your retirement income is a massive advantage, it's really just one piece of the puzzle when choosing a retirement location. Many states that forgo income taxes make up for that revenue through other means. It’s crucial to look at the entire tax picture – from sales tax to property tax and even various local fees – to truly understand the cost of living and how it will impact your retirement budget. A state that seems "tax-friendly" on paper might still end up being more expensive overall if these other taxes are particularly high.
Sales Taxes: Daily Costs to Consider
Sales taxes are levied on goods and services you purchase, and they can vary significantly from state to state, and even from city to city within a state. While a few states have no statewide sales tax, most do, and it can add up quickly. For instance, if you're living on a fixed income, every time you buy groceries, go out to eat, or make a larger purchase like a new appliance, that sales tax takes a bite out of your budget.
States with no income tax often have higher sales tax rates to compensate. For example, Tennessee has one of the highest combined state and local sales tax rates in the country, even though it doesn't tax retirement income. You might save on your pension, but you'll pay more for almost everything else. Tools provided by services like SmartAsset can help you compare these rates side-by-side, giving you a clearer picture of your daily spending power in different locations.
Property Taxes: A Major Retirement Expense
For most homeowners, property taxes represent one of the most significant annual expenses, and they are definitely something to factor into your retirement planning. These taxes are generally levied by local governments (counties, cities, school districts) and are based on the assessed value of your home. Like sales taxes, property tax rates vary wildly across the country.
Consider Texas, which has no income tax but is known for having some of the highest property taxes in the nation. While you won't pay state income tax on your earnings, the annual property tax bill could be a substantial burden, especially if you plan to own a home. Some states offer homestead exemptions or property tax credits for seniors, which can help offset these costs. Understanding these specific local deductions and credits, like those discussed in "Property Tax Credits & Homestead Exemptions by State", is vital. You also need to consider how your home’s value might change over time, potentially impacting your property tax liability.
Other Local Taxes and Fees
Beyond sales and property taxes, don't forget about other, often smaller but still impactful, local taxes and fees. These can include vehicle registration fees, excise taxes on certain goods (like gasoline or tobacco), and local city income taxes in some areas. While these might seem minor individually, they can collectively add up.
For instance, even in a state with no state income tax, some municipalities might have their own local income or wage taxes. Although none of the 13 states discussed today currently have broad local income taxes that would apply to general retirement income, it’s a good practice to research all levels of taxation. For example, some states may have significant intangible personal property taxes on things like investment accounts, although these are becoming rarer. Being aware of these additional costs helps paint a truly accurate picture of your overall financial burden in retirement. You might find more information on this in guides like "Local & City Income Taxes in the US".
Making the Move: Establishing and Maintaining Tax Residency
Choosing a tax-friendly state is one thing; actually realizing those benefits by establishing legal residency is another entirely. State tax authorities are vigilant, especially if they suspect you're trying to claim residency in a low-tax state while still maintaining significant ties to a high-tax state. It's not enough to simply change your driver's license; you need to genuinely sever ties with your old state and establish deep roots in your new one to avoid potential audits and double taxation.
Proving Domicile to State Tax Authorities
"Domicile" is the legal term for your true, fixed, and permanent home – the place where you intend to return whenever you are absent. Proving domicile is paramount, as state tax agencies look for clear evidence of your intent to make a new state your permanent home. This goes far beyond the simple "183-day rule for state taxes," which is a statutory residency test, not necessarily a domicile test.
State auditors will scrutinize a variety of factors, often referred to as the "domicile test." They'll look at where you vote, register your vehicles, have your professional licenses, keep your most cherished possessions, maintain your primary bank accounts, and even where your pets' veterinarian is located. Changing these key indicators immediately and consistently is crucial. If you maintain a primary residence in New York and also own a condo in Florida, but spend more time in Florida, New York's tax authorities might still consider you a resident unless you've clearly established Florida as your legal domicile. Understanding the difference between "domicile vs statutory residency" is a key piece of this puzzle.
Practical Steps for a Smooth Transition
To ensure a smooth tax transition and successfully establish residency in your new tax-friendly state, it's wise to take a series of deliberate steps. Begin by obtaining a new driver's license and registering your vehicles in your new state. Update your mailing address with banks, investment firms, and government agencies (like Social Security and Medicare). Register to vote in your new state and actually participate in local elections.
Consider moving valuable or sentimental items to your new home. Close bank accounts in your old state and open new ones in your new state. Change your will and other legal documents to reflect your new state's laws and residency. If you own property in your old state, consider selling it, or at least clearly designating your new state property as your primary residence. The more definitive actions you take, the clearer your intent of domicile becomes to tax authorities. For a detailed guide, consider reading "How to Change Your State Residency for Taxes". Remember, consistency is key; avoid activities that could suggest you still maintain primary ties to your former high-tax state.
Finding Your Perfect Retirement Spot: A Holistic Approach
Choosing where to retire is a deeply personal decision, and while taxes are a huge consideration, they shouldn't be the only factor. It's about finding a place where you can thrive, where your money goes further, but also where you feel comfortable, engaged, and supported. The "perfect" state for one retiree might be completely unsuitable for another, highlighting the need for a holistic approach that balances financial prudence with personal preferences and lifestyle needs.
Weighing Tax Savings Against Quality of Life
It's easy to get fixated on the numbers, especially when comparing states with drastically different tax burdens. Saving thousands of dollars annually in income tax is certainly appealing. However, imagine moving to a state purely for tax benefits, only to find you dislike the climate, are far from family, or can't access the healthcare or social activities you desire. What's the point of having more money if you're not happy using it?
Consider factors like proximity to loved ones, access to quality healthcare (especially critical in retirement), climate and weather preferences, cultural attractions, recreational opportunities, and the general cost of living beyond just taxes. A state with no income tax might have higher costs for utilities, groceries, or transportation that could negate some of the tax savings. The goal is to find a place where the overall value proposition – taxes, cost of living, and quality of life – aligns with your retirement vision. For a deeper dive into this, you might find articles on the "Cost of Living vs Taxes by State" insightful.
The Importance of Professional Advice
Navigating state tax laws, especially when considering a move across state lines, can be incredibly complex. Each state has its own unique set of rules regarding income, property, and sales taxes, not to mention residency requirements and potential exemptions for retirees. What applies in one state might be entirely different in another, and staying up-to-date on changes (like some of the recent "State Income Tax Cuts & Changes for 2026") is a full-time job in itself.
This is where seeking professional advice becomes invaluable. A qualified financial advisor or a tax professional specializing in multi-state taxation can help you understand the full impact of a move on your finances. They can assist with domicile planning, help you compare the true tax burden in different states, and advise on strategies to minimize your overall tax liability, not just income tax. While a guide like this provides a great starting point, a personalized consultation ensures you make the best decision for your unique circumstances and avoid any costly surprises down the road. For many, working with a reputable firm can bring immense peace of mind.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change, and individual circumstances vary. Always consult with a qualified tax professional or financial advisor for advice tailored to your specific situation.