Georgia State Income Tax Calculator Guide
It's incredibly frustrating when you're trying to make sense of your finances, and state income tax calculations feel like a complex puzzle with missing pieces. You just want to know how much to expect – whether it's a refund that could help pay off bills or a payment you need to budget for – but Georgia's tax rules, especially with recent changes, can make that feel impossible. This guide will clarify how Georgia's state income tax works and show you how a state income tax calculator can provide the clear estimates you need to plan your year confidently.
Understanding Georgia's Income Tax System
Navigating the tax landscape in any state can be a challenge, and Georgia is no exception. While some states keep things relatively simple, Georgia has recently undergone a significant shift in its income tax structure that impacts nearly everyone who earns income within its borders. Understanding these core principles is your first step toward financial clarity.
Who Needs to Pay Georgia Income Tax?
The question of who pays Georgia income tax often comes down to your residency status and where your income is earned. It's not always as straightforward as it seems, especially in our increasingly mobile world.
First and foremost, if you are considered a legal resident of Georgia, you are generally required to pay Georgia income tax on all of your income, regardless of where that income was earned. So, if you live in Atlanta but work remotely for a company based in New York, your entire salary is subject to Georgia's income tax. This is a pretty standard rule across most states with an income tax, reflecting the benefit of living within the state and utilizing its services. For a deeper dive, you might find our guide on State Tax Residency Rules Explained helpful.
Then there are non-residents. If you live outside of Georgia but earn income from sources within the state, you'll likely need to file a Georgia non-resident tax return. Think of someone living in Chattanooga, Tennessee (a state with no income tax), but commuting daily to Ringgold, Georgia, for work. The income earned from that Georgia-based job is taxable by Georgia. This prevents people from avoiding state taxes simply by living just across a border while benefiting from the state's economic activity. This often involves filing taxes in multiple states, a topic we cover extensively in Working in One State, Living in Another: Tax Guide.
Finally, we have part-year residents. This category applies if you moved into or out of Georgia during the tax year. For example, if you lived in Florida (a state with no income tax) for the first half of the year and then moved to Savannah, Georgia, in July, you would be a part-year resident. You'd typically only pay Georgia income tax on the income you earned while you were a resident of Georgia, plus any Georgia-sourced income earned as a non-resident. This requires careful tracking of your income and dates, and usually, you'd file a part-year resident return, which can sometimes be more complex than a full-year resident or non-resident return.
Georgia's Flat Income Tax Rate for 2026
If you've been keeping up with Georgia's tax laws, you'll know there's been a significant shift from a progressive income tax system to a flat tax. This change began in 2024 and is being phased in gradually, with the rate decreasing each year until it reaches its final intended percentage. For the 2026 tax year, Georgia is continuing its transition to a flat income tax rate.
Prior to this change, Georgia utilized a progressive tax system, meaning different income levels were taxed at different rates. The more you earned, the higher your marginal tax rate could be, reaching up to 5.75% for higher earners. This system, common in many states, aims to distribute the tax burden based on an individual's ability to pay. However, the state of Georgia decided to simplify its tax code and potentially make it more attractive for businesses and individuals by moving to a flat tax.
For 2026, the Georgia state income tax rate is set to be 5.29%. This means that regardless of your taxable income (after deductions and exemptions), the same percentage will be applied. This is a notable simplification compared to the old bracket system where your income fell into different tiers, each with its own rate. So, while you might have previously looked at Georgia's Tax Brackets 2026 (if it still had them), now you're simply applying a single rate to your taxable income.
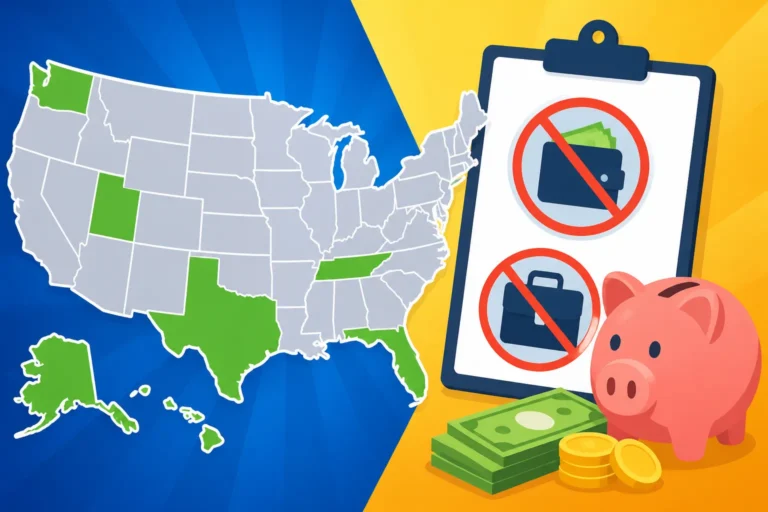
The shift to a flat tax has pros and cons. On one hand, it makes calculations much simpler and provides more predictability. On the other hand, it means that everyone, from the lowest to the highest earners, pays the same percentage of their taxable income, which can be a hot topic for debate. Many states are exploring similar changes, with some, like Ohio, also moving towards or implementing a flat tax. For a broader view, you can check out our article on States With a Flat Income Tax (2026).
To give you a quick overview, here's what the flat tax rate looks like for 2026:
| Tax Year | Georgia State Income Tax Rate |
|---|---|
| 2026 | 5.29% |
This flat rate is applied to your Georgia taxable income, which is your gross income minus any allowable deductions and exemptions. This brings us to why a calculator becomes so important – it helps you figure out that taxable income precisely.
Why a Georgia State Income Tax Calculator is Your Best Friend
Even with a flat tax rate, calculating your precise tax liability isn't as simple as multiplying your gross pay by 5.29%. There are still numerous factors like deductions, exemptions, and credits that play a significant role. This is where a Georgia state income tax calculator steps in, transforming a potentially confusing task into a manageable one.
Estimating Your Tax Liability and Refunds
Imagine approaching tax season without a clue whether you're going to owe a substantial amount or receive a nice refund. It's stressful, right? A good Georgia state income tax calculator can eliminate that uncertainty, giving you a clear projection long before the tax deadline.
Let's say you're a recent college graduate starting your first job in Athens. You're making a decent salary, but you're also trying to manage student loan payments and rent. Knowing if you'll get a few hundred dollars back or if you need to set aside money to pay the state can make a huge difference in your budget. A calculator allows you to input your income, your filing status (single, married filing jointly, etc.), and any potential deductions or credits you might be eligible for. In return, it spits out an estimated tax liability or refund.
This isn't just about avoiding a last-minute panic; it's about empowerment. When you have a solid estimate, you can make informed decisions throughout the year. Perhaps you realize you're on track for a large refund – great, maybe you can adjust your withholdings to get more money in each paycheck. Or, if it looks like you'll owe money, you can start setting aside funds monthly, rather than facing a large bill come April. Many online tools, including reputable ones like those offered by SmartAsset, provide straightforward interfaces to help you get these estimates quickly and accurately. This foresight is invaluable for budgeting and financial planning, helping you avoid that dreaded question, "Why Do I Owe State Taxes This Year?"
Planning for Withholding and Estimated Payments
Beyond just knowing your end-of-year situation, a tax calculator is a powerful tool for proactively managing your tax payments throughout the year. This is particularly crucial for controlling your cash flow and avoiding penalties.
For most employees, state income taxes are handled through payroll withholding, meaning your employer takes a portion of your paycheck and sends it to the state. However, the amount withheld is determined by the W-4 form you fill out. If you claimed too many allowances on your W-4, not enough tax might be withheld, leading to a surprise tax bill. If you claimed too few, you might be giving the state an interest-free loan throughout the year. Using a Georgia income tax calculator can help you fine-tune your W-4 entries. You can run different scenarios in the calculator – what if I claim one allowance? What if I claim zero? – and then adjust your W-4 with your employer accordingly. This way, you can aim for a tax outcome that suits your financial goals, whether that's a small refund or breaking even.
For those who are self-employed, independent contractors, or have significant income from investments or other sources not subject to withholding, estimated tax payments are a reality. Georgia, like the federal government, generally requires you to pay estimated taxes quarterly if you expect to owe a certain amount (typically $1,000 or more) in taxes for the year. Missing these payments or underpaying can result in penalties. A tax calculator becomes indispensable here. You can input your projected self-employment income, business expenses, and other earnings, and the calculator will help you determine how much you should be sending in each quarter to the Georgia Department of Revenue. This proactive approach ensures compliance and helps you avoid those pesky underpayment penalties. Consider exploring our guide on State Tax Payment Plans & Penalties for more details on this.
How to Use a Georgia State Income Tax Calculator Effectively
Using an online calculator might seem simple, and often it is, but getting the most accurate estimate requires understanding what information you need to input and how to interpret the results. It's not just punching numbers; it's about smart data entry.
Key Information You'll Need
To get a reliable estimate from any Georgia state income tax calculator, you'll need to gather a few pieces of crucial information. Think of it as preparing your ingredients before you start cooking – the better your inputs, the better your output.
First, and most obviously, you'll need your income information. This includes your gross wages from your W-2 forms, any self-employment income from 1099-NEC forms, rental income, interest, dividends, and any other taxable income sources. Don't forget capital gains if you sold investments, or retirement income if you're pulling from a 401(k) or IRA. The calculator needs a complete picture of your earnings for the year. Many calculators, like the one SmartAsset offers, are designed to walk you through these different income types to ensure you don't miss anything.
Next, your filing status is paramount. Are you single, married filing jointly, married filing separately, head of household, or a qualifying widow(er)? Your filing status significantly impacts your standard deduction amount and other thresholds, directly affecting your taxable income. Be honest and accurate with this; it's one of the biggest determinants of your final tax bill.
Finally, you'll need to consider deductions and credits. This is where many people can save significant money. Georgia has its own state-specific deductions and credits. You'll need to know if you plan to take the Georgia standard deduction or if you're able to itemize deductions. While Georgia's income tax is a flat rate, your taxable income is still reduced by these deductions. For example, some states offer deductions for contributions to 529 plans, while others have state-specific EITCs or child tax credits. Knowing about these can help you How to Lower Your State Income Tax. Even if you don't have all the exact numbers yet, estimating these can give you a much more refined projection.
Interpreting Your Results
Once you've diligently entered all your financial data into the Georgia state income tax calculator, you'll get a result. But what do those numbers truly mean for your financial future? It's more than just a single dollar amount; it's about understanding the implications.
The most prominent result you'll see is usually your estimated tax liability or your projected refund. If it's a liability, that's the amount you might owe the state. If it's a refund, that's the money coming back to you. However, remember that this is an estimate. It's based on the information you've provided, and real-life circumstances can always shift. The real value comes from using this estimate as a guide, not a guarantee. For instance, if you're projecting a large refund, it might be worth reviewing your W-4 with your employer to see if you can adjust your withholdings and have more money in your paychecks throughout the year. Conversely, if you're staring down a big tax bill, it's a prompt to start saving up or adjusting your budget.
Another important concept, even with a flat tax, is the difference between your marginal tax rate and your effective tax rate. While Georgia's statutory income tax rate for 2026 is a flat 5.29%, your effective tax rate (the percentage of your total income you actually pay in state taxes) will almost certainly be lower. This is because deductions and exemptions reduce your taxable income before the 5.29% rate is applied. So, if a calculator also shows your effective rate, it's a great metric to compare your overall tax burden, especially if you're looking at moving to other states. For a detailed explanation, check out our guide on Marginal vs Effective Tax Rate Calculator Guide.
Regularly re-evaluating your tax situation, especially after major life events like a new job, marriage, or having a child, is a smart move. A Georgia state income tax calculator allows you to plug in updated figures throughout the year, ensuring your estimates remain as accurate as possible. This way, you're always ahead of the game, rather than being surprised when the tax deadline, typically April 15th, rolls around.
Beyond the Calculator: Other Georgia Tax Considerations
While a calculator is an indispensable tool for estimating your income tax, it's part of a larger financial picture. Understanding Georgia's unique deductions and credits, as well as critical deadlines, can further optimize your tax planning.
Common Deductions and Credits in Georgia
Even with Georgia's flat tax rate, understanding available deductions and credits is key to reducing your overall tax burden. These aren't just minor adjustments; they can significantly lower your taxable income or even reduce your tax bill dollar-for-dollar.
First off, let's talk about the Georgia standard deduction. Like the federal tax system, Georgia offers a standard deduction that you can claim instead of itemizing. For the 2026 tax year, the Georgia standard deduction amounts are typically lower than the federal amounts, so it's critical to know the state-specific figures. For example, for a single filer, the Georgia standard deduction is often around $5,000, while for married couples filing jointly, it's double that. Choosing between the standard deduction and itemizing depends on whether your itemized deductions (like mortgage interest, state and local taxes up to the SALT cap, or charitable contributions) exceed the standard amount. Our guide on State Standard Deduction vs Itemized (2026) provides a comprehensive look at this.
Beyond the standard deduction, Georgia also offers various credits that can further reduce your tax liability. Some states offer broad credits like a state-level Earned Income Tax Credit (EITC) or Child Tax Credits. While Georgia has historically provided some credits, these can change annually. For instance, Georgia has offered credits for dependent care expenses, which help families offset the costs of childcare. There are also specific credits for things like qualified education expenses, adoption expenses, or even certain business investments designed to stimulate the state economy. It’s always worth checking the Georgia Department of Revenue website for the most current list of available credits, as they can represent a direct reduction of your tax bill, rather than just reducing your taxable income. For more on this, you might explore articles like State Earned Income Tax Credits (EITC) Guide or State Child Tax Credits 2026. These deductions and credits are your opportunity to pay only what you legally owe and nothing more.
Staying Compliant with Georgia Tax Deadlines
Knowing what you owe or are owed is one thing, but knowing when to take action is just as important. Missing deadlines can lead to penalties and interest, adding unnecessary stress and cost to your tax situation.
The primary deadline for filing your Georgia state income tax return and paying any taxes owed is typically April 15th of each year, mirroring the federal deadline. If April 15th falls on a weekend or a holiday, the deadline shifts to the next business day. This applies to most individual filers. However, it's crucial to confirm the exact date each year, as slight variations can occur, especially if there are state-specific holidays or emergencies. You can always refer to our detailed post on State Tax Deadlines 2026 (All States) for the most up-to-date information across the nation.
If you find yourself unable to file by the April deadline, don't panic. Georgia, like the IRS, generally offers an automatic extension to file your return. If you file a federal extension (Form 4868), Georgia usually grants you an automatic extension to file your state return as well, typically for an additional six months. However, it's absolutely critical to remember that an extension to file is not an extension to pay. If you estimate you'll owe state taxes, you must still pay that estimated amount by the original April deadline to avoid interest and penalties. Failing to pay on time, even with an extension to file, can still result in fines. Our article on State Tax Extensions: How to File can walk you through the specifics.
Beyond the main annual deadline, remember the quarterly estimated tax payment deadlines if you're self-employed or have other non-wage income. These generally fall on April 15th, June 15th, September 15th, and January 15th of the following year. Staying on top of these deadlines ensures compliance and keeps your financial planning smooth and stress-free.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional tax advice. Tax laws, rates, and regulations are complex and subject to change. Always consult with a qualified tax professional or the Georgia Department of Revenue for advice tailored to your specific situation.