States That Require Same Deduction as Federal
Figuring out your state tax deductions can feel like trying to solve a Rubik's Cube blindfolded, especially when you're already grappling with federal tax rules. One of the biggest questions that pops up is whether your state just goes along with whatever the IRS says, or if they have their own completely unique set of rules. It’s a common point of confusion, and frankly, a source of major headaches for many taxpayers trying to make sure they're not leaving money on the table or, even worse, making a mistake that could lead to penalties. This guide is here to shed some light on which states require you to use the same deductions as your federal return, helping you navigate this often-tricky landscape with a bit more confidence.
Decoding Federal Standard Deductions
Before we dive into the state-specific quirks, it's essential to have a solid grasp of what we're talking about at the federal level. The federal tax system offers taxpayers a choice: either take a standard deduction or itemize their deductions. This choice significantly impacts your taxable income and, ultimately, how much you owe the IRS.
What is the Federal Standard Deduction?
The federal standard deduction is a set dollar amount that taxpayers can subtract from their adjusted gross income (AGI) if they choose not to itemize. It's essentially a no-questions-asked reduction that simplifies tax filing for millions of Americans. The amount you qualify for depends on your filing status (single, married filing jointly, head of household, etc.) and whether you or your spouse are age 65 or older, or blind. For instance, the standard deduction for a single filer in 2026 might be around $14,600, give or take, but these figures are adjusted annually for inflation.
Think of it this way: the government provides a baseline amount of income that it agrees not to tax, no questions asked. This is incredibly helpful for most people because gathering all the receipts and documentation for itemized deductions can be a real chore. For many, the standard deduction is higher than what they'd get by itemizing, making it the more financially beneficial and simpler choice. It’s designed to provide a uniform tax break, recognizing that everyone incurs certain basic living expenses that shouldn't be fully taxed. Knowing this amount is your first step in understanding your total tax picture, as it sets the foundation for how many states approach their own tax calculations.
How Federal Itemized Deductions Play a Role
While the standard deduction is simple and widely used, itemized deductions are where things get a bit more personal and complex. Itemizing means you're listing out specific expenses that you're allowed to subtract from your AGI, rather than taking the fixed standard amount. Common itemized deductions include things like mortgage interest, state and local taxes (up to the current SALT cap, which has been quite a hot topic, currently at $10,000 for many, though there's talk of increasing it to $40,000 as discussed in articles about the What Is the SALT Deduction Cap for 2026?), medical expenses exceeding a certain percentage of your AGI, and charitable contributions.
The decision to itemize or take the standard deduction federally is a crucial one, as it forms the basis for how many states will then expect you to handle your state income tax return. If you itemize federally, some states will require you to itemize on your state return too, even if their state-specific itemized deductions are different. Other states might allow you to switch it up, taking the federal standard deduction but then choosing to itemize for state purposes, or vice-versa, depending on what works best for your specific situation. This interplay is exactly why understanding both options at the federal level is non-negotiable before tackling your state taxes. For a deeper dive into making this choice, you might find our guide on State Standard Deduction vs Itemized (2026) really useful.
States That Mirror Federal Standard Deductions
Now, let's get to the good news for those who appreciate simplicity: many states actually align their deduction rules pretty closely with the federal government. This means if you take the federal standard deduction, you'll likely be taking a similar (or identical) standard deduction on your state return. It can be a huge relief, cutting down on the amount of extra work you need to do.
The Convenience of Conformity
States that conform to federal standard deductions often do so to streamline the tax filing process for their residents and for their own tax administration. It reduces complexity for both taxpayers and the state's revenue department, as there isn't a need to maintain an entirely separate set of rules and forms just for deductions. For you, the taxpayer, this means less head-scratching and a smoother experience when you're preparing your returns. If you're using tax software like TurboTax, this conformity makes it incredibly straightforward, as much of the federal data can simply flow through to your state return.
Many states, especially those with relatively simpler tax codes or flat income tax rates, find this approach beneficial. For instance, states like Indiana often align closely with federal deductions. If you claim the standard deduction on your federal return, you'll typically claim the same amount on your Indiana state return. This eliminates the need for Hoosiers to calculate a separate set of state-specific itemized deductions, unless they have unique circumstances. The benefit here is tangible: fewer forms, less potential for error, and a more intuitive filing process. This is particularly appreciated by those who already find tax season overwhelming. For detailed information on specific state amounts, checking out our State-by-State Standard Deductions 2026 guide is a smart move.
Specific Examples and Nuances
While many states aim for federal conformity, it’s rarely a perfect, one-to-one match without any small nuances. For example, some states might start with the federal standard deduction amount but then allow for certain additions or subtractions that are unique to their state. They might offer additional deductions for things like military retirement income, contributions to state-sponsored 529 plans, or certain health savings account contributions. So, while the base deduction might be federal, there could be state-specific "above-the-line" deductions that reduce your state taxable income further.
Take Iowa, for instance. It’s generally a federal conformity state, meaning much of your federal taxable income and deductions carry over. However, Iowa allows certain adjustments, such as deductions for unreimbursed casualty losses or contributions to the Iowa Educational Savings Plan Trust (the state's 529 plan). These are additions that you wouldn't necessarily see on your federal return in the same way, demonstrating how states can conform largely but still retain some unique characteristics. It’s always crucial to double-check your state's specific tax department guidelines or consult with a qualified tax professional to ensure you're capturing all available deductions. This hybrid approach allows states to offer some relief or incentives aligned with their own policy goals, even while largely simplifying the process by mirroring federal rules.
States with Their Own Deduction Rules
On the flip side of the coin, you have states that march to the beat of their own drum when it comes to deductions. These states have either completely different standard deduction amounts, different sets of itemized deductions, or a combination of both. This is where things can get a bit more complicated, especially if you’re used to federal conformity.
Why States Deviate
There are several compelling reasons why states choose to deviate from federal deduction rules. Often, it comes down to revenue needs and specific policy goals. States have their own budgets to balance and their own priorities, which might include encouraging certain behaviors (like charitable giving or energy efficiency) or providing relief to particular segments of their population (like low-income families or seniors). For example, a state might offer a generous earned income tax credit that goes beyond the federal EITC, or they might have unique property tax credits that aren't mirrored federally.
Another reason for divergence can be historical. Many state tax codes predate significant federal tax reforms, and lawmakers may simply choose not to overhaul their entire system to align perfectly with federal changes. This can lead to a patchwork of deductions that are distinctly state-specific. Furthermore, some states might want to keep their tax base broader to generate more revenue, which means offering fewer or smaller deductions than the federal government. This is often the case in states with higher tax burdens where every deduction matters significantly. Understanding this helps explain why you might encounter different rules depending on where you reside or earn income.
Examples of Divergence
Let's look at some examples of states that diverge significantly. California, for instance, has its own set of rules entirely. While you can take a standard deduction on your California return, the amount is often quite different from the federal amount. For 2026, the California Standard Deduction 2026 for single filers is typically much lower than the federal standard deduction, making itemizing a more attractive option for many Californians, even if they took the standard deduction federally. Furthermore, California has unique deductions and credits that aren't found at the federal level, such as the renter's credit for eligible individuals.
New York is another prime example. The New York Standard Deduction 2026 also differs from the federal amount, and like California, New York residents often find that their state tax situation requires a separate calculation of deductions. New York also has its own system of itemized deductions. This means you could potentially take the standard deduction on your federal return but still find it beneficial to itemize on your New York state return, or vice versa, if allowed. The key takeaway here is that you absolutely cannot assume that what applies to your federal return will automatically apply to states like California or New York. These states require careful attention to their specific guidelines, which sometimes means extra calculations or different forms compared to more conforming states.
Navigating Hybrid Deduction Systems
It's not always a clear-cut choice between full federal conformity and complete state divergence. Many states operate on a hybrid model, offering some aspects of federal alignment while maintaining unique state-specific deductions or rules. This can make tax planning even more intricate, requiring taxpayers to understand both sets of guidelines.
The Best of Both Worlds (and Challenges)
A hybrid system attempts to strike a balance: leverage the simplicity of federal calculations where possible, but also allow the state to address its own fiscal and social priorities through unique deductions. For example, a state might adopt federal adjusted gross income (AGI) as a starting point, which incorporates many federal deductions, but then allow taxpayers to claim additional state-specific deductions or credits. This can be beneficial because it reduces some of the initial calculation burden, but it also means you can't just copy and paste everything from your federal return.
Consider a state like North Carolina. For 2026, North Carolina has its own standard deduction amounts that differ from the federal figures. However, it also allows for certain deductions that mirror federal deductions, like deductions for IRA contributions, or has unique subtractions for things such as government pensions or contributions to the state's 529 plan. So, while you're not strictly tied to your federal standard deduction amount, you still need to be aware of what state-specific deductions are available to you. This kind of system requires taxpayers to be diligent in reviewing their state's tax instructions to ensure they're maximizing all potential tax breaks, even when using general tax software.
When to Itemize Federally vs. State-Level
One of the most common dilemmas in hybrid systems is deciding whether to itemize at the federal level and then at the state level. In states that don't require you to use the same deduction method as your federal return, you might find it advantageous to take the federal standard deduction but itemize on your state return, or vice-versa. This flexibility is a powerful tool for optimizing your tax liability.
For example, imagine you have high medical expenses, but they don't quite push you over the federal AGI threshold to make itemizing federally beneficial. However, your state might have a lower AGI threshold or a more generous deduction for medical expenses, making it worthwhile to itemize on your state return even if you took the federal standard deduction. The same applies to local property taxes; if you live in an area with high property taxes, but your total itemized deductions (including the current federal SALT cap) don't exceed your federal standard deduction, you might still get a significant tax break by itemizing on your state return if that state allows it and doesn't have a similar SALT cap limitation. Tools like SmartAsset can sometimes help compare these scenarios, though official state tax department calculators are always the definitive source. Ultimately, understanding your Marginal vs Effective Tax Rate Calculator Guide for both federal and state taxes can help you make these nuanced decisions. This is where a careful comparison of the numbers really pays off, ensuring you don't miss out on savings just because you assumed one deduction method automatically applied to both.
Practical Tips for Taxpayers Across States
Navigating the various state income tax deduction rules can feel like a minefield. Whether your state largely conforms to federal guidelines, has its own distinct rules, or operates on a hybrid model, there are some universal truths and practical steps you can take to make the process smoother and ensure you're compliant.
The Importance of Up-to-Date Information
Tax laws, both federal and state, are constantly changing. What was true last year might not be true this year, and what applies to one state certainly doesn't apply to all. This is why relying on up-to-date information is absolutely critical. Always check the official website of your state's department of revenue or taxation for the most current guidelines, forms, and deduction amounts for the specific tax year you're filing. These sites are the definitive source and will outline any changes to standard deduction amounts, new credits, or modifications to itemized deduction rules.
Tax software like TurboTax is designed to incorporate these annual changes, but it's still smart to have a general understanding yourself. For instance, some states might announce State Income Tax Cuts & Changes for 2026 that directly impact your deductions. Don't rely on old blog posts, anecdotal advice from friends, or even last year's tax forms without verifying the information. A quick search for " [State Name] tax deductions 2026" on your state's official government website can save you a lot of grief and potential penalties down the line. It's about empowering yourself with knowledge directly from the source.
Planning for Multi-State Scenarios
For individuals who live in one state and work in another, or those who have moved mid-year, the deduction landscape becomes even more complex. You might be considered a part-year resident in two states or even a nonresident in a state where you earned income. In these multi-state scenarios, you'll typically need to file returns in each state where you have a filing obligation, and each state will have its own rules regarding how to allocate income and deductions. This can quickly lead to situations where you're asking, " Do I Pay Taxes in Two States If I Work Remotely?" or " How Do I Avoid Paying Taxes in Two States?"
The key here is understanding how each state treats income from different sources and how they handle deductions for part-year or nonresident filers. Many states will require you to proration your deductions based on the percentage of your income earned within that state. For example, if you earned 60% of your income in State A and 40% in State B, and both states allow the same deduction, you might only be able to claim 60% of that deduction on State A's return and 40% on State B's. However, some states, particularly those with a "convenience of the employer" rule, can add another layer of complexity for remote workers. This means meticulous record-keeping of your income, expenses, and days spent in each state is non-negotiable. Consulting with a tax professional experienced in multi-state taxation is often the wisest course of action to ensure compliance and maximize your tax benefits in these situations.
A Comparative Look at Deduction Methods
To give you a clearer picture, here’s a simplified table comparing how different types of states might handle deductions:
| State Type | Federal Standard Deduction | State Standard Deduction | Itemized Deductions | Common Examples (Illustrative) |
|---|---|---|---|---|
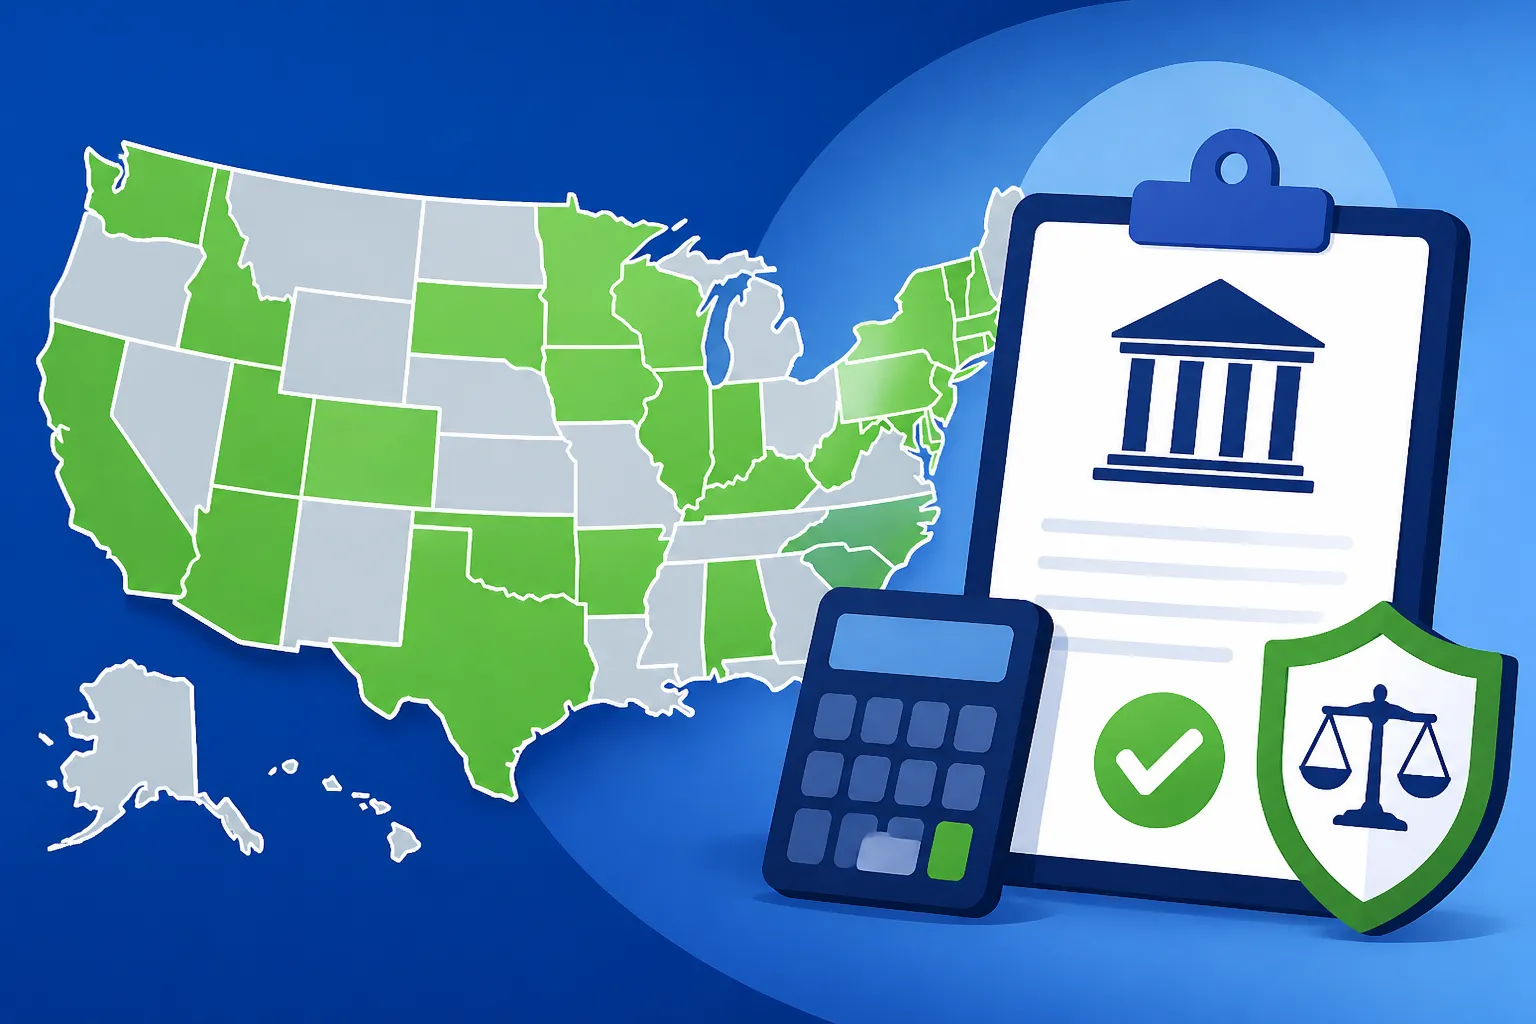
| Full Conformity | Generally required | Matches federal | Mirrors federal | Indiana, West Virginia |
| Partial Conformity/Hybrid | May or may not match | State-specific amount | Federal basis + state additions | Iowa, North Carolina |
| Full Divergence | Separate consideration | State-specific amount | State-specific rules | California, New York |
| No Income Tax States | N/A | N/A | N/A | Florida, Texas, Washington |
Note: This table provides general illustrative examples. Specific rules and amounts vary greatly by state and year. Always consult official state tax resources.
For those living in one of the States With No Income Tax (2026 Full List), this entire discussion about income tax deductions might seem irrelevant. And largely, it is! However, even these states might have other taxes like property taxes or sales taxes that can impact your overall tax burden, which SmartAsset can help you research. But when it comes to income tax deductions, you're off the hook.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change. Always consult with a qualified tax professional or refer to the official publications from your state's Department of Revenue or Taxation for personalized advice regarding your specific tax situation.