States With No 529 Deduction
Saving for college is a noble goal, but let's be honest, it can feel like you're constantly swimming upstream against rising tuition costs and complex financial rules. Many families look to 529 college savings plans as a beacon of hope, not just for their long-term growth potential, but also for the sweet state income tax deductions they often provide. But what happens if you live in a state that doesn't offer this particular perk? It's a common frustration, and one that leaves many wondering if a 529 plan is even worth it. This comprehensive guide will shed light on the states that offer no specific 529 deduction, explore why that's the case, and help you strategize your college savings effectively, no matter where you call home.
Understanding 529 Plans Beyond Federal Benefits
When you start researching 529 plans, the first thing you usually hear about are the federal tax benefits. And those are certainly compelling! Tax-deferred growth and tax-free withdrawals for qualified education expenses are a powerful combination. But states often sweeten the pot with their own incentives, and understanding this two-tiered system is crucial for optimizing your college savings.
The Basics of 529 Plans
A 529 plan, officially known as a "qualified tuition program," is an investment vehicle designed to encourage saving for future education costs. These plans are sponsored by states, state agencies, or educational institutions, and they typically come in two flavors: college savings plans and prepaid tuition plans. College savings plans, which are far more common, are investment accounts similar to a 401(k) or IRA, where your contributions grow and are withdrawn tax-free for eligible expenses. Prepaid tuition plans, on the other hand, allow you to purchase future tuition credits at today's prices, primarily for in-state public colleges. For the purpose of state tax deductions, we're almost always talking about the college savings plans.
The big draw with 529 plans is the tax treatment. Federally, your contributions aren't deductible, but the earnings grow tax-free, and distributions are also tax-free as long as they're used for qualified higher education expenses. This means no capital gains tax on your investment growth, which can be substantial over many years. But here's where things get interesting: many states offer a state income tax deduction or credit for contributions made to a 529 plan. This state-level incentive is a huge motivator for many families, essentially giving them an immediate discount on their contributions. It's like getting a thank-you note from your state for being a responsible saver!
The Appeal of State Tax Deductions
The lure of a state income tax deduction for 529 contributions is quite strong. Imagine you contribute $5,000 to a 529 plan in a state that offers a 5% deduction. That immediately shaves $250 off your state taxable income, or more if it's a credit. It's essentially a guaranteed return on your investment right from the start, a powerful boost that traditional savings accounts or even other investment vehicles can't typically offer. This immediate benefit can make a significant difference, especially for families trying to squeeze every possible dollar out of their budget to put toward college.
Many states have these incentives, and they can vary wildly. Some states offer deductions only if you contribute to your home state's 529 plan, while others offer "tax parity," meaning you get the deduction regardless of which state's plan you choose. This is where researching your specific state's rules is absolutely critical, as detailed in our guide on 529 Plan Tax Deductions by State. Understanding How State Tax Brackets Work: Marginal vs Effective can further clarify just how much a state deduction truly benefits your overall tax liability. It's not just about the percentage; it's about how that percentage interacts with your total income and other deductions.
The List: States That Don't Offer a 529 Deduction or Credit
Now, let's get down to brass tacks. While many states offer some form of tax benefit for 529 contributions, a significant number do not. This can be a real disappointment for residents of these states, as they miss out on that immediate, upfront tax saving.
States with No Income Tax
First, let's address the most obvious category: states that don't have a state income tax to begin with. If there's no state income tax, there's naturally no income tax deduction to offer for 529 contributions. It's a simple, undeniable fact. These states typically rely on other forms of taxation, like sales tax or property tax, to fund state services.
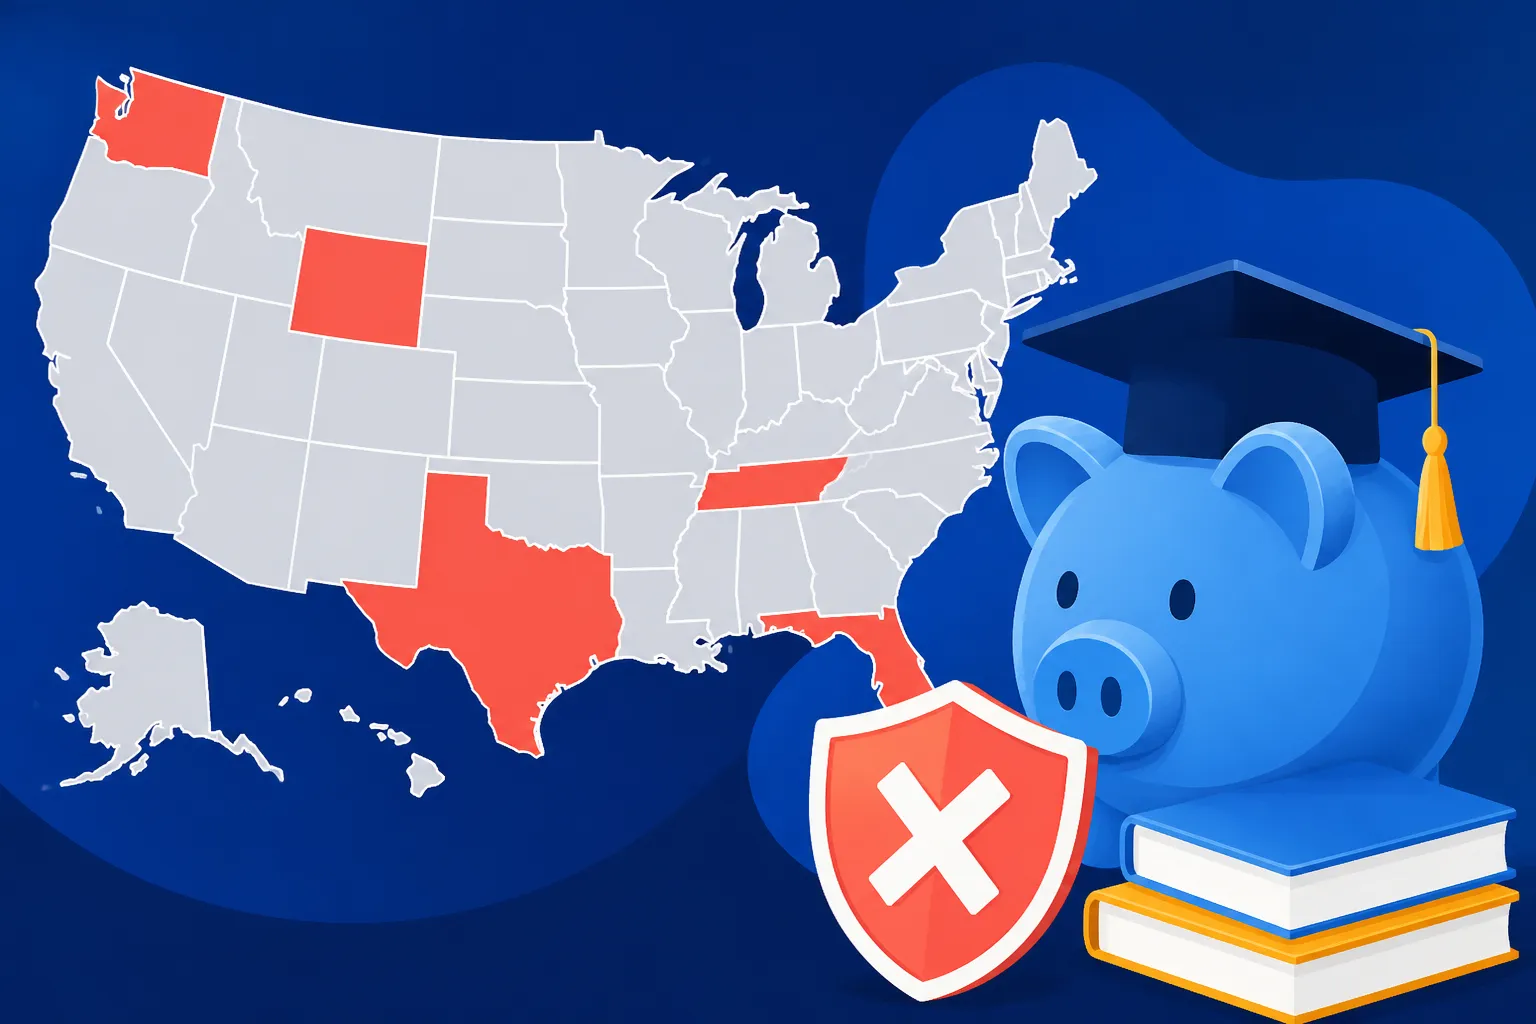
As of early 2024, the following nine states have no state income tax:
- Alaska
- Florida
- Nevada
- New Hampshire (though it does tax interest and dividends)
- South Dakota
- Tennessee (though it previously taxed interest and dividends, this has been phased out)
- Texas
- Washington (though it has a capital gains tax)
- Wyoming
For residents of these states, the decision to contribute to a 529 plan still makes perfect sense due to the federal tax benefits—tax-free growth and withdrawals. However, you won't get that added state income tax break. This is a crucial point many people overlook when considering their options, thinking a 529 is a wash if their state doesn't offer a deduction. It's not. It just means your tax benefits are solely at the federal level. For more details on these states, you can check out our article States With No Income Tax (2026 Full List).
Income Tax States Without a Specific 529 Deduction
Beyond the no-income-tax states, there are several states that do have a state income tax but still don't offer a specific deduction or credit for 529 plan contributions. This can feel a bit like a double whammy for residents, as they pay state income tax but don't get the 529 incentive that residents in many other income-taxing states enjoy.
Based on current tax laws, here are some of the income tax states that do not offer a state income tax deduction or credit for 529 contributions:
- California
- Delaware
- Hawaii
- Kentucky
- Massachusetts
- Minnesota
- New Jersey
- North Carolina
- Vermont
It's important to keep in mind that state tax laws can change, so it's always a good idea to confirm the most up-to-date information with your state's revenue department or a trusted tax professional. For example, North Carolina is a state that has seen State Income Tax Cuts & Changes for 2026, but these haven't typically included a 529 deduction. Even in states like New Jersey, which does offer a retirement income exclusion, a 529 deduction isn't currently on the table.
What "No Deduction" Really Means for You
So, you live in one of these states. Does that mean a 529 plan is useless? Absolutely not! What "no deduction" really means is that you won't get an immediate reduction in your state taxable income for the money you contribute. Your actual tax bill won't be lowered simply by making a contribution to a 529 plan that year.
However, the powerful federal tax benefits still apply. Your investments inside the 529 plan still grow tax-deferred, and all qualified withdrawals for tuition, fees, books, supplies, and even certain room and board expenses remain entirely tax-free at the federal level. This tax-free growth over decades can add up to a significant amount, often overshadowing the lack of a state deduction, especially for those planning far in advance.
Let's consider an example: Sarah lives in California, a state with no 529 deduction. She contributes $500 a month to her child's 529 plan for 18 years. While she won't get a California income tax break on her annual $6,000 contributions, the earnings on her investments will compound year after year without being taxed. If her account grows to, say, $150,000 from her $108,000 in contributions, that $42,000 in earnings would have been subject to capital gains tax in a regular brokerage account. With the 529, it's all tax-free when used for college. That's a huge win!
Why Some States Opt Out of 529 Tax Breaks
It might seem counterintuitive for a state to forego offering a tax incentive for something as universally beneficial as college savings. After all, an educated populace often leads to a stronger economy. However, states have complex budgets and myriad priorities. The decision not to offer a 529 deduction is usually a calculated one, based on revenue, policy goals, and sometimes even the existing tax structure.
Revenue Considerations for States
The primary reason many states don't offer a 529 deduction comes down to revenue. Every tax deduction or credit a state offers means less money flowing into state coffers. State legislatures must constantly balance various needs: funding schools, maintaining infrastructure, providing healthcare, public safety, and so much more. A tax deduction for 529 contributions, while beneficial to families, can represent a substantial revenue loss, especially in larger states with many residents saving for college.
Consider a state like California. With its massive population and corresponding tax base, even a modest 529 deduction could translate into billions of dollars in lost tax revenue each year. The state might decide that those funds are better allocated to direct educational spending, infrastructure projects, or other social programs that benefit a broader segment of the population. It's a matter of prioritization and economic trade-offs. While promoting college savings is a worthy goal, it might not be the top priority when faced with other pressing budgetary concerns. This is part of the ongoing discussion around State Income Tax Cuts & Changes for 2026 where every proposed change has a fiscal impact.
Alternative Incentives or Priorities
Some states might also choose not to offer a 529 deduction because they prefer to offer other forms of educational or savings incentives, or they might simply have different philosophical approaches to taxation and public funding. For instance, a state might invest heavily in its public university system, offering lower tuition rates to in-state residents, effectively making college more affordable without needing to provide a 529 tax break.
Other states might focus on different types of tax credits that aim to help lower-income families or address other specific needs. For example, some states have generous State Earned Income Tax Credits (EITC) Guide or State Child Tax Credits 2026 that they prioritize. These credits might be seen as more broadly impactful than a 529 deduction, which primarily benefits those who have disposable income to save. The policy goal isn't to discourage college savings, but rather to use tax incentives to achieve other desired outcomes or support different segments of the population. It's a complex puzzle of public finance and policy objectives.
The Impact of No State Deduction on Your College Savings Strategy
If you're in a state without a 529 deduction, it definitely shapes your strategy, but it certainly doesn't mean giving up on 529 plans. It just means you need to be a bit savvier in how you approach your college savings.
Evaluating the True Value of a 529
Without a state tax deduction, the primary value of a 529 plan reverts to its federal tax advantages: tax-deferred growth and tax-free withdrawals for qualified expenses. For long-term savers, this is still incredibly powerful. Over 10, 15, or 20 years, the compounding of tax-free returns can easily eclipse the value of an annual state tax deduction, especially if that deduction was relatively small.
Think of it this way: a 5% state deduction on $10,000 contributed annually saves you $500 in state taxes. That's great! But if your investments grow by 7% per year, and those earnings compound tax-free for a decade, the avoided capital gains taxes could be much, much higher. It’s all about the long game. You should still absolutely use a 529 plan, even if your state doesn't give you that upfront tax break. The long-term growth potential and tax-free distributions are significant. To understand the bigger picture of how this fits into your overall financial wellness, you might want to consider the broader Cost of Living vs Taxes by State as well.
Considering Out-of-State 529 Plans
One silver lining for residents in states without a home-state deduction is that you're not penalized for shopping around. Since there's no incentive to stick with your own state's plan, you're free to choose any state's 529 plan that offers what you're looking for. This is where SmartAsset and similar resources come in handy, allowing you to compare different plans side-by-side.
When looking at out-of-state plans, consider factors such as:
- Investment Options: Do they offer a variety of low-cost, diversified investment portfolios? Look for options with low expense ratios.
- Fees: Are the administrative and underlying fund fees reasonable? Fees can eat into your returns over time.
- Performance: While past performance doesn't guarantee future results, it can give you an idea of how well the plan is managed.
- Ease of Use: Is the online interface user-friendly? Can you set up automatic contributions easily?
For example, many financial experts often recommend plans from states like Utah (my529), New York (New York's 529 College Savings Program Direct Plan), or Ohio (Ohio's CollegeAdvantage) due to their low fees, diverse investment options, and strong management, even for out-of-state residents. The key is to find a plan that aligns with your risk tolerance and investment goals, rather than feeling constrained by state borders. Our article State 529 Deduction Limits 2026 (All States) offers a detailed look at what other states offer, which can give you a benchmark for comparison.
Maximizing Your College Savings in Non-Deduction States
Even without a state income tax deduction, you have plenty of ways to maximize your college savings. It's about being strategic and leveraging all available tools.
Exploring Other Tax-Advantaged Accounts
While a 529 plan is often the go-to for college savings, it's not the only tax-advantaged game in town. Depending on your financial situation and goals, other accounts might complement or even substitute for some of your 529 savings, especially if you're concerned about state tax inefficiency.
- Roth IRA: While primarily a retirement account, a Roth IRA offers incredible flexibility. Contributions are made with after-tax dollars, grow tax-free, and qualified withdrawals in retirement are also tax-free. Here's the kicker for college savings: you can withdraw contributions (not earnings) from a Roth IRA at any time, for any reason, without tax or penalty. Plus, you can withdraw earnings penalty-free (though they might be taxable) if used for qualified higher education expenses, provided the account has been open for five years. This makes it a powerful dual-purpose vehicle – retirement first, college second.
- Custodial Accounts (UGMA/UTMA): These accounts are established for a minor and managed by a custodian. Any assets in the account belong to the child, and they become accessible at the age of majority (usually 18 or 21, depending on the state). While they don't offer the same tax-free growth and withdrawal benefits as a 529, they do benefit from the "kiddie tax" rules, meaning some earnings are taxed at the child's lower tax rate. The downside is that the child has full control of the funds once they reach the age of majority, which might not align with your college funding intentions.
- Education Savings Accounts (ESAs): Formerly known as Education IRAs, ESAs allow you to contribute up to $2,000 per year per child. Earnings grow tax-free, and withdrawals are tax-free if used for qualified education expenses. This is similar to a 529 but with lower contribution limits and income restrictions for contributors.
Each of these has its own nuances, contribution limits, and impact on financial aid eligibility, so it's worth weighing the pros and cons carefully. The core message is that Can You Deduct 529 Contributions on State Taxes? might be a "no" for you, but there are other avenues for tax-advantaged savings.
Leveraging Federal Tax Benefits
Even without state tax benefits, the federal tax benefits of a 529 plan are substantial and should not be overlooked. The tax-free growth and tax-free withdrawals for qualified education expenses are incredibly valuable over the long term. This means that if your investment strategy within the 529 plan is sound, you could save thousands, or even tens of thousands, in federal capital gains taxes.
Beyond the 529 itself, remember there are other federal education tax credits and deductions available, such as:
- American Opportunity Tax Credit (AOTC): A partially refundable credit up to $2,500 for qualified education expenses for the first four years of higher education.
- Lifetime Learning Credit (LLC): A nonrefundable credit up to $2,000 for qualified education expenses for undergraduate, graduate, and professional degree courses.
- Student Loan Interest Deduction: You can deduct the amount of interest you paid during the year on a qualified student loan, up to $2,500.
These federal benefits can significantly offset the costs of college, and they operate independently of your state's 529 deductions. It's a reminder that State Income Tax vs Federal Income Tax often involves very different rules and incentives, and it's essential to understand both.
Practical Saving Strategies
Beyond tax-advantaged accounts, good old-fashioned disciplined saving remains paramount.
- Automate Your Savings: Set up automatic monthly transfers from your checking account to your chosen 529 plan or other savings vehicle. "Out of sight, out of mind" truly works wonders for consistent saving. Even a small amount consistently saved can grow significantly over time.
- Windfalls and Bonuses: Direct a portion of any bonuses, tax refunds, or unexpected windfalls directly into your college savings. This can give your account a big boost without impacting your regular budget.
- Budgeting and Prioritization: Re-evaluate your household budget to identify areas where you might be able to reallocate funds to college savings. This isn't about deprivation, but about intentional spending aligned with your long-term goals. If you're looking for ways to reduce your overall tax burden and free up more funds for saving, our guide on How to Lower Your State Income Tax might offer some valuable insights.
Here's a quick comparison of states and their 529 deduction status:
| State | State Income Tax? | 529 Plan Deduction/Credit? | Notes |
|---|---|---|---|
| Alabama | Yes | Yes | Deduction for residents |
| Alaska | No | N/A | No state income tax |
| Arizona | Yes | Yes | Credit for residents |
| Arkansas | Yes | Yes | Deduction for residents |
| California | Yes | No | No state tax benefit for 529 contributions |
| Colorado | Yes | Yes | Deduction for residents |
| Delaware | Yes | No | No state tax benefit for 529 contributions |
| Florida | No | N/A | No state income tax |
| Hawaii | Yes | No | No state tax benefit for 529 contributions |
| Kentucky | Yes | No | No state tax benefit for 529 contributions |
| Massachusetts | Yes | No | No state tax benefit for 529 contributions |
| Minnesota | Yes | No | No state tax benefit for 529 contributions |
| Nevada | No | N/A | No state income tax |
| New Hampshire | Yes (I&D only) | N/A | Only taxes interest & dividends, no 529 deduction |
| New Jersey | Yes | No | No state tax benefit for 529 contributions |
| North Carolina | Yes | No | No state tax benefit for 529 contributions |
| South Dakota | No | N/A | No state income tax |
| Tennessee | No | N/A | No state income tax (interest/dividends phased out) |
| Texas | No | N/A | No state income tax |
| Vermont | Yes | No | No state tax benefit for 529 contributions |
| Washington | No (Capital Gains) | N/A | No state income tax (except capital gains) |
| Wyoming | No | N/A | No state income tax |
Note: This table focuses on states without a specific 529 deduction or credit. For a comprehensive list of all states and their 529 deductions, please refer to more detailed guides.
Navigating Your Options with Tax Software and Professional Advice
The world of state taxes and education savings can be incredibly complex, especially when considering moving parts like residency and different state plans. Utilizing the right tools and seeking expert advice can make a world of difference.
Using Tax Software for Multi-State Planning
Even if your state doesn't offer a 529 deduction, you might still find yourself dealing with multi-state tax situations, perhaps if you work in one state and live in another, or if you're a part-year resident. This is where modern tax software becomes invaluable. Programs like TurboTax, H&R Block, or TaxAct are designed to guide you through the intricacies of both federal and state tax filings, often cross-referencing information to ensure accuracy.
While they won't magically create a deduction where none exists, these software platforms can help you:
- Accurately report contributions: Even if not deductible, it's good to keep records.
- Track qualified education expenses: Essential for federal tax-free withdrawals.
- Calculate other deductions and credits: Ensure you're taking advantage of all federal and any available state education tax breaks.
- Manage multi-state tax returns: If you have income from different states, the software can help you prepare the necessary forms for each.
For example, if you reside in a state like New York but decide to use an out-of-state 529 plan, while New York does offer a deduction for its own plan, it won't apply to an out-of-state one. Tax software will help you navigate this distinction and ensure you're reporting everything correctly. This is particularly relevant when you're considering the complexities of States With a Flat Income Tax (2026) versus progressive tax structures, which can affect the overall impact of deductions.
When to Consult a Financial Advisor
While tax software is excellent for filing, it doesn't offer personalized financial planning advice. If you're feeling overwhelmed by your college savings strategy, especially in a non-deduction state, or if your financial situation is particularly complex, consulting a qualified financial advisor is highly recommended.
A financial advisor can help you:
- Develop a comprehensive college savings plan: They can look at your overall financial picture, including retirement savings, other investments, and your budget, to create a holistic strategy.
- Compare 529 plans across different states: They can help you analyze the various investment options, fee structures, and historical performance of different state plans to find the best fit for you, regardless of your state's deduction policy. Many advisors use tools like those offered by SmartAsset to do this in an efficient way.
- Evaluate alternative savings vehicles: They can help you understand if a Roth IRA, ESA, or even a taxable brokerage account might be a better fit for a portion of your college savings, considering your risk tolerance and other financial goals.
- Understand financial aid implications: They can advise you on how different savings vehicles might impact your child's eligibility for need-based financial aid.
- Stay updated on tax law changes: Tax laws are constantly evolving. A good advisor will keep abreast of changes at both federal and state levels that could impact your savings strategy.
Don't hesitate to seek professional guidance. Investing in an hour or two with a fee-only financial planner can save you a lot of stress and potentially maximize your savings in the long run.
Disclaimer
Please remember that tax laws are complex and subject to change. This guide provides general information and should not be considered tax or financial advice. It's always best to consult with a qualified tax professional or financial advisor for personalized advice based on your specific situation.