Best Low-Tax States for Retirees on a Budget
Trying to figure out where to retire can feel like solving a complex puzzle, especially when you're watching every penny. Many folks dream of stretching their hard-earned retirement savings further, but state taxes can be a huge, often unexpected, drain on those dreams. This guide is here to cut through the confusion and help you uncover the best low-tax states that won't just look good on paper, but genuinely make your retirement budget feel more comfortable.
Understanding the Retirement Tax Landscape
It’s easy to get swept up in the idea of moving to a "no income tax" state, but the reality is often more nuanced. State tax policies for retirees are a patchwork quilt across the country, and what seems like a great deal in one area might hide higher costs in another. You need to look at the full picture, not just one piece of the puzzle.
The Hidden Costs of Retirement Taxation
When you're planning for retirement, you're not just looking at your income anymore; you're looking at distributions from 401(k)s, IRAs, pension payments, and Social Security benefits. Each state handles these differently. Some states might not tax Social Security at all, which sounds fantastic, but then they might hit you hard on your pension or 401(k) withdrawals. Others might tax all forms of retirement income but offer generous deductions or exclusions once you hit a certain age or income level.
For example, imagine you're eyeing Florida for its lack of state income tax. That sounds like a dream, right? But then you start looking at property taxes in certain popular coastal areas, or you notice that the sales tax is 6% or 7% on nearly everything you buy, from groceries to home goods. Suddenly, what you saved on income tax might start to vanish through other avenues. It’s a delicate balance, and ignoring one piece can throw off your entire budget. You really need to dig into How Each State Taxes Retirement Income 50-State Guide to get a full picture.
Domicile Versus Statutory Residency for Tax Purposes
One of the biggest pitfalls many retirees face when moving to a new state for tax reasons is misunderstanding the difference between domicile and statutory residency. You might think you've moved to a low-tax state, but if your old state believes you still maintain your "domicile" there, they could continue to try and tax your income. Your domicile is essentially your true, fixed home, the place you intend to return to whenever you're away. It's about intent, but states look for concrete evidence.
On the other hand, statutory residency is often determined by how many days you spend in a state, typically the "183-day rule." If you spend more than half the year in a state, even if you don't consider it your permanent home, that state might deem you a statutory resident and claim the right to tax your income. This is why it’s critical to formally establish residency in your new state and sever ties with your old one. You’ll want to review resources like State Tax Residency Rules Explained and How to Change Your State Residency for Taxes to avoid any nasty surprises.
Top States for Retirees on a Budget
When we talk about the "best" states for retirees on a budget, we're not just looking for the flashiest tax breaks. We're looking for an overall environment where your money genuinely goes further, combining favorable tax policies with a reasonable cost of living. This often means carefully weighing income tax benefits against other taxes you'll inevitably pay.
States with No or Very Low Retirement Income Tax
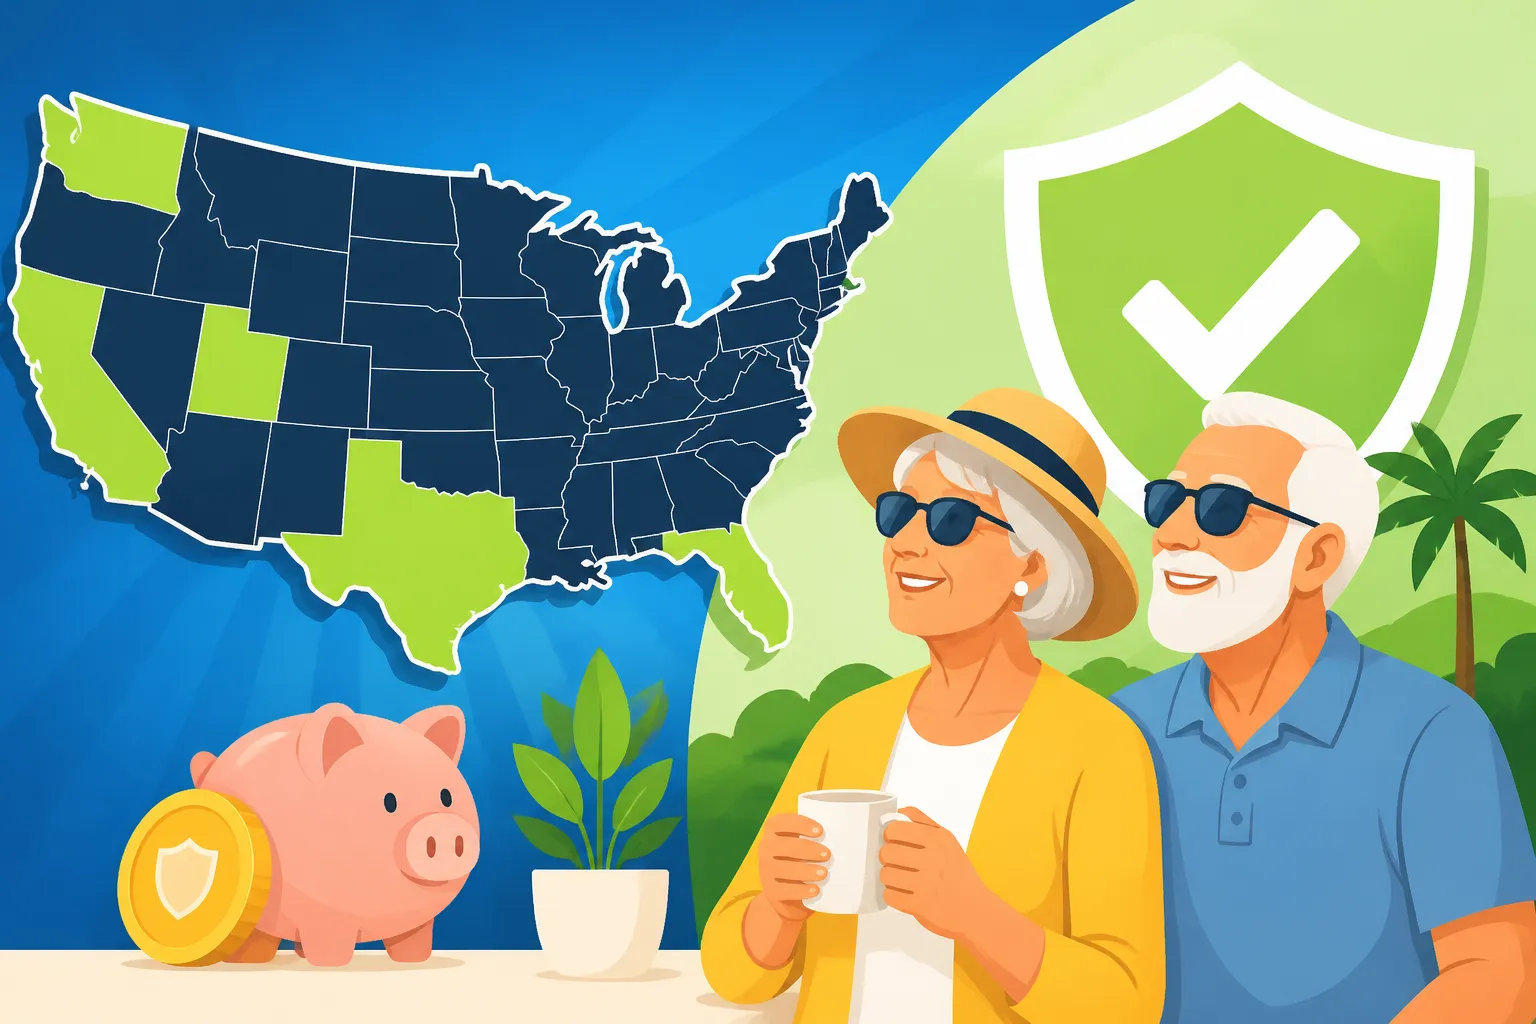
Nine states currently boast no state income tax, which is often the first thing retirees look for: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. New Hampshire taxes only interest and dividends, though that's slated to be fully phased out by 2027. These states are often championed as the ultimate havens for retirees, and for good reason! If your primary income source is from retirement accounts or pensions that would normally be heavily taxed in a high-income-tax state, these places can offer substantial savings. For a full list, check out States With No Income Tax 2026 Full List.
However, "no income tax" doesn't mean "no taxes." These states still need to fund their public services, so they often make up the difference through higher sales taxes, property taxes, or excise taxes. For instance, while Florida doesn't tax your pension, some areas have pretty steep property taxes. Similarly, Texas has no state income tax, but its property taxes are among the highest in the nation. It's a trade-off you need to be aware of.
Beyond the nine no-income-tax states, many other states offer significant exemptions or deductions for various types of retirement income. Pennsylvania, for example, is incredibly tax-friendly for retirement income, exempting most pension and 401(k)/IRA distributions from state income tax, alongside Social Security. Illinois also exempts all retirement income, including Social Security, pensions, and 401(k) withdrawals, from state income tax. Mississippi offers a full exemption for all retirement income, including Social Security, IRAs, 401(k)s, and pensions. These states can be excellent choices if you’re trying to avoid paying state income tax on pension income.
Balancing Income and Property Tax Burdens
The real trick is finding a state where the sum of all taxes – income, property, and sales – works in your favor. A state like Delaware, for example, has no sales tax and relatively low property taxes, and it doesn't tax Social Security benefits. While it does have an income tax, it offers generous pension exemptions, making it attractive for many retirees.
Let's compare a few common choices. Arizona is popular for retirees due to its climate. It has a relatively low state income tax, and it doesn't tax Social Security. Property taxes are also generally below the national average. Contrast that with, say, New Jersey, which has some of the highest property taxes in the nation, even though it offers some retirement income exclusions. For those aiming to avoid higher income taxes altogether, States That Don't Tax Social Security (2026) and States That Don't Tax Pensions (2026) offer good starting points, but you have to dig deeper into the property tax implications.
Here's a quick look at how some popular retirement destinations stack up on key tax factors for 2026:
| State | Income Tax on SS Benefits | Income Tax on Pensions/401(k)s | State Sales Tax Rate | Average Effective Property Tax Rate |
|---|---|---|---|---|
| Florida | No | No | 6.00% | 0.98% |
| Texas | No | No | 6.25% | 1.69% |
| Wyoming | No | No | 4.00% | 0.51% |
| Tennessee | No | No | 7.00% | 0.64% |
| Pennsylvania | No | No (most) | 6.00% | 1.34% |
| Delaware | No | No (up to $12,500 exclusion for seniors) | 0.00% | 0.58% |
| Arizona | No | Yes (with potential subtractions) | 5.60% | 0.62% |
| Georgia | No | No (up to $65,000 exclusion for 62+, unlimited for 65+) | 4.00% | 0.91% |
Note: Sales and property tax rates can vary significantly by county and city. Property tax rates here are average effective rates as a percentage of home value.
This table, while simplified, helps illustrate that a "no income tax" state like Texas might come with a higher property tax burden, while a state like Delaware has a low property tax rate and no sales tax, making its income tax considerations less daunting for some retirees. Tools from financial analysis companies like SmartAsset can be incredibly helpful for comparing these complex factors side-by-state, allowing you to tailor your search based on your specific income sources and spending habits.
Beyond Income Tax: Other Factors to Consider
Taxes are undeniably a huge factor, but they're not the only factor when you're looking for the best place to retire on a budget. The true cost of living involves so much more than just what you pay the government. You have to think about what your day-to-day life will actually look like and how much it will cost to live it.
Sales Tax and Everyday Expenses
Even if a state doesn't tax your income, it might have a high sales tax that eats into your daily budget. Think about it: every time you buy groceries (though some states exempt food), new clothes, gas for your car, or enjoy a meal out, you're paying sales tax. Some states, like Tennessee, have a high statewide sales tax rate, plus local sales taxes that can push the combined rate over 9% in some areas. If you're a retiree who plans to shop frequently, eat out, or make larger purchases like a new car, a high sales tax can really add up.
On the other hand, states like Oregon, Montana, and Delaware don't have a statewide sales tax at all. This can lead to significant savings on consumer goods over the course of a year, especially for those who enjoy shopping. It’s an important consideration, particularly if a substantial portion of your retirement spending goes towards retail and services rather than just housing. Always factor in how your spending habits align with a state's sales tax structure.
Property Tax and Homestead Exemptions
Property taxes are often the single largest annual tax expense for homeowners, and they can vary wildly from one state to another, and even from county to county within the same state. As mentioned, states without an income tax often rely more heavily on property taxes to fund local services like schools and fire departments. For instance, New Hampshire, which doesn't tax earned income, has some of the highest property tax rates in the country.
However, many states offer homestead exemptions or other property tax relief programs specifically for seniors or low-income residents. These exemptions can significantly reduce the taxable value of your primary residence. For example, in Texas, while overall property taxes are high, homeowners can claim a general homestead exemption, and those over 65 often qualify for an additional "over 65" exemption, freezing a portion of their school district taxes. Learning about these programs is crucial; you can find more information about these kinds of savings by looking into Homestead Exemption by State. SmartAsset provides fantastic county-level data on property taxes, which is incredibly useful because statewide averages can sometimes mask significant differences in local tax rates.
Cost of Living Versus Tax Burden
It’s easy to focus solely on taxes, but the overall cost of living is equally, if not more, important for retirees on a budget. A state might have incredibly low taxes, but if housing is exorbitant, groceries are expensive, and utilities cost a fortune, your overall budget might not go as far. Conversely, a state with a slightly higher income tax might have a much lower cost of living, leading to a better quality of life for the same amount of retirement income.
Consider a state like Arkansas. It taxes retirement income, but its overall cost of living is significantly below the national average, particularly for housing. For some retirees, paying a modest income tax might be preferable if it means their overall monthly expenses for necessities are much lower. This is a vital calculation that often gets overlooked in the chase for "no income tax" states. Always look at the full picture of Cost of Living vs Taxes by State to ensure you're making a truly budget-friendly move.
Making Your Move: Practical Considerations
Once you've narrowed down your list of potential states, the next steps involve careful planning and execution. Moving for retirement is a big life change, and you want to ensure you've dotted all your i's and crossed all your t's, especially when it comes to financial and legal matters.
Establishing Residency Legally and Formally
Establishing legal residency is more than just packing your bags and moving. To truly benefit from a new state's tax laws, you need to prove your intent to make that state your new, permanent home. States with high income taxes are particularly vigilant about tracking former residents who claim to have moved, often initiating audits to verify changes in domicile. They look for tangible evidence of your commitment to the new state.
This means:
- Changing your driver's license and vehicle registration: This is usually one of the first and most critical steps.
- Registering to vote: Showing that you're participating in local elections signals your intent.
- Updating your mailing address: Make sure all financial statements, bills, and important documents go to your new address.
- Opening new bank accounts and moving existing ones: Having local accounts can serve as evidence.
- Updating your will, trust, and estate planning documents: Ensure these reflect your new state of residence and its laws.
- Severing ties with your previous state: This might mean selling your old home, canceling club memberships, or changing doctors.
- Spending the majority of your time there: As discussed earlier, the 183-day rule is a significant factor in many states.
Failure to properly establish your new domicile could lead to your old state continuing to claim you as a resident and taxing your income, potentially leading to double taxation or stressful audits. Resources like How to Establish Florida Domicile or How to Prove You Changed Your Domicile can offer detailed checklists to guide you through this process.
Professional Advice and Planning
Navigating the complexities of state tax laws, retirement planning, and residency rules is not a task you should undertake lightly. While articles like this one can provide a solid foundation, every individual's financial situation is unique. What works for one retiree might not be optimal for another.
This is where a qualified financial advisor, especially one specializing in retirement planning and multi-state tax implications, becomes invaluable. They can help you:
- Analyze your specific income streams: Understand how your Social Security, pensions, 401(k)s, IRAs, and other investments will be taxed in various states.
- Project your future expenses: Create a realistic budget that accounts for local cost of living, not just taxes.
- Identify potential deductions and credits: Uncover specific state-level benefits you might be eligible for as a senior or retiree.
- Develop a residency establishment plan: Advise you on the exact steps needed to legally and formally change your domicile.
Many advisors use advanced tools to model different scenarios, showing you exactly how much you could save (or spend) by moving to various states. Additionally, reputable platforms like SmartAsset offer free online tools and resources, including calculators and articles, to help you compare states based on a variety of financial metrics. They can even connect you with vetted financial advisors who can provide personalized guidance. Remember, a small investment in professional advice upfront can save you significant money and headaches down the road, ensuring your golden years are truly golden.
Disclaimer
Please remember that tax laws are complex and subject to change. This information is intended for general guidance only and does not constitute professional tax or financial advice. We strongly recommend consulting with a qualified tax advisor or financial planner to discuss your specific situation and make informed decisions.