Renters’ Tax Credits by State
It's incredibly frustrating when tax season rolls around, and all you hear about are the mortgage interest deductions, property tax breaks, and homestead exemptions homeowners get. If you're a renter, it often feels like you're completely left out of the tax-saving conversation, even though you’re contributing to property taxes indirectly through your rent payments. But here's some good news: some states actually offer specific tax credits designed to put a little money back in renters' pockets. This comprehensive guide will walk you through the world of renters' tax credits by state, helping you understand who qualifies, how to claim them, and what to look out for.
Understanding Renters' Tax Credits: A State-by-State Overview
For many years, the tax code has seemed to heavily favor homeowners, leaving renters feeling like second-class citizens when it comes to tax relief. But as housing costs have soared, and the plight of renters has become more visible, some states have stepped up to offer specific tax benefits. These aren't universal, and they vary wildly in scope and generosity, but understanding them is your first step toward potential savings.
What Exactly Are Renters' Tax Credits?
At its core, a renters' tax credit is a direct reduction in your state income tax liability. Unlike a deduction, which reduces your taxable income, a credit directly reduces the amount of tax you owe, dollar for dollar. For example, a $100 tax credit means your tax bill drops by $100. If the credit is refundable, and you owe less than the credit amount, you might even get the difference back as a refund, even if your tax liability was zero. This is a significant distinction that makes credits particularly valuable.
These credits are typically designed to help offset the portion of your rent that effectively goes towards property taxes paid by your landlord. Landlords usually factor their property tax expenses into the rent they charge, meaning renters indirectly bear some of that property tax burden without getting any direct tax relief. Renters' tax credits aim to correct this imbalance, providing some financial relief to those who might otherwise struggle with high housing costs, especially low to moderate-income individuals and families, seniors, or those with disabilities.
Eligibility for these credits often hinges on several factors, including your income level, age, disability status, the amount of rent you pay, and your residency status within the state. Each state sets its own parameters, making it crucial to check the specific rules for where you live. For instance, some states might have very low-income thresholds, making the credit accessible only to the truly economically disadvantaged, while others might offer a broader reach. The details truly matter here, and a little digging can yield significant benefits.
The Uneven Landscape of Renters' Relief
It’s important to manage expectations from the outset: not every state offers a direct renters' tax credit. In fact, many states do not. The landscape of renters' relief is incredibly uneven, resembling a patchwork quilt rather than a uniform blanket of support. Some states have robust programs that have been in place for years, while others offer very limited or highly targeted benefits. Then there are states that offer nothing specifically for renters, often arguing that general income tax deductions or broader tax relief measures are sufficient, or simply prioritizing homeowners in their tax policies.
This disparity can be frustrating for renters, especially those living in high-cost states where a significant portion of their income goes towards housing. For example, a renter in San Francisco, California, might be eligible for a state credit, whereas a renter across the country in, say, Dallas, Texas, generally won't find a similar state-level income tax credit because Texas has no state income tax at all. This highlights how deeply intertwined tax policy is with local economic conditions and political priorities.
The rationale behind offering these credits often stems from a recognition of the regressive nature of property taxes, and the desire to provide some equity in the tax system. Housing affordability is a major concern across the nation, and renters, who often face rising rents and stagnant wages, are particularly vulnerable. Legislators in some areas are pushing for greater tax equity, leading to the creation or expansion of these credits. However, other states might prioritize other forms of tax relief, or simply lack the political will or budget capacity to implement such programs.
States Leading the Way with Robust Renters' Tax Credits
While not universal, some states have recognized the unique financial pressures faced by renters and have implemented substantial programs to provide tax relief. These states often stand out for their commitment to housing affordability and tax equity.
California's Renter's Credit: More Than Meets the Eye
California, known for its high cost of living and progressive tax policies, offers a renter's credit. However, it's crucial to understand the specifics, as it's not as broadly accessible as some might hope, and its value can be modest for many. The California Renter's Credit is a nonrefundable tax credit, meaning it can reduce your tax liability to zero, but you won't get any money back if the credit exceeds your tax due. While this might sound less exciting than a refundable credit, it can still provide meaningful savings for eligible individuals.
To qualify for the California Renter's Credit, you generally need to have been a California resident for at least half the tax year and have paid rent for at least half the year. Critically, there are income limitations, and these are often quite low compared to the actual cost of living in California. For the 2026 tax year, the income thresholds remain a significant barrier for many middle-income renters. For instance, a single individual might only qualify if their adjusted gross income (AGI) is below a certain threshold, which could be around $43,000, while married couples filing jointly might see a cap around $86,000. These figures are subject to change, so always check the most current Franchise Tax Board (FTB) guidelines. The credit amounts are also relatively modest, typically $60 for single filers and $120 for married couples filing jointly or heads of household.
Let's consider a real-world scenario: Imagine Maria, a single mother living in a small apartment in Los Angeles, earning $40,000 a year as a teaching assistant. She's been a California resident all year and has paid rent consistently. Her income falls within the eligibility limits, so she can claim the $60 nonrefundable credit. While $60 might not seem like a huge amount in the grand scheme of California living expenses, it's still $60 that stays in her pocket rather than going to the state, perhaps covering a week's worth of groceries. This credit is claimed on Form 540, California Resident Income Tax Return, and requires careful attention to the specific income and residency requirements. For a deeper dive into this, you might find our article on California Renters Credit 2026 particularly helpful.
Minnesota's Property Tax Refund for Renters
Minnesota takes a slightly different, and often more generous, approach. Instead of a direct "renter's credit," it offers a "Property Tax Refund" program that extends to renters. This program is typically refundable, meaning if the credit amount exceeds your tax liability, you get the difference back. This makes it a powerful tool for low- to moderate-income individuals and families. The underlying philosophy is similar to a traditional renters' credit: acknowledging that renters indirectly pay property taxes through their rent and providing relief.
Eligibility for Minnesota's renter's property tax refund is primarily based on your household income and the amount of rent you've paid during the year. You also need to have been a full-year resident of Minnesota. The refund is calculated based on a percentage of the rent you paid, minus a small deductible amount, and it phases out as your income increases. The maximum refund can be quite substantial, often reaching several hundreds or even over a thousand dollars for those with lower incomes and higher rent payments. It’s also important to note that the refund calculation takes into account not just rent, but also any mobile home park lot rent or manufactured home property tax.
Consider David, a single individual who works in a non-profit in Minneapolis, earning $35,000 a year, and paying $1,200 a month in rent. After factoring in his income and total rent paid for the year, he might be eligible for a significant property tax refund from the state. He would file Form M1PR, Homestead Credit Refund (for Homeowners) and Renter's Property Tax Refund. The process involves detailing his income and rent payments, which the state uses to calculate the refund amount. This can be a real game-changer for someone like David, providing a much-needed boost to his budget. You can learn more about this specific program in our dedicated piece on the Minnesota Renters Credit.
Other Notable States with Significant Programs
Beyond California and Minnesota, a few other states offer substantial tax benefits for renters, though they might be structured differently.
-
Massachusetts: The Bay State offers a "Circuit Breaker" tax credit that primarily benefits seniors and low-income individuals, and importantly, it extends to renters. If your property tax payments (or 25% of your annual rent, as an approximation of property tax) exceed 10% of your total income, you might qualify for a refundable credit. Eligibility often requires you to be 65 or older, or disabled, and meet specific income thresholds. For example, a senior couple in Boston, both over 65, living on a fixed income of $30,000 and paying $1,800 a month in rent, could potentially qualify for a significant credit to offset their housing burden. This is reported on Schedule CB, Circuit Breaker Credit.
-
New Jersey: The Garden State provides property tax relief benefits that include a tenant rebate program. While not a direct income tax credit, it operates similarly by providing financial relief to qualifying renters. Eligibility is often based on age (65 or older) or disability status, and income limits. Renters can receive a direct rebate check, which is incredibly helpful, especially in a state with some of the highest property taxes in the nation.
-
New York: New York offers a Real Property Tax Credit, which can be claimed by eligible residents, including renters. This credit is refundable and income-based, with specific thresholds that vary by filing status and income. To qualify, you generally must be a full-year New York resident and have a household gross income below certain limits (e.g., around $18,000 for single filers or $25,000 for married couples). The credit amount depends on your income, household size, and the amount of rent paid. For instance, a single individual living in an apartment in Queens, earning $15,000 a year, would be able to claim this credit, providing valuable relief from the high cost of living in the Empire State.
These examples illustrate that while the names and specific mechanics differ, the goal is often the same: to alleviate the financial strain on renters. It's crucial to consult your state's tax department website or use reliable tax software like TurboTax to ensure you're claiming all eligible benefits. For a broader overview, you can check out our main guide on Renters' Tax Credits by State.
States with Limited or Targeted Renters' Tax Benefits
While some states have embraced comprehensive renters' relief programs, many others offer either very limited options or no specific renters' tax credits at all. This often leaves renters in these areas feeling overlooked when it comes to state-level tax benefits.
The Scarcity of Direct Credits
The reality is that in a large number of states, a direct, standalone renters' income tax credit simply doesn't exist. This can be due to a variety of reasons, including legislative priorities that lean towards other forms of tax relief, state budget limitations, or a general focus on property ownership as the primary avenue for housing-related tax benefits. In many places, the political will to create specific benefits for renters just isn't there, or it's overshadowed by other concerns.
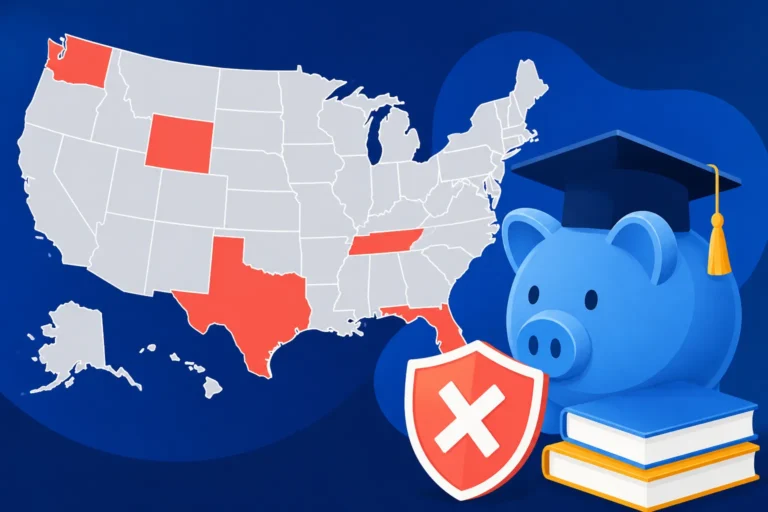
Consider a renter in Florida. Florida is one of the states with no state income tax, which sounds appealing, but it also means there are no income tax credits of any kind, including for renters. While the absence of income tax is a benefit in itself, it also means renters here don't have that specific avenue for relief that income tax states might offer. Similarly, in states like Texas or Washington, which also boast no state income tax, direct renters' tax credits are not part of the tax code. If you're residing in one of the States With No Income Tax (2026 Full List), your state tax burden might be lower overall, but specific rental-related credits won't be available at the state income tax level.
In states that do have an income tax but lack a specific renters' credit, individuals might still benefit from broader, general low-income tax credits or deductions that are not housing-specific but happen to include many renters. For example, a state's general Earned Income Tax Credit (EITC) might help low-income renters, but it's not designed to address the unique burden of rent itself. The absence of a targeted credit means that the indirect property tax burden carried by renters goes unaddressed in these state tax systems. This often leads to advocacy groups pushing for legislative changes to introduce such credits, recognizing the increasing pressure of rental costs on household budgets.
Property Tax "Circuit Breaker" Programs That Include Renters
While not always called a "renters' tax credit," some states offer "circuit breaker" programs that can provide relief to eligible renters by limiting the amount of property tax they effectively pay. These programs are designed to protect low-income individuals, especially seniors and those with disabilities, from losing their homes or facing severe financial hardship due to high property taxes. The "circuit breaker" metaphor implies that when property taxes reach a certain percentage of a household's income, the program kicks in to "break" the circuit and limit the burden.
For renters, these programs often work by assuming a certain percentage of their annual rent payments represents their indirect contribution to property taxes. This "property tax equivalent" is then used in the circuit breaker calculation. If this deemed property tax burden exceeds a certain percentage of the renter's income (the "circuit breaker" threshold), the renter may be eligible for a refund or credit. The specific percentage of rent considered as property tax equivalent varies by state, but it’s commonly around 15% to 20% of annual rent.
States like Vermont and Maine, for example, have property tax relief programs that incorporate renters, often through a similar mechanism. In Vermont, the Homestead Property Tax Income Sensitivity Adjustment and Renter Rebate program allows eligible residents, including renters, to claim a credit if their property tax (or a portion of their rent) exceeds a certain percentage of their household income. These programs typically have strict income and sometimes age or disability requirements. For instance, an elderly couple in Bangor, Maine, living on social security, might apply for a property tax fairness credit where a portion of their rent qualifies them for a refundable credit, easing their financial strain. While not explicitly a "renters' credit," these circuit breaker programs serve a similar purpose of providing housing-related tax relief. Understanding if your state has such a program, even if it's not explicitly named for renters, is crucial. You can often find comprehensive information on such programs by looking into Property Tax Circuit Breaker Programs within your state.
Navigating Eligibility and Application Challenges
Even in states that offer renters' tax credits, actually qualifying for and successfully claiming them can be a detailed process. It requires careful attention to rules, deadlines, and documentation. Don't let the complexity deter you, though; a bit of organization can unlock significant savings.
Income Thresholds and Residency Requirements
One of the biggest hurdles for many renters is meeting the specific income thresholds set by each state. These limits are often designed to target relief to low- to moderate-income households, which means if your income is above a certain level, you might be ineligible, even if you're struggling with high rent. It's not always about your adjusted gross income (AGI) either; some states consider "household income," which can include income from all members of your household, even if they aren't directly on your tax return. This can be tricky if you live with roommates or adult children who contribute to household expenses but file their taxes separately.
For example, New York's Real Property Tax Credit for renters has relatively low household income limits, meaning a single individual earning just above the poverty line might qualify, but someone earning a moderate income in a high-cost area like Brooklyn might quickly exceed the threshold. This can feel unfair, as even moderate earners in expensive cities can struggle significantly with rent. It's important to consult the state's official tax publications or use resources like SmartAsset to accurately determine what income is counted and what the current thresholds are for the tax year you're filing.
Beyond income, residency is another critical factor. Most renters' tax credits require you to be a full-year resident of the state for which you are claiming the credit. If you moved mid-year, you might qualify as a part-year resident, but the credit amount could be prorated, or you might not qualify at all depending on the state's specific rules. For instance, if you lived in Illinois for eight months and then moved to Indiana for the remaining four, you'd file as a part-year resident in both states. While Indiana has a renters' deduction, not a credit, you'd need to ensure your residency status aligns with the requirements for any benefits in either state. Our guide on Resident vs Nonresident vs Part-Year Resident can help clarify these distinctions. To prove residency and rent paid, you'll need documentation like your lease agreement, rent receipts, and proof of income (W-2s, 1099s). It's a good practice to keep all these documents meticulously organized throughout the year.
The Application Process: Forms, Deadlines, and Pitfalls
Once you've determined your eligibility, the next step is the application process itself. This usually involves filing a specific form with your state's revenue department, often alongside your regular state income tax return. The forms can vary significantly from state to state; for example, in California, you'd claim the renter's credit directly on Form 540, while in Minnesota, it involves a separate form, M1PR. You'll typically find these forms, along with detailed instructions, on your state's official tax website.
Common pitfalls include missing deadlines, which are usually aligned with the general state income tax deadline (often April 15th, but sometimes later if an extension is granted, though the payment itself is usually still due by the original date). Filing an incomplete form or providing inaccurate information can lead to delays in processing your refund or, worse, an audit. It's crucial to double-check all calculations, especially the portion of your rent that qualifies (some states exclude utility payments or other fees). Many states provide online calculators or worksheets to help you determine the correct amount.
Many people find tax software invaluable for navigating these complexities. Platforms like TurboTax are designed to walk you through the process, asking questions about your income, residency, and rental payments, and then automatically calculating any eligible state tax credits. This can significantly reduce the chances of making a mistake. However, always remember to verify the information against official state guidelines. For a comprehensive overview of how to file, check out our How to File State Taxes: Complete Guide.
The Importance of Accurate Record-Keeping
This might sound like a broken record, but I cannot stress enough how important accurate record-keeping is when it comes to claiming any tax credit, especially those related to housing. Your state's tax department won't just take your word for it; they'll want proof.
Here's what you should be keeping throughout the year:
- Lease Agreements: Your current and any past lease agreements for the tax year. These documents verify your rental status, the address, and the amount of rent agreed upon.
- Rent Receipts or Payment Records: This could be cancelled checks, bank statements showing rent payments, money order receipts, or statements from your landlord. These prove you actually paid the rent you're claiming.
- Proof of Residency: Documents like utility bills, driver's license, or voter registration can help establish your residency for the required period.
- Income Documentation: W-2s, 1099s, and any other statements of income.
- Correspondence with your Landlord: Any written communication regarding rent changes, repairs, or other financial matters.
You should aim to keep these records for at least three years from the date you filed your return, as this is the general statute of limitations for state tax audits. Imagine being audited two years down the line and not being able to prove your rent payments – that could mean losing your credit and potentially owing back taxes, penalties, and interest. Having a dedicated folder, either physical or digital, for your tax documents is a simple habit that can save you a world of headache.
Comparing Renters' Credits with Other State Tax Benefits
The conversation about renters' tax credits often happens in the broader context of state tax benefits, which have historically favored homeowners. Understanding this comparison, and exploring other general benefits that might apply to renters, can help you paint a clearer picture of your overall tax situation.
Homeowners vs. Renters: A Persistent Disparity
It’s no secret that homeowners have long enjoyed a slew of tax advantages that simply aren't available to renters. Federal tax law allows homeowners to deduct mortgage interest and property taxes, which can amount to significant savings, especially for those with larger mortgages and in areas with high property values. Many states mirror these federal deductions or offer their own state-specific ones. This includes deductions for real estate taxes paid and, in some cases, even credits for energy-efficient home improvements. Our article on State Tax Deductions for Homeowners goes into more detail on these benefits.
This disparity has created a sense of unfairness among renters, who, as we discussed, often indirectly contribute to property taxes through their rent payments without receiving the corresponding tax breaks. While renters' tax credits aim to mitigate this imbalance, they rarely fully level the playing field. The credit amounts are often modest, and eligibility can be restrictive, meaning many renters still find themselves with fewer tax-saving opportunities than their homeowning counterparts. The frustration is understandable, especially in today's housing market where homeownership feels increasingly out of reach for many, forcing them into a rental market that offers less financial stability and fewer tax advantages. This ongoing debate about tax equity between renters and homeowners is a significant one in state legislative bodies across the country.
Broader State Tax Credits That May Benefit Renters
Even if your state doesn't offer a specific renters' tax credit, you might still be eligible for other broader state tax credits that can provide relief. These aren't tied directly to your rental status but can certainly help offset your overall tax burden, freeing up funds that can then be used for housing costs.
One of the most significant is the State Earned Income Tax Credit (EITC). Many states have adopted their own versions of the federal EITC, often designed to boost the income of low- to moderate-income working individuals and families. These credits are frequently refundable, meaning you could receive money back even if you owe no state tax. Renters in lower-income brackets are precisely the demographic this credit is designed to help. For example, a single parent renting an apartment in Colorado and working full-time at a modest wage could qualify for both the federal and Colorado EITC, providing a substantial boost to their annual income. To see if your state offers this, you can explore our guide on the State Earned Income Tax Credits (EITC) Guide.
Another increasingly common benefit is the State Child Tax Credit. Following expansions at the federal level, many states have introduced or expanded their own child tax credits, aimed at helping families with children. These credits can also be refundable and significantly reduce a family's tax liability. For a family with multiple children renting an apartment in, say, New York, the combination of the state's Real Property Tax Credit (if they meet income limits) and a robust State Child Tax Credit could dramatically improve their financial situation. Our article on State Child Tax Credits 2026 provides a detailed look at where these are available.
Additionally, some states offer general low-income tax credits, property tax circuit breakers (as mentioned, some of which include renters by proxy), or even specific credits for seniors or individuals with disabilities that might apply to renters. The key is to look beyond just "renters' credits" and explore the full spectrum of state tax benefits for which you might qualify based on your income, family situation, and other personal circumstances. Resources like SmartAsset often compile comprehensive lists of state-specific deductions and credits, making it easier for you to identify potential savings opportunities and better understand How to Lower Your State Income Tax.
Future Trends and Advocacy for Renters' Tax Relief
The current economic climate, marked by soaring rents and a persistent housing affordability crisis, is bringing the issue of renters' tax relief to the forefront. This means that while the current landscape might be uneven, there's growing momentum for change and expansion of these vital programs.
The Growing Call for Housing Affordability Solutions
Across the country, the issue of housing affordability is reaching critical levels. Rents have been steadily increasing, outpacing wage growth in many areas, and putting immense pressure on household budgets. This is not just a coastal city problem; communities in every state are grappling with the challenges of ensuring residents can afford a safe and stable place to live. As a result, there's a growing call from advocacy groups, economists, and even some political leaders to implement more robust solutions, and renters' tax credits are a key part of that conversation.
Legislators are increasingly recognizing that tax policies heavily skewed towards homeowners exacerbate housing inequality. Proposals for new or expanded renters' tax credits are emerging in various state legislatures as a way to directly address the financial strain on renters. For instance, states that currently offer limited benefits might consider expanding their programs, increasing credit amounts, or raising income thresholds to reach a wider segment of the population. We might also see more states adopting refundable credits, which provide a more impactful benefit to low-income renters who might otherwise owe little to no state income tax. This trend is driven by a broader understanding that stable housing is fundamental to economic well-being and that current tax structures need updating to reflect the realities of the modern housing market.
How to Stay Informed and Advocate for Change
Given the dynamic nature of state tax laws, staying informed is crucial. What's true for the 2026 tax year might change for 2027 or beyond, as states continuously evaluate and modify their tax codes. Here are some proactive steps you can take:
- Track State Legislative Sessions: Many state legislative websites allow you to track bills related to housing and taxation. Following these discussions can give you an early heads-up on potential changes to renters' tax credits or the introduction of new programs.
- Engage with Local Housing Advocacy Groups: Organizations dedicated to housing justice and affordability are often at the forefront of pushing for these types of tax reforms. Joining their mailing lists or participating in local meetings can keep you updated and give you a voice. Groups like the National Low Income Housing Coalition (NLIHC) or state-specific tenants' rights organizations are excellent resources.
- Contact Your State Representatives: Elected officials are more likely to act when they hear directly from their constituents. Share your personal experiences regarding rental costs and advocate for the expansion of renters' tax relief. A thoughtful letter or email can make a difference.
- Consult State Revenue Department Websites: Your state's Department of Revenue or Franchise Tax Board website is the official source for all tax-related information. They will publish updates on new credits, eligibility requirements, and forms. Subscribing to their newsletters (if available) can ensure you receive timely notifications.
- Utilize Reputable Tax News Sources: Websites and blogs specializing in state tax policy, like those provided by SmartAsset, often break down complex legislative changes into understandable information. Keeping an eye on these resources can help you anticipate and adapt to changes that might affect your eligibility for various credits.
By staying engaged and informed, renters can not only maximize their current tax savings but also contribute to the ongoing efforts to create a more equitable and affordable housing landscape for everyone.
| State | Program Name | General Eligibility | Key Features |
|---|---|---|---|
| California | Renter's Credit | CA resident for 6+ months, paid rent for 6+ months, meet specific low-income thresholds (e.g., ~$43k single, ~$86k joint for 2026). | Nonrefundable credit (reduces tax owed to zero, no cash back). Modest credit amount ($60 single, $120 joint). Claimed on Form 540. Aimed at low-to-moderate income renters. |
| Minnesota | Renter's Property Tax Refund | MN resident, paid rent, meet household income requirements. | Refundable credit. Calculates refund based on percentage of rent paid and household income, minus a deductible. Can be substantial for lower incomes. Claimed on Form M1PR. |
| Massachusetts | Circuit Breaker Tax Credit (includes renters) | MA resident, 65+ or disabled, meet income limits, property tax (or 25% of rent) exceeds 10% of total income. | Refundable credit. Helps offset property tax burden (or deemed property tax burden for renters). Income limits and age/disability requirements. Reported on Schedule CB. |
| New York | Real Property Tax Credit (includes renters) | NY resident, household gross income below specific limits (e.g., ~$18k single, ~$25k joint), paid rent. | Refundable credit. Amount depends on income, household size, and rent paid. Designed for low-income residents. Claimed on Form IT-214. |
| New Jersey | Tenant Rebate Program | NJ resident, 65+ or disabled, meet income limits (e.g., ~$150k for seniors/disabled, ~$75k for others), lived in rental property. | Not a direct income tax credit, but a direct rebate check. Helps offset property tax portion of rent. Income and age/disability requirements. Application separate from income tax filing. |
| Connecticut | Renters' Rebate Program | CT resident, 65+ or disabled, income limits (e.g., ~$45k single, ~$53k married), paid rent. | Not an income tax credit but a direct check payment. Max payment ranges. Must apply directly to municipality. |
| Maine | Property Tax Fairness Credit (includes renters) | ME resident, paid rent or property tax, meet income limits. | Refundable credit. Calculates credit based on rent or property tax paid, and income. Max credit typically around $1,000. Claimed on Form 1040ME, Schedule PTFC. |
Note: Eligibility requirements, income thresholds, and credit/rebate amounts are subject to change annually. Always refer to the most current information from your state's official Department of Revenue or Franchise Tax Board for precise details.
Disclaimer
Please remember that this article provides general informational guidance on state tax credits for renters and should not be considered professional tax advice. Tax laws are complex and vary by state and individual circumstances. It is always recommended to consult with a qualified tax professional or refer to your state's official Department of Revenue website for personalized advice regarding your specific tax situation.