Most Tax-Friendly States for Retirees 2027
The dream of retirement often involves picturing sunny beaches, quiet mountain retreats, or vibrant city life, free from the daily grind. But let's be honest, the reality can come with a major headache: figuring out how state taxes will impact your hard-earned savings and fixed income. Many retirees find themselves wondering which states will let them keep more of their money, making the golden years truly golden. This comprehensive guide is here to shed light on the most tax-friendly states for retirees, helping you navigate the complex world of state taxation with clarity and confidence.
Understanding the Landscape of Retirement Taxation
For many, retirement means a shift in income sources and, often, a fixed budget. This makes understanding your tax landscape absolutely critical. It’s not just about federal taxes; state-level taxation can vary wildly and significantly impact your financial well-being. What might seem like a small percentage difference could amount to thousands of dollars over the course of your retirement, affecting everything from your travel budget to your ability to handle unexpected expenses.
Why State Taxes Matter So Much for Retirees
When you're working, your income is typically coming from a steady paycheck, and your tax obligations might feel relatively straightforward. However, in retirement, your income streams diversify. You might be drawing from Social Security, a pension, 401(k)s, IRAs, and perhaps still have some investment income or part-time earnings. Each state has its own unique way of looking at these different income types, deciding what to tax, what to exempt, and at what rate.
Think about it this way: if you’re living on a fixed income, say $60,000 a year, and one state taxes a significant portion of that while another exempts it, the difference in your disposable income can be substantial. This isn't just theoretical; it translates directly into your quality of life. More disposable income means more flexibility for healthcare costs, visiting grandchildren, pursuing hobbies, or simply having peace of mind. Choosing the right state isn't just a financial decision; it's a lifestyle one, directly linked to how much financial freedom you'll enjoy. A state that is generous with its exemptions can truly make a difference in your day-to-day living and long-term financial security.
Key Types of Income Taxed in Retirement
When we talk about retirement income, we're usually looking at a few distinct categories. First up, there's Social Security benefits. For many, this is a cornerstone of their retirement income, and whether a state taxes it or not is a huge deal. Then, you have pensions – whether they're from a private employer, a government entity, or military service. Each type of pension can be treated differently by state tax codes.
Next, and increasingly common, are distributions from retirement accounts like 401(k)s, traditional IRAs, and other deferred compensation plans. These are the funds you’ve been diligently saving for years, and how a state taxes their withdrawal can greatly affect their net value. Finally, many retirees have investment income from stocks, bonds, mutual funds, or rental properties, which typically fall under capital gains and dividends. Some states have specific rules or exemptions for these as well, making the whole picture quite intricate. Knowing how each of these income sources is treated in potential retirement states is the first step in painting a clear financial future.
The Gold Standard: States with No Income Tax
For many retirees, the holy grail is a state with no income tax. It sounds simple, right? Just move there, and your pensions, 401(k) withdrawals, and other income are all tax-free at the state level. While this is largely true, it's important to understand the full picture and not jump to conclusions based solely on this one factor. There are nuances, and other taxes can often make up for the lack of income tax.
The Obvious Winners: Nine States with Zero Income Tax
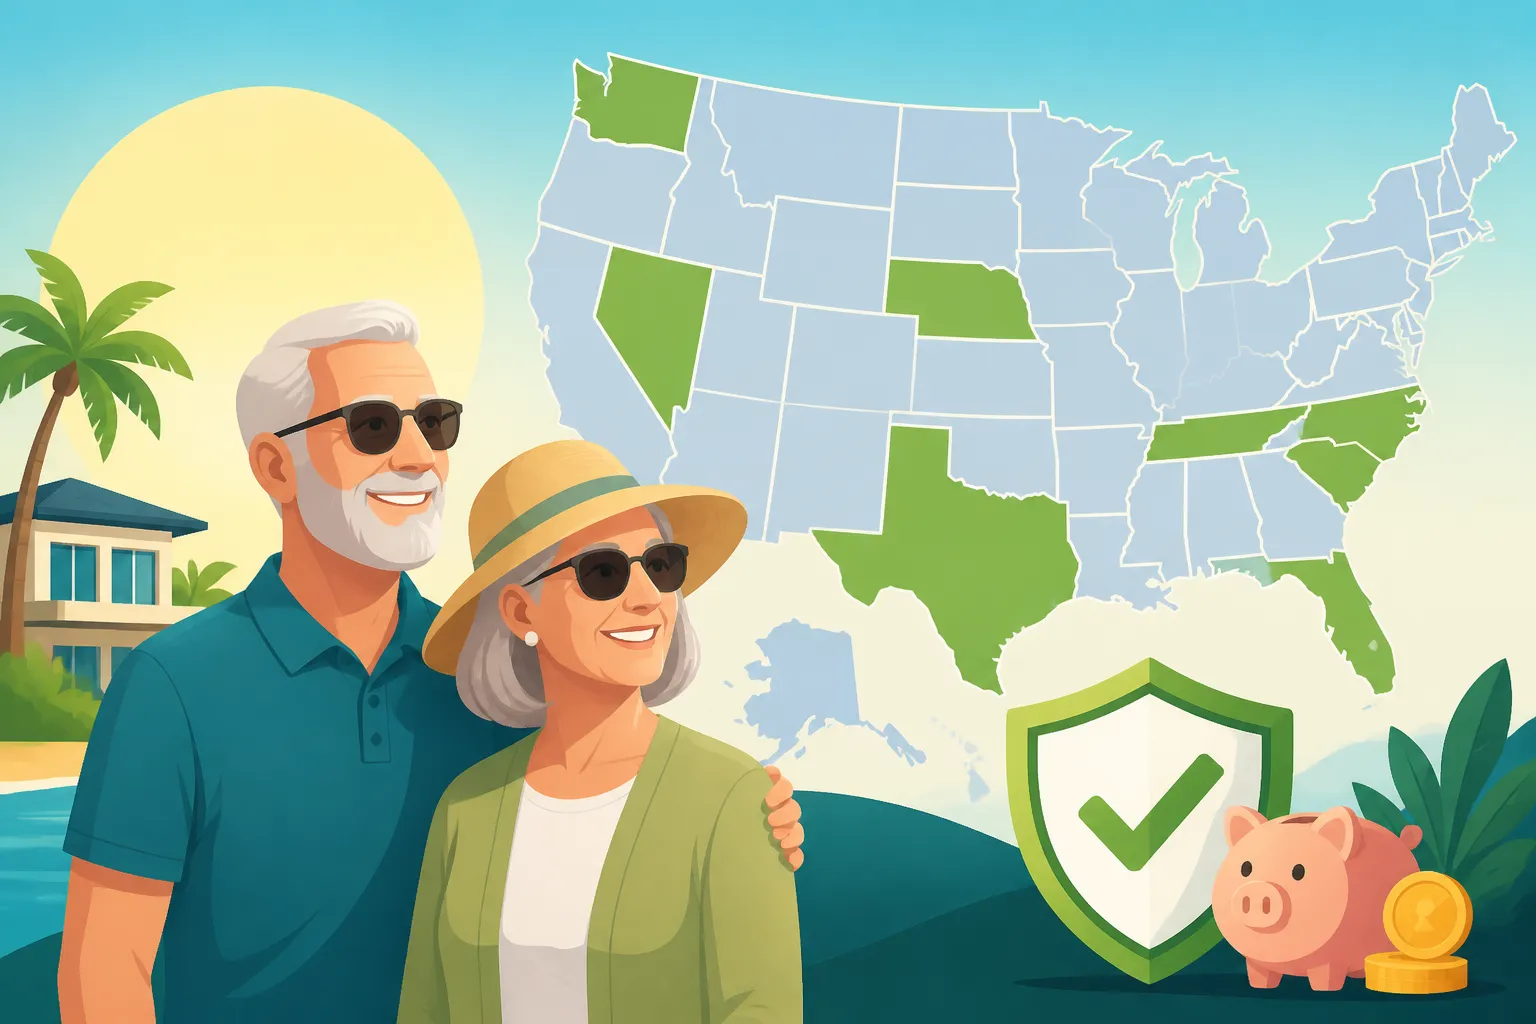
There are nine states that currently stand out as having no broad-based state income tax. These states are Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. For retirees, this is a significant advantage, as it means their Social Security benefits, pension income, and withdrawals from 401(k)s and IRAs are generally not subject to state income taxation. This can translate to substantial savings, especially for those with sizable retirement accounts or pensions.
However, it's crucial to note a couple of exceptions and details within this list. New Hampshire, for instance, famously doesn't tax earned income, but it does tax interest and dividend income above a certain threshold, though this is being phased out. On the other hand, Washington State recently introduced a capital gains tax, which could affect certain high-net-worth retirees who have significant gains from investments. Despite these specific points, the general rule holds: moving to one of these states can significantly reduce your state tax burden on most forms of retirement income, offering a powerful incentive for many. For a comprehensive overview, you might want to explore the list of States With No Income Tax (2026 Full List).
Beyond the Income Tax: Other Tax Burdens to Consider
While "no income tax" sounds incredibly appealing, it's not the whole story. States need revenue, and if they're not getting it from income taxes, they're typically making it up elsewhere. This often comes in the form of higher property taxes, higher sales taxes, or even excise taxes on specific goods and services. For retirees, especially those on fixed incomes, these other taxes can quickly erode the savings gained from not paying state income tax.
Consider Texas, a popular destination for retirees. While it boasts no state income tax, its property taxes are among the highest in the nation. If you own a home, this could mean a significant annual outflow. Similarly, Florida, another no-income-tax state, has relatively high sales taxes and can have elevated property insurance costs due to its susceptibility to natural disasters. On the flip side, states like Alaska might have no income tax and no state sales tax, but the high cost of living for goods and services can offset those benefits. It's a careful balancing act, and what looks good on paper for income tax might be less attractive when you factor in your daily expenses and property ownership. This is where tools from financial platforms like SmartAsset can really come in handy, allowing you to compare the overall tax burden in different locations.
States That Don't Tax Social Security Benefits
For most retirees, Social Security benefits are a foundational element of their financial security. Whether or not these benefits are subject to state income tax can make a substantial difference in their take-home income. The good news is that the vast majority of states recognize the importance of these benefits and offer full or partial exemptions.
A Major Relief: States Exempting Social Security
It's a huge relief for many to learn that a large number of states choose not to tax Social Security benefits at all. As of 2026, over 30 states have policies in place that fully exempt Social Security benefits from state income tax. This means that for retirees living in these states, the Social Security income they receive is entirely theirs, free from any state-level deductions. This policy is particularly beneficial for those for whom Social Security represents a significant portion of their retirement income, as it protects a vital financial safety net.
This exemption often reflects a state's broader commitment to making retirement more affordable for its senior residents. When you combine this with other potential exemptions or low overall income tax rates, these states become incredibly attractive. It's not just about the absolute amount, but the principle of preserving those benefits that many have contributed to throughout their working lives. For those exploring their options, knowing which states provide this full exemption is a critical piece of information. You can find a detailed breakdown in our article on States That Don't Tax Social Security (2027).
The Exceptions: States That Still Tax Social Security
While most states offer a reprieve, there are still a handful that choose to tax Social Security benefits. States like Colorado, Connecticut, Kansas, Minnesota, Missouri, Montana, Nebraska, New Mexico, Rhode Island, Utah, Vermont, and West Virginia still tax Social Security income to some degree. However, it’s not always a straightforward tax on every dollar. Many of these states have specific income thresholds or sliding scales that determine how much, if any, of your Social Security benefits will be taxed.
For instance, a state might only tax Social Security benefits if your Adjusted Gross Income (AGI) exceeds a certain amount, or they might allow a significant deduction, effectively exempting lower and middle-income retirees. For example, states like Missouri and Nebraska have recently enacted legislation to phase out or repeal their Social Security taxes, showing a trend towards greater tax-friendliness for retirees. This means the rules can change, so staying up-to-date is crucial. Always check the specific rules for the state you’re considering, as the devil is often in the details when it comes to these exemptions. A financial planner or a detailed resource like SmartAsset can help you understand the nuances of these specific state tax codes. For more on this, check out The 8 States That Still Tax Social Security.
States That Are Friendly to Pensions and Retirement Account Withdrawals
Beyond Social Security, pensions and withdrawals from traditional retirement accounts like 401(k)s and IRAs constitute a large part of many retirees' income. The state-level taxation of these income sources varies widely, making it a critical factor in determining a state's overall tax-friendliness for seniors. Some states offer generous exemptions, while others tax these distributions much like any other income.
Pension and 401(k)/IRA Exemptions: A State-by-State Look
How states treat pension income and withdrawals from your 401(k) or IRA can be a major deciding factor for retirees. Many states offer full or partial exemptions, or significant deductions for these types of income. For example, states like Illinois and Pennsylvania are known for their broad exemptions, allowing residents to generally exclude pension and retirement account income from state taxation. This is a huge benefit, especially for those who have substantial amounts saved in these vehicles.
Other states might offer a more nuanced approach. Some states provide age-based exemptions, where retirees over a certain age can exclude a set amount of their retirement income. Others might have income thresholds, meaning that only those above a certain income level will see their pensions or withdrawals taxed. Then there are states that simply tax these distributions as ordinary income, offering little to no special treatment. It’s important to research the specific rules for each state you’re considering, as a blanket assumption could lead to an unpleasant surprise. Tools and guides that offer a How Each State Taxes Retirement Income (50-State Guide) can be invaluable here.
Military Retirement and Government Pensions
Military retirees and former government employees often have unique pension situations, and states frequently recognize this with special tax benefits. A significant number of states offer full exemptions for military retirement pay. This is a deliberate policy choice by many states to honor veterans and attract retired military personnel. For example, states like Alabama, Arizona, and North Carolina provide full exemptions for military retirement income, making them particularly appealing for those who served.
Similarly, state and local government pensions can also receive preferential tax treatment in some states. While not as universally exempt as military pensions, many states offer specific deductions or exclusions for these income streams. It's common for states to offer a certain dollar amount exclusion for public pensions, or to completely exempt them from taxation. These exemptions can be a significant boost to a retiree's income, especially if their pension is their primary source of funds. If you’re a military or government retiree, investigating these specific exemptions should be high on your priority list when considering a move. Our resource on Military Retirement Tax by State (Full List) can help you drill down into these specific rules.
The "Most Tax-Friendly" Contenders: Deep Dive
When we talk about the "most tax-friendly" states for retirees, we're not just looking at one type of tax. It's a combination of factors: how they treat income, property, and sales. A truly friendly state minimizes the overall burden across the board, allowing retirees to maximize their savings and enjoy their post-career years without undue financial stress.
Top Tier: States with Broad Exemptions
Some states consistently rank at the top for retirees due to their broad-based exemptions across various income types. These are the states that don't just avoid income tax, but also offer a generally low-tax environment or specific benefits for seniors.
Florida is often cited as a prime example. As one of the States With No Income Tax (2026 Full List), it immediately exempts all types of retirement income from state taxation, including Social Security, pensions, 401(k)s, and IRAs. While Florida does have a 6% sales tax and property taxes can be a factor, the homestead exemption can provide some relief for homeowners. The lack of income tax makes it incredibly attractive for those living off their retirement savings.
Nevada is another strong contender. Like Florida, Nevada has no state income tax, meaning all retirement income is exempt. It also boasts no inheritance or estate tax. While sales tax is a bit higher (6.85% state rate, with local taxes pushing it up), and property taxes are moderate, the overall absence of income tax makes it very appealing. The vibrant lifestyle options in places like Las Vegas and Reno, combined with tax advantages, draw many retirees.
Wyoming rounds out this top tier. With no state income tax, no inheritance tax, and no estate tax, Wyoming offers a robust tax-friendly environment. Sales tax is a manageable 4% statewide, though local taxes can add more. Property taxes are also quite low compared to the national average. The stunning natural beauty and lower population density make it an attractive option for those seeking tranquility alongside tax benefits. These states offer a compelling package for retirees looking to keep more of their money.
Emerging Favorites: States Making Improvements
The tax landscape for retirees isn't static. States are constantly evaluating their tax policies, and some are making significant strides to become more attractive to seniors. This can involve phasing out certain taxes, introducing new exemptions, or lowering overall rates. Keeping an eye on these emerging favorites is important, as they might offer a better fit for your specific needs in the coming years.
Pennsylvania has long been considered quite tax-friendly for retirees, but it continues to refine its policies. It's noteworthy for generally exempting most retirement income, including Social Security, eligible pensions, and distributions from 401(k)s and IRAs, for those over age 59 1/2. While it has a flat income tax rate, the broad exemptions for retirement income make it highly competitive. It also doesn't have an inheritance tax on transfers to spouses, children, or grandchildren, which is a significant benefit for estate planning.
Michigan is another state that has been making moves to enhance its tax-friendliness for retirees. The state is currently phasing out its tax on pension income. While the exact details depend on birth year and type of pension, by 2026, most retirement income will see significant exemptions or complete tax relief for many seniors. This is a substantial change that positions Michigan more favorably compared to its past tax structure.
Georgia has also gained attention for its generous retirement income exclusion. For those aged 65 or older, a large portion of retirement income, including income from pensions, annuities, interest, dividends, and capital gains, is exempt up to a certain high threshold (currently $65,000 per person). This means that for many retirees, a significant chunk of their income will be completely tax-free at the state level. These states demonstrate that even those with an income tax can be incredibly friendly to retirees through targeted exemptions and deductions, proving that a deeper dive beyond the "no income tax" headline is always warranted.
Factors Beyond Income Tax: A Holistic View
While income tax is often the first thing retirees consider, a truly tax-friendly state offers a holistic advantage. Overlooking other tax burdens can lead to an incomplete and potentially misleading picture of your actual cost of living. To make an informed decision, you need to consider property taxes, sales taxes, and even less common levies like estate or inheritance taxes.
Property Taxes and Homestead Exemptions
Property taxes are a substantial expense for most homeowners, and they vary dramatically from state to state, and even county to county. For retirees on a fixed income, a high property tax bill can quickly negate any savings from low or no income taxes. For example, while New Hampshire doesn't have an income tax, it consistently ranks among the states with the highest property tax rates in the nation. This means a homeowner there could end up paying more in property taxes than they would in income tax in another state.
However, many states offer relief in the form of homestead exemptions or property tax credits specifically for seniors or low-income residents. A homestead exemption reduces the taxable value of your primary residence, lowering your property tax bill. For instance, Florida, despite being a no-income-tax state, offers a generous homestead exemption that can significantly reduce the taxable value of a primary home. Texas also provides various homestead exemptions, including a substantial one for seniors. Looking into Property Tax Credits & Homestead Exemptions by State is crucial to understand the true cost of homeownership in your potential retirement haven. Don't just look at the average rate; investigate how these exemptions might apply to your specific situation.
Sales Taxes, Estate Taxes, and Other Considerations
Beyond income and property taxes, sales taxes impact your daily expenses. Almost every state has a sales tax, though rates vary from zero (in states like Delaware, Montana, New Hampshire, and Oregon) to over 7% at the state level, with local taxes often pushing the combined rate much higher. For retirees, who often spend less on housing and more on consumables and services, high sales taxes can add up. Some states, however, exempt necessities like groceries or prescription medications, which can mitigate the impact for seniors.
Then there are estate taxes and inheritance taxes, which can affect your heirs. Most states do not levy these taxes, but a handful do, including states like New York, New Jersey, and Pennsylvania. If leaving a legacy is important to you, and your estate is substantial, these taxes could be a significant factor. While not a recurring annual cost for retirees themselves, they are a vital component of holistic financial planning. Additionally, don't forget less common taxes like vehicle registration fees or excise taxes on fuel or utilities, which can also contribute to the overall cost of living. Understanding the full picture of a state's tax burden, beyond just income, provides a truly comprehensive view of its financial friendliness for your retirement years.
| Tax Category | Florida | Nevada | Pennsylvania | Texas | New Hampshire |
|---|---|---|---|---|---|
| State Income Tax | None | None | Flat (3.07%) | None | None (Int/Div) |
| Social Security Tax | None | None | None | None | None |
| Pension/401(k) Tax | None | None | None (Qualifying) | None | None (Phasing Out Int/Div) |
| State Sales Tax Rate | 6% | 6.85% | 6% | 6.25% | None |
| Avg. Property Tax Rate | Moderate (0.83%) | Moderate (0.53%) | High (1.43%) | Very High (1.68%) | Very High (1.89%) |
| Estate/Inheritance Tax | None | None | Inheritance only | None | None |
Note: Property tax rates are averages and can vary significantly by county. Sales tax rates do not include local additions.
Planning Your Retirement Move: Practical Steps
Deciding to move for retirement, especially across state lines, is a huge undertaking with many moving parts. Beyond the taxes, there are logistics, emotional considerations, and a myriad of details to handle. But when it comes to taxes, proper planning is absolutely crucial. A haphazard move could leave you unintentionally subject to taxes in two states, or worse, trigger a residency audit.
Residency Rules and Domicile Establishment
One of the most critical aspects of moving for tax purposes is officially establishing your new state residency and domicile. Many people think simply owning a second home or spending "most of the year" in a state is enough, but states have very specific rules about what constitutes a legal resident for tax purposes. Your domicile is your true, fixed, and permanent home – the place where you intend to return whenever you are absent. Changing your domicile isn't just about packing your bags; it involves a series of deliberate actions to demonstrate your intent to your new state and, importantly, to your old one.
This typically includes updating your driver's license, registering your car, registering to vote, moving your bank accounts, closing utility accounts in your old state, and severing ties like club memberships. States like California and New York, known for their rigorous residency audits, expect to see clear, consistent proof that you've genuinely moved and have no intention of returning permanently. Without establishing a clear change in domicile, you could find yourself in a dual residency situation, potentially owing taxes in both your old and new states. For a deep dive into this topic, refer to our guide on State Tax Residency Rules Explained and How to Change Your State Residency for Taxes.
Consulting Financial Experts and Utilizing Tools
Navigating the complexities of state tax residency and retirement income can be overwhelming, even for the most financially savvy individuals. This is precisely why consulting with a qualified financial advisor or a tax professional specializing in multi-state taxation is highly recommended. These experts can help you analyze your unique income streams, assess your assets, and project your potential tax burden in different states. They can also provide guidance on the specific steps needed to legally establish domicile and sever ties with your previous state, minimizing the risk of residency audits.
Beyond professional advice, utilizing online financial planning tools can be incredibly helpful. Platforms like SmartAsset offer valuable resources, including calculators and state-by-state comparisons of retirement taxes, property taxes, and overall cost of living. These tools can give you a quick snapshot and help you narrow down your options before seeking personalized advice. Remember, your retirement finances are unique, and a one-size-fits-all approach rarely works. A combination of expert advice and robust tools will ensure you make the most informed decision for your golden years.
Real-World Scenarios and Case Studies
Understanding tax rules in theory is one thing, but seeing how they apply to real-world situations can truly bring the concepts to life. Retirees come in all shapes and sizes, with different income profiles, assets, and lifestyle preferences. Let's explore a couple of common scenarios to illustrate how state tax friendliness can play out for various individuals.
The Snowbird Dilemma: Dual Residency Challenges
Imagine Sarah and John, a couple from New York, who dream of escaping the harsh winters. They decide to buy a small condo in Florida, spending six months there and six months back in their New York home. This is the classic "snowbird" scenario, and it can quickly become a dual residency tax challenge. New York is known for its aggressive approach to statutory residency, meaning if you maintain a permanent place of abode there and spend more than 183 days in the state, you could be considered a New York resident for tax purposes, even if you claim Florida as your domicile.
In this situation, Sarah and John would need to be meticulously careful about tracking their days in each state. If New York successfully argues they are statutory residents, they could be taxed on all their income, including pensions and 401(k) withdrawals, by New York, even if that income was earned or received while they were in Florida. While Florida has no state income tax, the goal is to avoid New York's substantial tax bite. To truly avoid New York taxes, they would need to establish clear Florida domicile, spend less than 183 days in New York, and sever as many ties as possible with their old state. Without careful planning, their dream of a tax-friendly Florida retirement could be overshadowed by New York's tax demands, highlighting the importance of understanding Snowbird & Dual-Residency Taxes.
Hypothetical Retiree Profiles and Best State Matches
Let's consider two different hypothetical retirees:
Scenario 1: The Pensioner
Meet Margaret, a retired public school teacher from Illinois, who receives a substantial pension ($80,000 annually) and modest Social Security benefits ($25,000). She also has a small IRA she'll start drawing from later. For Margaret, states that exempt pensions are paramount.
- Best Match: Illinois, her home state, actually exempts qualified pension income from state income tax, making it surprisingly tax-friendly for pensioners like her. She also wouldn't pay state tax on her Social Security. If she wanted a change of scenery, states like Pennsylvania or Mississippi also offer broad exemptions for pension income. Even though Pennsylvania has a flat income tax, its generous exemptions for retirement income would make it a strong contender for Margaret.
Scenario 2: The Investment-Savvy Retiree
Now consider David, who retired early with a significant nest egg in a 401(k) and a portfolio of investments generating substantial capital gains and dividends. He doesn't have a traditional pension but will be drawing heavily from his 401(k) and living off his investment income. His Social Security benefits are also significant.
- Best Match: David would strongly favor states with no state income tax, as this would shield his 401(k) withdrawals, capital gains, and dividends from state taxes. States like Florida, Nevada, or Texas would be ideal. Even though Washington State has no income tax, its relatively new capital gains tax might give David pause, depending on the volume of his realized gains. For David, avoiding income tax on his diverse investment and retirement account income is the top priority, making the no-income-tax states shine brightest.
These scenarios illustrate that the "most tax-friendly" state isn't a one-size-fits-all answer. It truly depends on your specific income sources, assets, and personal situation.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change. It is essential to consult with a qualified financial advisor, tax professional, or attorney for advice tailored to your individual circumstances.