States That Don’t Tax Military Retirement
One of the most pressing concerns for military retirees, after dedicating years of service to our country, is understanding how their hard-earned retirement income will be treated when it comes to state taxes. It's a frustrating maze to navigate, with each state seemingly having its own unique rulebook, leaving many feeling uncertain about where they can truly make their retirement savings stretch furthest. This comprehensive guide aims to unravel that complexity, detailing which states offer full or partial exemptions on military retirement pay, and what other factors you should consider when planning your post-service life.
Understanding State Taxation of Military Retirement Income
When you transition from active duty to retirement, your military pension becomes a significant part of your income. However, unlike your federal taxes, which are pretty uniform across the board, state taxes on this income can vary wildly. This isn't just a minor detail; it can significantly impact your disposable income and overall financial well-being in retirement.
Why State Taxes Matter for Military Retirees
For many military families, the idea of settling down in a place where their military retirement income won't be chipped away by state taxes is incredibly appealing. Think about it: an extra few hundred or even thousand dollars a year can make a huge difference in your budget, whether it's for healthcare costs, travel, or simply enjoying your well-deserved free time. For example, if you're receiving a $50,000 annual military pension, and your state taxes it at a 5% rate, that's $2,500 gone right off the top. Over a decade, that's $25,000! That's why understanding these nuances is critical, especially when comparing potential retirement destinations. It's not just about the upfront tax rate, but the cumulative effect over years that truly matters.
General Approaches to Taxing Military Retirement
States generally take one of three approaches when it comes to military retirement income:
- Full Exemption: These are the states that completely exempt all military retirement pay from state income taxes. This is often the holy grail for many military retirees, offering the most significant tax savings.
- Partial Exemption: Many states offer some form of exemption, but it might be capped at a certain dollar amount, apply only after a certain age, or depend on your total adjusted gross income. These can still offer substantial relief but require careful calculation to understand the true benefit.
- Full Taxation: A smaller number of states treat military retirement pay just like any other form of income, taxing it according to their standard income tax brackets. Even in these states, general deductions or credits might apply, but there's no specific exemption for military retirement.
It's a dynamic landscape, too. States are constantly evaluating their tax policies to attract retirees, especially those with military backgrounds, recognizing the economic contributions these individuals bring. What might be fully taxed today could be partially or fully exempt tomorrow, or vice versa, so staying informed is crucial.
The Full Exemption Club: States That Don't Tax Military Retirement
For many, the dream is to settle in a state where every penny of their military pension is theirs to keep, free from state income tax. The good news is that a significant and growing number of states understand the value of military retirees and offer full exemptions on their retirement income.
A Growing Trend: States Eliminating the Tax
Over the past few years, we've seen a noticeable trend of states either introducing full exemptions for military retirement pay or expanding existing partial exemptions to full ones. This is often a strategic move by state legislatures to attract veterans and their families, recognizing the skilled workforce, community engagement, and economic stability they bring. Many states see it as a way to honor service while boosting local economies. For instance, states like West Virginia and Missouri have recently moved to eliminate or phase out taxes on military retirement income, making them much more attractive to veterans looking for a new home. This trend means that the list of tax-friendly states is not static, and it's always worth checking the latest legislative changes.
Specific Examples of Fully Exempt States
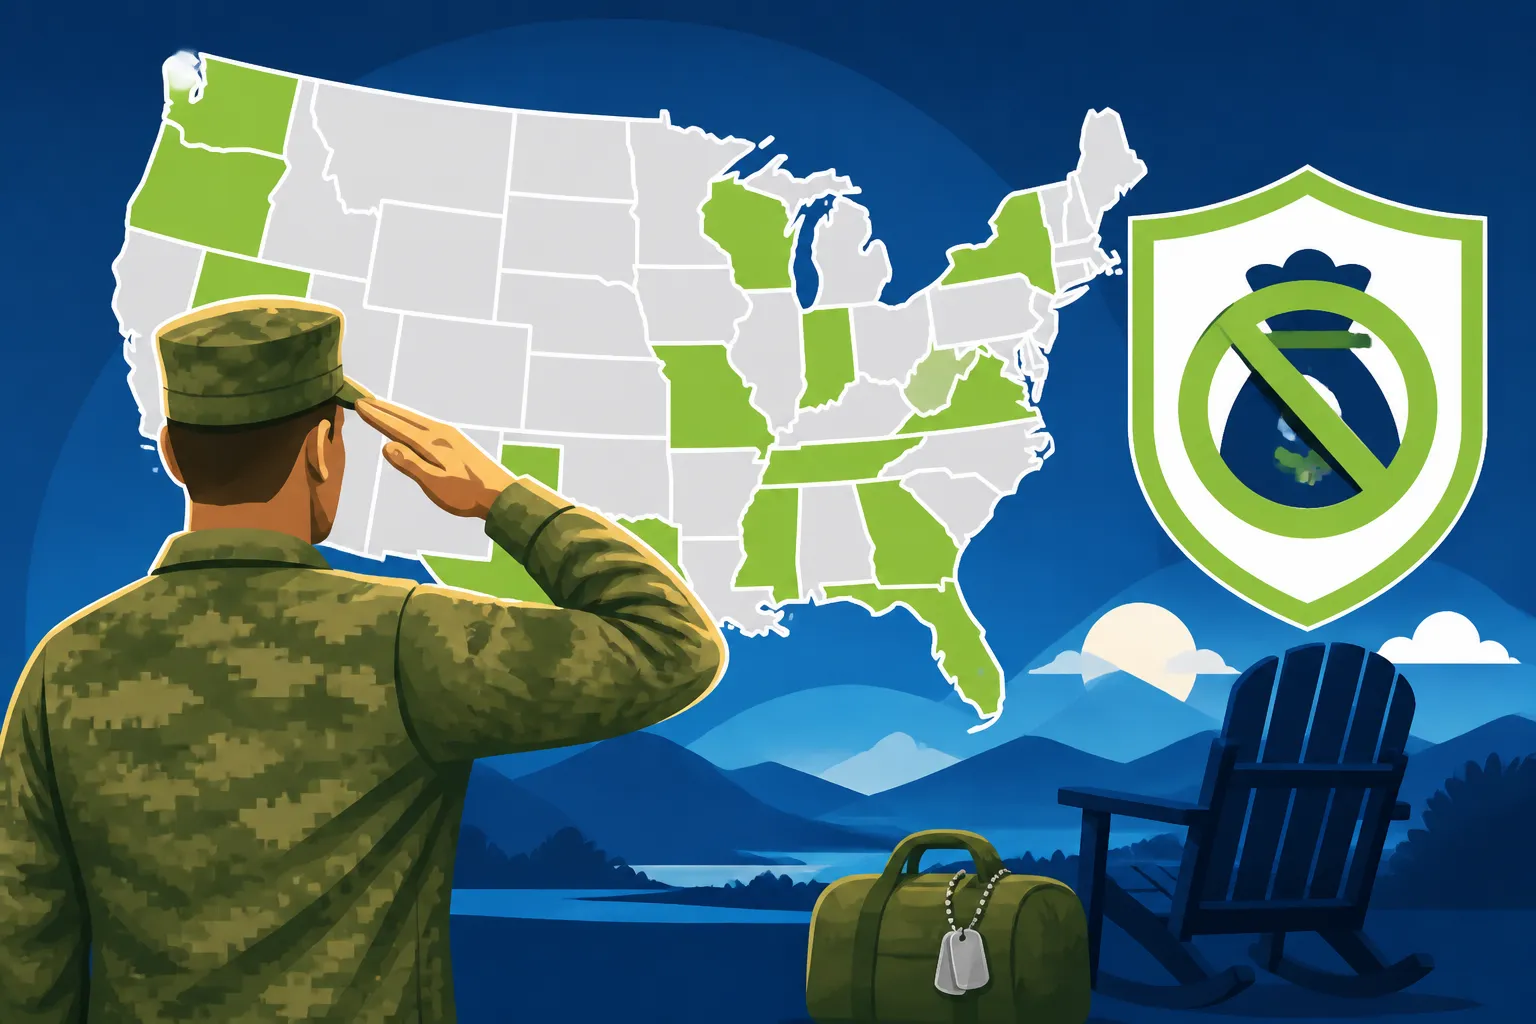
Many states offer a full exemption for military retirement income. This means if you establish residency in one of these places, your military pension will not be subject to state income tax. These states often become prime targets for retirees looking to maximize their income.
Here's a breakdown of some prominent states in the "full exemption club":
- Alabama: Fully exempts military retirement pay.
- Arizona: Fully exempts military retirement pay.
- Arkansas: Fully exempts military retirement pay.
- Florida: This is one of the States With No Income Tax (2026 Full List), so naturally, military retirement income is not taxed.
- Georgia: Fully exempts military retirement pay.
- Illinois: Fully exempts military retirement pay.
- Indiana: Fully exempts military retirement pay.
- Iowa: Fully exempts military retirement pay.
- Kansas: Fully exempts military retirement pay.
- Kentucky: Fully exempts military retirement pay.
- Louisiana: Fully exempts military retirement pay.
- Massachusetts: While having an income tax, it fully exempts military retirement pay.
- Michigan: Fully exempts military retirement pay.
- Minnesota: Fully exempts military retirement pay.
- Mississippi: Fully exempts military retirement pay.
- Missouri: Has moved to fully exempt military retirement pay.
- Montana: Fully exempts military retirement pay.
- Nevada: Another state with no income tax, thus no tax on military retirement.
- New Hampshire: Only taxes interest and dividends, not earned income or retirement pay.
- New Jersey: Fully exempts military retirement pay as of recent changes.
- New York: Fully exempts military retirement pay for those meeting specific criteria (e.g., age 55 or older, or specific military service dates).
- North Carolina: Fully exempts military retirement pay.
- North Dakota: Fully exempts military retirement pay.
- Ohio: Fully exempts military retirement pay.
- Oklahoma: Fully exempts military retirement pay.
- Pennsylvania: Fully exempts all retirement income, including military pensions.
- South Carolina: Fully exempts military retirement pay.
- South Dakota: No income tax state.
- Tennessee: No income tax on wages, and has phased out taxes on interest and dividends.
- Texas: No income tax state.
- Utah: Fully exempts military retirement pay.
- Vermont: Fully exempts military retirement pay.
- Virginia: Fully exempts military retirement pay.
- Washington: No income tax, though it does have a capital gains tax.
- West Virginia: Fully exempts military retirement pay.
- Wisconsin: Fully exempts military retirement pay.
- Wyoming: No income tax state.
This robust list illustrates the wide array of options available to military retirees seeking a tax-friendly home. However, remember that tax laws can change, so always verify the latest information from official state sources or a qualified tax professional before making a significant move. You can often find detailed breakdowns of these policies, along with other financial tools, from resources like SmartAsset, which compiles extensive state-by-state tax information for retirees.
States with Partial Exemptions or Specific Conditions
While a full exemption is ideal, many states offer significant tax relief through partial exemptions or specific conditions that can still make them very attractive. These often require a bit more homework to determine the exact benefit but can still lead to substantial savings.
Age, Income, or Service-Based Exemptions
Some states don't offer a blanket full exemption but instead provide relief based on certain criteria. These can include:
- Age: An exemption might kick in once you reach a certain age, often 55, 60, or 65. For example, a state might exempt the first $10,000 of military retirement income for those under 65, and then increase that exemption significantly or fully exempt it once you hit 65. This is designed to provide greater relief as retirees get older and potentially have fixed incomes or higher healthcare costs.
- Income Level: The exemption might be tied to your overall adjusted gross income. If your total income falls below a certain threshold, a larger portion or even all of your military retirement might be exempt. Conversely, higher earners might see their exemption reduced or phased out entirely. This aims to provide tax relief to those who need it most.
- Years of Service or Combat Status: Less common, but some states might offer enhanced exemptions for those with a certain number of years of service or who served in specific combat zones. This is a way to acknowledge particular sacrifices made during military careers.
- Specific Service Dates: Occasionally, states will offer exemptions that only apply to military members who served during specific periods or wars. This can be complex, as it might exclude newer retirees.
For example, a state like Colorado offers a retirement income subtraction that includes military pensions, but it's limited to a certain amount ($24,000 for those 65 or older, and $20,000 for those 55-64). This isn't a full exemption, but it significantly reduces the taxable portion of your military retirement. Similarly, states like Maryland offer substantial exclusions for military retirement income, which can reduce your taxable income by a considerable amount, but generally don't fully exempt it for all retirees. It's vital to look into the specifics of these rules, as they can differ greatly.
How Partial Exemptions Work in Practice
Navigating partial exemptions requires a careful look at the state's tax code. It's not as straightforward as a "no tax" state, but the benefits can still be substantial. Here’s a typical scenario:
Imagine you retire from the military at age 50 and move to a state that exempts up to $15,000 of military retirement income annually for those under 65. If your annual military pension is $40,000, you would only pay state income tax on $25,000 of that income ($40,000 – $15,000). While you're still paying some tax, it's significantly less than if there were no exemption at all. Once you turn 65, that exemption might jump to $30,000 or become a full exemption, further reducing your tax liability.
These partial exemptions often interact with other state tax benefits, such as general retirement income exclusions or standard deductions. It's important to understand how these different pieces fit together. For instance, some states might have a blanket retirement income exclusion that applies to all types of pensions, including military, up to a certain dollar amount. You might find that by combining these, your effective taxable income is very low, even if the state doesn't offer a specific full military retirement exemption. Tools from financial analysis sites like SmartAsset can help you compare these complex scenarios, allowing you to estimate your tax burden in different states. Looking at resources like the Military Retirement Tax by State (Full List) can give you a better idea of how these different states compare.
States That Still Tax Military Retirement Income
While the trend is definitely leaning towards states becoming more tax-friendly for military retirees, there are still a handful that treat military retirement income like any other taxable income. It's crucial to be aware of these states, especially if you have strong ties to them or are considering moving there for other reasons.
Understanding the Tax Burden
In states that fully tax military retirement income, your pension will be subject to the same income tax rates and rules as regular wages or other taxable retirement distributions. This means that if the state has a progressive tax structure, your military pension will be taxed at the applicable rates based on your income level. If it's a flat tax state, it will be taxed at that single rate.
For instance, consider California, a state with a high cost of living and progressive income tax rates. While it's a popular state for its climate and opportunities, it does not offer a specific exemption for military retirement pay. If you receive a $60,000 military pension and live in California, that entire $60,000 would be subject to state income tax, in addition to any other taxable income you might have. This can significantly impact your financial planning compared to living in a state like Florida, which has No Income Tax. You can read more about how California taxes retirees in posts such as Does California Tax Retirement Income?.
Another example is Connecticut, which also generally taxes military retirement income according to its progressive income tax system, although it does offer some minor relief for lower-income retirees. The lack of a specific or substantial exemption means that your military retirement can face a considerable state tax burden, making it less attractive from a purely tax perspective. These states often have other compelling factors that draw residents, like strong job markets, unique cultural attractions, or family ties, but from a tax efficiency standpoint for military retirees, they present a challenge.
States to Watch for Future Changes
The landscape of state tax laws is constantly evolving. What is true today might not be true tomorrow. States are always looking at ways to attract or retain residents, and tax incentives for military retirees are a popular tool.
States like Rhode Island and Nebraska, for example, have made significant strides in recent years towards reducing or eliminating taxes on all retirement income, which indirectly benefits military retirees. While they might not yet offer a full, specific exemption for military pensions, their broader retirement income exclusions could provide substantial relief. It's always a good idea to monitor legislative changes in these states. A good resource for tracking these changes is often available through government finance departments or non-partisan research groups that analyze tax policy trends. Staying updated with State Income Tax Cuts & Changes for 2026 can help you identify states that might become more military-retirement-friendly in the near future.
It’s worth noting that even in states that tax military retirement, there are often broader deductions or credits available to all taxpayers that can reduce your overall tax burden. These could include standard deductions, deductions for medical expenses, or various credits. Therefore, it's essential to consider the full picture of the state's tax system, not just the military retirement exemption, when evaluating its friendliness towards retirees.
Beyond Income Tax: Other Tax Considerations for Military Retirees
Focusing solely on income tax for military retirement is a common mistake. While crucial, it's just one piece of the larger financial puzzle. When considering where to settle, military retirees need to look at the total tax burden, which includes property taxes, sales taxes, and potentially other levies that can eat into their retirement savings. A state with no income tax might have significantly higher property taxes, for example, making it less "tax-friendly" than initially perceived.
Property Taxes and Homestead Exemptions
Property taxes can be one of the largest ongoing expenses for homeowners, especially if you plan to buy a home in retirement. These taxes are locally assessed, meaning they vary not just by state, but often by county, city, and even school district within a state. A state renowned for low income tax might have incredibly high property taxes, effectively negating any income tax savings. For example, states like New Hampshire, which doesn't tax income, are known for having some of the highest property taxes in the nation. This can be a significant drain on a fixed retirement income.
Many states, however, offer homestead exemptions or other property tax relief programs specifically for veterans, disabled veterans, or seniors. These exemptions reduce the taxable value of your home, thereby lowering your property tax bill. For instance, in states like Florida, a common destination for retirees, qualifying veterans can receive significant property tax exemptions, which can be a huge benefit for homeowners. Even in states that tax military retirement, generous property tax exemptions could make them more appealing overall. It's vital to research these programs in any state you're considering. For a comprehensive overview, checking out resources like Property Tax Credits & Homestead Exemptions by State is highly recommended.
Sales, Estate, and Other State-Level Taxes
Beyond income and property taxes, several other state-level taxes can impact your retirement budget:
- Sales Tax: Almost all states levy a sales tax on goods and services. Some states have higher rates than others, and some even include groceries or certain services, which can add up over time. If you plan to spend a lot on consumer goods or dine out frequently, a high sales tax state might be more expensive than one with a lower rate.
- Estate Tax/Inheritance Tax: While less common, a few states impose estate taxes (tax on the value of a deceased person's property before distribution) or inheritance taxes (tax on what beneficiaries receive). If legacy planning is important to you, and you have substantial assets, these taxes could be a concern.
- Excise Taxes: These are taxes on specific goods like gasoline, tobacco, and alcohol. While they might seem minor, they can contribute to the overall cost of living, especially for certain lifestyles.
- Vehicle Registration Fees: Some states have significantly higher annual vehicle registration fees or personal property taxes on vehicles, which can be another hidden cost.
When evaluating states, it’s not just about the state income tax on your pension. It’s about the full picture – what you'll pay in property taxes, how much you’ll spend on sales tax, and if there are any other unique state or local taxes that will impact your bottom line. For instance, while states like Washington and Texas have no state income tax, they often rely more heavily on sales and property taxes. To truly understand your overall tax burden, you might use a tool like SmartAsset's tax calculator, which often incorporates various state-level taxes to give a more holistic view of the Cost of Living vs Taxes by State.
Making an Informed Decision: Factors Beyond Just Taxes
While tax implications are a huge piece of the puzzle for military retirees, they shouldn't be the only factor driving your relocation decision. A low-tax state might not be the best fit if it lacks other amenities important to your quality of life. It’s about finding the right balance between financial advantages and personal preferences.
Cost of Living and Quality of Life
A state might boast no income tax on military retirement, but if the overall cost of living is exceptionally high, those tax savings could be quickly eroded. For example, while states like Washington have no state income tax, areas around Seattle have some of the highest housing costs in the nation. Conversely, a state with a modest income tax might have a much lower cost of housing, groceries, and utilities, making your retirement income go further overall.
Consider these aspects of the cost of living:
- Housing: This is usually the biggest expense. Research median home prices and rental costs in areas you're considering.
- Utilities: Energy costs (electricity, gas, water) can vary dramatically by climate and state.
- Groceries: Even small differences in food prices can add up over a year.
- Transportation: Gas prices, car insurance, and public transport options are important.
- Healthcare: Access to quality healthcare and its associated costs (even with Tricare or other insurance) can differ widely.
Beyond cost, think about your desired quality of life. Do you want access to cultural events, outdoor activities, or a specific climate? Is a vibrant community important to you, or do you prefer quiet solitude? Would you like to be near family or old friends? What about educational opportunities or volunteer work? A state like New York might have some income taxes, but if being near Broadway shows and world-class museums is a priority, the trade-off might be worth it. Ultimately, the "best" state is subjective and depends on your individual priorities and lifestyle preferences.
Proximity to Military Facilities and Healthcare
For many military retirees, maintaining connections to the military community and accessing specialized healthcare are high priorities. This often means living near military bases, VA hospitals, or other veteran support services.
- VA Facilities: Access to high-quality Veterans Affairs (VA) hospitals and clinics is a major consideration. Some states have extensive VA networks, while others have fewer facilities, potentially requiring longer travel times for appointments or specialized care.
- Military Bases: Living near an active military installation can offer access to commissaries, exchanges, MWR (Morale, Welfare, and Recreation) facilities, and a sense of community with other service members and veterans. These benefits, while not direct tax savings, represent significant value and convenience. For example, if you're accustomed to shopping at the commissary for groceries, the savings can be substantial, effectively boosting your purchasing power.
- Veteran Support Services: Beyond healthcare, many states and local communities offer a wide range of services specifically for veterans, including employment assistance, legal aid, mental health support, and social programs. These networks can be invaluable for navigating post-military life.
For example, a state like Texas, which has no income tax and a relatively low cost of living, also boasts numerous military installations and VA facilities, making it a popular choice for many veterans. When you factor in these non-monetary benefits, a state that might seem slightly less appealing from a pure income tax perspective could become a frontrunner. It's about looking at the entire package of what a state offers to retirees and veterans. This is why many retirees look for the Most Tax-Friendly States for Retirees 2027 that also align with their lifestyle preferences.
Navigating Residency for Tax Purposes
One of the most complex aspects of state taxation for military retirees, especially if you move frequently or maintain multiple residences, is establishing and proving your state of residency or "domicile." This isn't just a casual declaration; it involves demonstrating genuine intent to make a particular state your permanent home, and states are increasingly scrutinizing these claims.
Establishing Domicile When Moving
Your "domicile" is your true, fixed, and permanent home, the place where you intend to return whenever you are absent. For tax purposes, your domicile is the state where you pay your state income taxes (if applicable) and where you claim residency. When you move, especially from a high-tax state to a low- or no-tax state, the former state might try to argue you haven't truly changed your domicile to avoid paying taxes. This can lead to what's known as a "residency audit."
To effectively establish a new domicile, you need to sever ties with your old state and create clear connections to your new one. Here are some key steps:
- Change Voter Registration: Register to vote in your new state and cancel your old registration.
- Driver's License & Vehicle Registration: Obtain a new driver's license and register your vehicles in your new state.
- Bank Accounts: Open bank accounts in your new state and close accounts in your old state.
- Professional Licenses: If applicable, transfer professional licenses to your new state.
- Property Ownership: Sell your primary residence in the old state and purchase or rent a home in the new state, making it your primary residence.
- Mail Forwarding: Change your mailing address with the post office.
- Medical & Dental Providers: Establish new doctors and dentists in your new state.
- Social Connections: Join local clubs, churches, or community groups in your new state.
The more evidence you have of your intent to make the new state your permanent home, the stronger your case. Simply renting a P.O. Box in a new state while maintaining all other ties to your old state will likely not be enough to avoid an audit or maintain your claim. Understanding the difference between Domicile vs Statutory Residency is crucial here, as states have different tests. For detailed guidance on how to make this change, reading articles like How to Change Your State Residency for Taxes can be very helpful.
The Impact of the Military Spouse Residency Relief Act (MSRRA)
The Military Spouse Residency Relief Act (MSRRA) is a crucial piece of legislation that significantly impacts military families, including retirees and their spouses. Prior to MSRRA, military spouses often had to change their state of residency for tax purposes every time their service member spouse received Permanent Change of Station (PCS) orders, leading to complicated tax filings and potential double taxation.
MSRRA allows military spouses to maintain their original state of domicile (home of record) even if they move to a new state due to military orders. This means if a military spouse is domiciled in Texas (a no-income-tax state) and moves with their service member to California (a high-income-tax state), the spouse might not have to pay California income tax on wages earned in California, provided they meet the MSRRA requirements. This is a huge benefit for families, simplifying tax situations and potentially saving significant amounts in state income taxes.
For retirees, MSRRA continues to be relevant, particularly for those who retired and whose spouses are still working or for those considering establishing domicile in a specific state while their spouse maintains a different one. It's a complex area, and understanding how Working in One State, Living in Another: Tax Guide relates to MSRRA is essential. While MSRRA primarily addresses current service members and their spouses, the underlying principles of domicile and residency are paramount for all military retirees looking to optimize their state tax situation. It essentially provides a protective layer for spouses' state residency, allowing them to retain their chosen domicile for tax purposes regardless of where military orders send them.
Strategies for Minimizing Your State Tax Burden
Beyond choosing a tax-friendly state, there are proactive steps military retirees can take to further minimize their state tax obligations. These strategies involve understanding available tax breaks and planning your financial decisions carefully.
Utilizing Available Deductions and Credits
Even in states that do tax military retirement income, or for other forms of retirement income, there are often deductions and credits that can significantly reduce your taxable income or your tax liability. Don't overlook these!
- Standard vs. Itemized Deductions: Just like with federal taxes, states offer either a standard deduction or allow you to itemize deductions. Many states have their own unique standard deduction amounts, which might differ from the federal amounts. Some allow you to itemize even if you take the federal standard deduction. You might find state-specific deductions for things like property taxes paid (even if limited by the federal SALT cap, some states offer workarounds or additional deductions), medical expenses, or charitable contributions.
- Retirement Income Exclusions: Beyond military-specific exemptions, many states offer general exclusions for retirement income up to a certain amount. This can include pensions, annuities, 401(k) withdrawals, and IRA distributions. For example, some states have an exclusion for a certain amount of income for those over 65, regardless of its source.
- Credits for Taxes Paid to Another State: If you work in one state and live in another, or if you have income from sources in different states, you might be eligible for a credit for taxes paid to another state. This prevents you from being taxed twice on the same income. This is a common situation for remote workers or those who have part-time jobs across state lines. Understanding these credits is key to avoiding Dual State Residency: Can You Be Taxed Twice?.
- Specific Veteran Credits: Some states offer unique tax credits for veterans, such as credits for owning a small business, hiring veterans, or for specific disabilities. These credits directly reduce your tax bill, dollar-for-dollar.
It’s always worth exploring the full range of state deductions and credits available. What seems like a small deduction can add up, especially when combined with other tax-saving measures. Consulting with a tax professional who specializes in multi-state taxation or military retirement can provide tailored advice. Financial platforms like SmartAsset often have tools and articles dedicated to explaining these complex state-specific deductions, helping you effectively manage your State Income Tax vs Federal Income Tax situation.
Planning Your Retirement Location
The most effective strategy for minimizing state taxes on your military retirement income often comes down to careful planning of where you choose to live. This isn't just about picking any state that doesn't tax military pensions; it's about finding the state that best aligns with your overall financial and lifestyle goals.
- Consider a "No Income Tax" State: As discussed earlier, states like Florida, Texas, and Nevada don't have a state income tax at all, meaning your military retirement income, along with all other earned income, will be exempt by default. This simplifies things immensely, as you don't need to worry about specific military exemptions. However, remember to weigh this against other taxes like property and sales tax, and the general cost of living. For a full list, check out States With No Income Tax (2026 Full List).
- Research Specific Military Retirement Exemptions: If a no-income-tax state isn't for you, delve into the states that specifically offer full or substantial partial exemptions for military retirement pay. This list is growing, and these states are actively trying to attract veterans.
- Holistic Financial Review: Look at your entire financial picture. How much income will you have from your pension, Social Security, 401(k)/IRA withdrawals, and any part-time work? How will each of these be taxed in different states? Will you have significant property tax or sales tax expenses? Will you be taking advantage of Retirement Income Exclusions by State? A comprehensive review helps you compare apples to apples when considering different locations.
- Future Changes: Keep an eye on legislative changes. States like West Virginia have recently phased out taxes on military retirement, showing that the tax landscape can improve. What might not be the most tax-friendly state today could be a top contender in a few years.
Ultimately, your retirement location planning should be a deliberate process that takes into account not only the state's tax laws but also its economic environment, healthcare infrastructure, community for veterans, and personal preferences. By doing your homework and considering all these factors, you can make a choice that allows your military retirement income to go further and ensures a comfortable and fulfilling post-service life.
A Snapshot: Military Retirement Tax Status by State (2026)
To help visualize the landscape, here's a table summarizing the general status of military retirement income taxation across the U.S. Keep in mind that "partial" exemptions can vary greatly, and "no income tax" states also mean no tax on military retirement.
| State | Military Retirement Income Tax Status | Notes |
|---|---|---|
| Alabama | Fully Exempt | |
| Alaska | No State Income Tax | |
| Arizona | Fully Exempt | |
| Arkansas | Fully Exempt | |
| California | Fully Taxed | Does not offer specific exemption for military retirement income. |
| Colorado | Partial Exemption | Limited retirement income subtraction for those 55+. |
| Connecticut | Fully Taxed | No specific exemption for military retirement, though some general retirement income exclusions may apply for lower-income individuals. |
| Delaware | Fully Exempt | |
| Florida | No State Income Tax | |
| Georgia | Fully Exempt | |
| Hawaii | Fully Exempt | |
| Idaho | Fully Exempt | |
| Illinois | Fully Exempt | |
| Indiana | Fully Exempt | |
| Iowa | Fully Exempt | |
| Kansas | Fully Exempt | |
| Kentucky | Fully Exempt | |
| Louisiana | Fully Exempt | |
| Maine | Partial Exemption | Limited retirement income deduction. |
| Maryland | Partial Exemption | Significant exclusion for military retirement income, but generally not a full exemption for all. |
| Massachusetts | Fully Exempt | |
| Michigan | Fully Exempt | |
| Minnesota | Fully Exempt | |
| Mississippi | Fully Exempt | |
| Missouri | Fully Exempt | |
| Montana | Fully Exempt | |
| Nebraska | Partial Exemption | Phasing out tax on Social Security; general retirement exclusions may apply to military pay, but not fully exempt. |
| Nevada | No State Income Tax | |
| New Hampshire | No State Income Tax (except I&D) | |
| New Jersey | Fully Exempt | Recent changes made military retirement fully exempt. |
| New Mexico | Partial Exemption | Up to $10,000 retirement exclusion for those 65+ (includes military retirement). |
| New York | Fully Exempt | For those age 55 and older. |
| North Carolina | Fully Exempt | |
| North Dakota | Fully Exempt | |
| Ohio | Fully Exempt | |
| Oklahoma | Fully Exempt | |
| Oregon | Fully Taxed | No specific exemption, general retirement income credit may apply. |
| Pennsylvania | Fully Exempt | Exempts all retirement income, including military pensions. |
| Rhode Island | Partial Exemption | Offers a modest retirement income exclusion for certain income levels, may apply to military pay. |
| South Carolina | Fully Exempt | |
| South Dakota | No State Income Tax | |
| Tennessee | No State Income Tax (except I&D) | |
| Texas | No State Income Tax | |
| Utah | Fully Exempt | |
| Vermont | Fully Exempt | |
| Virginia | Fully Exempt | |
| Washington | No State Income Tax | |
| West Virginia | Fully Exempt | |
| Wisconsin | Fully Exempt | |
| Wyoming | No State Income Tax |
Disclaimer: Tax laws are complex and subject to change. This content is for informational purposes only and not tax advice. Please consult with a qualified tax professional or financial advisor for personalized advice regarding your specific situation.