Worst States to Retire for Taxes 2027
Retirement is a time many of us dream of—a chance to relax, enjoy hobbies, and spend time with loved ones without the daily grind of work. But for many, the joy of retirement can be overshadowed by the looming specter of taxes, especially state taxes, which can significantly erode carefully saved nest eggs. It's a real concern, and rightfully so, as some states are far less friendly to retirees than others. This comprehensive guide will meticulously break down the worst states for retirees from a tax perspective, helping you understand the financial landscape and make informed decisions.
Understanding Retirement Income Taxation by State
When you retire, your income streams often change dramatically, shifting from regular paychecks to a mix of Social Security benefits, pension payouts, and withdrawals from retirement accounts like 401(k)s and IRAs. The tricky part is that each state treats these income sources differently, creating a complex patchwork of tax rules that can make planning incredibly challenging. Understanding these nuances is the first critical step in assessing a state's tax-friendliness for retirees.
Different Types of Retirement Income
Retirement income isn't a monolith; it's a diverse portfolio of funds, each with its own tax implications at both the federal and state levels. For most retirees, the primary sources include Social Security benefits, which are often the bedrock of a retirement plan. Then there are traditional pension payments, which can come from former employers, military service, or government agencies. Many individuals also rely heavily on distributions from tax-deferred retirement accounts, such as 401(k)s, 403(b)s, and traditional IRAs, which have been growing tax-free for decades. Additionally, some retirees may have income from personal savings, investments, or even part-time work, all of which fall under various tax rules.
It's not just about what kind of income you have, but also how much. States often have different thresholds and exemptions that kick in based on your total adjusted gross income. For instance, a state might fully exempt a certain amount of pension income, but everything above that threshold becomes taxable. This makes it crucial to understand the specific components of your retirement income and how each piece might be treated by your state of residence.
Furthermore, capital gains from investments, rental income from properties, and interest from savings accounts can also contribute to a retiree's overall income. These categories often have their own set of state-specific rules and rates, which can further complicate the picture. A state might be considered "tax-friendly" for Social Security but could heavily tax investment income, impacting a retiree who relies heavily on their investment portfolio.
How States Tax Pensions and 401(k)/IRA Withdrawals
The way states approach pensions and withdrawals from tax-deferred retirement accounts is a major differentiator when evaluating tax-friendliness for retirees. Many states, in an effort to attract or retain retirees, offer partial or full exemptions for these types of income. However, a significant number of states still tax these distributions, sometimes at their full marginal income tax rates, which can be quite substantial.
For example, states like Pennsylvania and Illinois are often cited as being very friendly in this regard because they generally do not tax pension income or withdrawals from 401(k)s and IRAs. This can be a huge benefit for retirees who have substantial savings in these accounts. On the other hand, states like California or New York, with their high-income tax brackets, will tax these distributions as ordinary income, without specific exclusions, unless certain conditions are met. This means a retiree in one of these states could see a significant chunk of their hard-earned retirement savings go towards state income taxes.
It's also important to note that some states offer age-based exclusions or income-based subtractions. For instance, some states might allow a certain amount of pension income to be excluded if you are over a specific age, say 65. Others might have a tiered system where lower-income retirees receive larger exemptions. Understanding these specific exemptions, which vary wildly from state to state as detailed in our guide on Retirement Income Exclusions by State, is critical for accurate tax planning.
State Taxation of Social Security Benefits
Perhaps one of the most surprising aspects for new retirees is that Social Security benefits, while often partially taxable at the federal level, are also taxed by a handful of states. Most states recognize the importance of Social Security as a lifeline for seniors and choose to exempt these benefits entirely from state income tax. This is great news for retirees in the vast majority of the country.
However, there are still a few states that continue to tax Social Security benefits, mirroring the federal rules or having their own unique thresholds. These states include Colorado, Connecticut, Kansas, Minnesota, Montana, New Mexico, Rhode Island, Utah, Vermont, and West Virginia (though West Virginia is phasing out this tax). If you're considering retiring in one of these states, your Social Security benefits could be subject to an additional tax burden, which can be a significant hit to your fixed income. Our detailed post, Social Security Taxation: Federal + the 8 States, provides a complete picture of which states tax these benefits and how.
The impact of this tax can vary depending on your overall income level, as states often use adjusted gross income (AGI) thresholds similar to federal guidelines. For instance, a single filer with a modest income might not pay state tax on their Social Security benefits, while someone with higher income from other sources could find a portion of their Social Security taxed. This makes it crucial to not just look at whether a state taxes Social Security, but at the specific rules and thresholds they apply.
Identifying the Unfriendliest States for Retiree Taxes
When we talk about the "worst" states for retirees in terms of taxes, we're not just looking at one type of tax. It's a cumulative burden that factors in income tax on various retirement sources, property taxes, sales taxes, and even inheritance or estate taxes. For 2026, some states consistently emerge as having a higher overall tax burden on seniors, making them less attractive for those on a fixed income.
States with High Income Taxes on Retirement Income
A state's general income tax rates can be a major red flag for retirees, especially if those rates apply broadly to various forms of retirement income without significant exemptions. States with progressive income tax structures and high top marginal rates often make the list of less tax-friendly places. Even if a state offers some exemptions, if its general income tax is exceptionally high, it can still be detrimental.
Take California, for instance. It boasts the highest top marginal income tax rate in the nation, which can extend to pension and 401(k)/IRA distributions. While the state doesn't tax Social Security, the sheer weight of its regular income tax can significantly impact higher-earning retirees. Similarly, states like Oregon and Minnesota have high top marginal income tax rates and relatively few broad exemptions for retirement income, meaning a large portion of a retiree's income could be subject to state taxes.
It's important to differentiate between states that have a high overall income tax burden and those that specifically target retirement income. Some states might have a high income tax but offer generous exemptions for pensions and retirement account withdrawals. Conversely, some states might have lower general income tax rates but tax all forms of retirement income. Therefore, understanding the nuances of How Each State Taxes Retirement Income (50-State Guide) is crucial for a complete picture.
States Still Taxing Social Security
While the number of states taxing Social Security benefits has been shrinking over the years, the remaining few still make a significant impact on retirees living within their borders. States like Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont, alongside West Virginia (which is actively phasing it out), continue to levy a state income tax on at least a portion of Social Security benefits.
This taxation can be a particularly bitter pill for retirees, as Social Security often forms a substantial part of their income, and the federal government already taxes a portion of these benefits for many. Adding a state tax on top of that can mean less money in your pocket each month. For example, a retiree in Minnesota might face both federal and state income tax on their Social Security, which can amount to a considerable sum, especially if they have other retirement income pushing them into higher tax brackets.
For those planning their retirement, checking if a potential state taxes Social Security is a fundamental step. Even a small percentage can add up over years, impacting your overall financial security. Websites like SmartAsset offer comprehensive breakdowns of state tax rules, including Social Security taxation, which can be invaluable for retirees.
Overall High Tax Burden States for Seniors
Beyond just income tax on retirement benefits, an "overall high tax burden" state considers all the ways a state extracts revenue from its residents, including property taxes, sales taxes, and sometimes inheritance or estate taxes. Some states, even if they appear friendly on one front (e.g., no income tax), can make up for it with other high taxes, making them ultimately unfavorable for many retirees.
For instance, while Florida has no state income tax, its property taxes can be quite high in popular retirement areas, and its sales tax is substantial. Similarly, Texas is another state with no income tax, but its property taxes are among the highest in the nation. For retirees on a fixed income, a high property tax bill can be just as, if not more, impactful than an income tax, especially if their home equity is their primary asset.
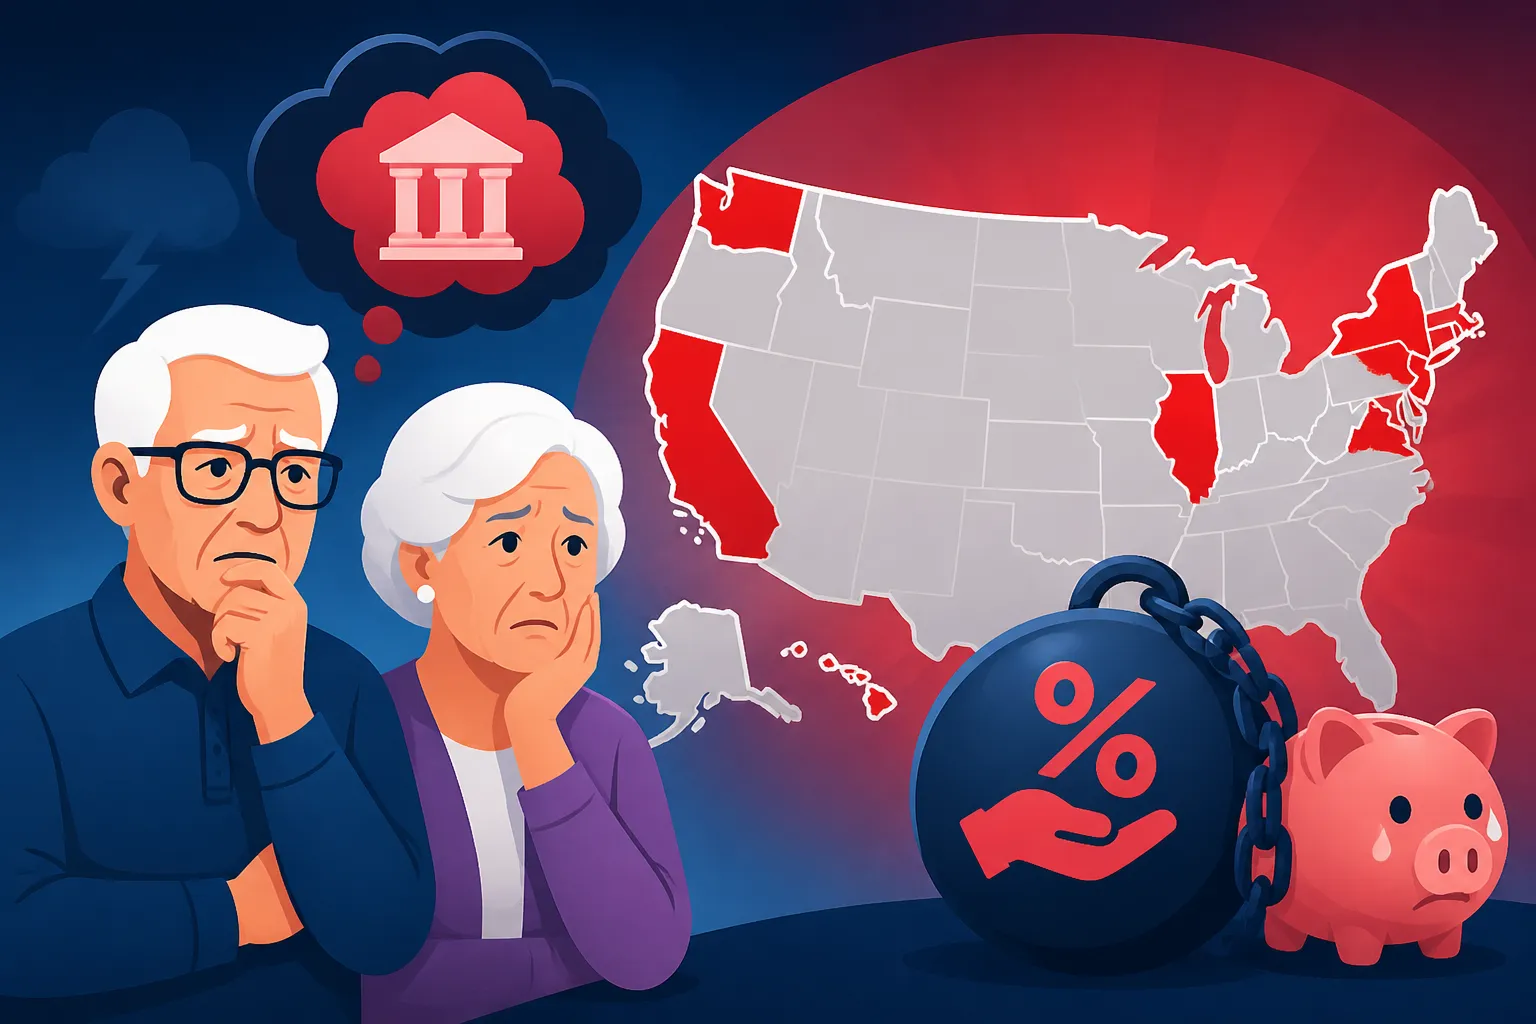
When considering the total picture, states like New Jersey, Connecticut, New York, and Illinois often rank highly on lists of overall tax burdens for retirees. These states typically combine high property taxes with significant income taxes (though sometimes with specific exemptions for certain retirement income) and above-average sales taxes. The cumulative effect of these various taxes can make living in these states financially challenging for retirees, even those with substantial savings.
Deeper Dive into High-Tax States
Let's zoom in on some specific states that consistently appear on the list of least tax-friendly places for retirees, focusing on the nuances that make them challenging. It's not always just a single factor but a combination of tax policies that create a less-than-ideal environment for those on fixed incomes.
California's Comprehensive Tax Burden for Retirees
California, while an undeniably beautiful state with a desirable climate for many, comes with a significant tax price tag for retirees. The Golden State has the highest top marginal income tax rate in the country, currently reaching up to 13.3% for the highest earners. While Social Security benefits are fully exempt from state income tax, other forms of retirement income, such as pension payments and withdrawals from 401(k)s and IRAs, are taxed as ordinary income at these high rates.
Imagine a retiree living in a desirable coastal town like Santa Barbara or a bustling urban center like San Francisco. Their pension and IRA withdrawals, which might be substantial, are subject to California's aggressive progressive income tax brackets. This can quickly deplete retirement savings. While there are some deductions and credits available, they often don't fully offset the impact of the high income tax rates. It's a state where a significant portion of your financial planning needs to account for state tax liabilities.
Furthermore, California's property taxes, while not the highest in the nation, are far from low, especially in prime real estate markets. When combined with a statewide sales tax rate that can go up to 7.25% (plus local rates pushing it higher in many areas), the overall tax burden becomes substantial. For many, the dream of retiring in California clashes directly with the financial reality of its comprehensive tax environment, making it one of the Highest Income Tax States in 2026 and a challenging place for retirees.
The New York Tax Landscape for Seniors
New York State, particularly if you're considering the metropolitan area, presents another formidable tax challenge for retirees. Like California, New York has a progressive income tax system with high top marginal rates. For 2026, the state's income tax rates can climb quite high, and these rates generally apply to pension income and withdrawals from retirement accounts. However, there's a significant silver lining: New York offers a substantial exclusion for pension and annuity income, up to $20,000 per person, which can ease the burden for many. Social Security benefits are also completely exempt from state income tax.
Despite these exemptions, if your retirement income significantly exceeds the exclusion thresholds, you could still be looking at a substantial state tax bill. Moreover, if you live in New York City, you'll also contend with a separate city income tax, which adds another layer of complexity and cost. Our guide on NYC Income Tax Explained (2026 Rates) delves into these specific city-level burdens.
Beyond income taxes, New York is notorious for its high property taxes, especially in suburban areas around major cities. These taxes can be incredibly burdensome for retirees on fixed incomes, even if they own their homes outright. Coupled with generally high sales taxes and other local levies, New York's overall tax environment makes it one of the least attractive states for many retirees, despite its cultural richness and amenities.
Other High-Tax States to Watch
While California and New York often grab headlines for their high taxes, several other states pose significant tax challenges for retirees. These states might not hit the absolute top in every single tax category, but their combined burden makes them less than ideal.
New Jersey: Known for some of the highest property taxes in the nation, New Jersey also has a progressive income tax that can apply to retirement income. While it offers a sizable exclusion for pension and retirement income (which has been expanding), the property tax burden alone is enough to deter many retirees. The statewide sales tax also adds to the cost of living. For someone who has paid off their home, a $10,000+ annual property tax bill can be a devastating drain on retirement savings.
Connecticut: This New England state is another one with high property taxes and a progressive income tax. Connecticut does tax Social Security benefits for higher earners, though it provides a generous pension and annuity exclusion for qualifying individuals. The high cost of living, combined with high income, property, and sales taxes, makes it a challenging place for retirees seeking to maximize their financial longevity.
Minnesota: Minnesota has a progressive income tax with one of the nation's highest top rates, and it's also one of the few states that taxes Social Security benefits. While there are some subtractions for retirement income, the overall tax burden for retirees can be substantial. Its property taxes are also above the national average, making it a state where retirees need to carefully plan their finances.
Massachusetts: The Bay State has a flat income tax rate, which might seem appealing at first glance, but it's applied to most forms of retirement income, including pensions and 401(k)/IRA withdrawals (though Social Security is exempt). Massachusetts also has relatively high property taxes and an above-average sales tax, contributing to a high overall tax burden. Retirees in Massachusetts often find that while the tax structure is simpler, the cumulative effect can still be quite expensive.
Beyond Income Tax: Other Tax Burdens for Retirees
Focusing solely on income tax rates when planning for retirement can be a big mistake. Many states that boast "no income tax" or generous retirement income exemptions can make up for that lost revenue through other avenues, often hitting retirees just as hard, if not harder. These include property taxes, sales and excise taxes, and sometimes even inheritance or estate taxes, all of which can significantly impact a fixed income.
The Impact of High Property Taxes on Fixed Incomes
For most homeowners, their home is their largest asset, and for many retirees, it's also where they plan to spend their golden years. However, property taxes can become a heavy burden, especially as incomes decrease in retirement. Property taxes are local taxes, assessed by counties, cities, and school districts, and they fund essential services like schools, police, and fire departments. These taxes can vary wildly even within the same state, but some states have consistently higher statewide averages.
Consider a retiree who has paid off their mortgage. They might think they're free from housing payments, but a property tax bill of $8,000 or $10,000 a year is still a significant recurring expense, especially if their only income is from Social Security and a modest pension. States like New Jersey, Illinois, New Hampshire, and Texas are known for some of the highest effective property tax rates in the country. Even if these states have no income tax, or are generally considered "tax-friendly" in other areas, their property tax burden can completely negate those benefits for homeowners.
Some states do offer property tax relief programs for seniors, such as homestead exemptions, circuit breaker credits, or assessment freezes, which can provide some much-needed relief. However, these programs often have strict eligibility requirements, including income limits or age requirements. It's crucial for retirees to investigate whether they qualify for any of these programs in their chosen state, as they can make a substantial difference in the annual tax burden.
How Sales and Excise Taxes Add Up
Sales taxes are another often-overlooked tax burden that disproportionately affects retirees, especially those on tighter budgets. Unlike income taxes, which might have exemptions for retirement income, sales taxes apply to almost every purchase you make, from groceries and clothing to household goods and entertainment. This means that a significant portion of a retiree's spending, even on essentials, is subject to this tax.
States like Tennessee, Arkansas, Alabama, and Louisiana have some of the highest combined state and local sales tax rates in the nation. While states like Tennessee and Florida may not have a state income tax, the higher sales tax can be a stealthy drain on retirement funds. Every time you buy something, a percentage is added on. Over a year, for someone living on a fixed income and trying to stretch every dollar, these cumulative sales taxes can add up to a considerable amount.
Excise taxes, which are taxes on specific goods like gasoline, tobacco, and alcohol, also contribute to the overall cost of living. While not as universally impactful as sales tax, they can still add up for individuals who regularly purchase these items. For instance, a retiree who drives frequently might find themselves paying more in gasoline taxes in certain states. When evaluating a state's tax-friendliness, it's essential to look at the total consumption tax picture, not just the sales tax rate in isolation.
Inheritance and Estate Taxes: A Hidden Cost
While income, property, and sales taxes impact retirees directly during their lifetime, inheritance and estate taxes come into play after passing, affecting their beneficiaries. These are often referred to as "death taxes," and they can significantly reduce the wealth passed on to heirs. Only a handful of states levy an estate tax, and even fewer have an inheritance tax, but for those that do, the impact can be substantial.
An estate tax is a tax on the deceased person's right to transfer property at death. It's paid by the estate itself before assets are distributed to beneficiaries. States that currently impose an estate tax include Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont, Washington, and the District of Columbia. The thresholds for these state estate taxes vary widely. For example, in Oregon, the threshold is $1 million, meaning estates valued over that amount are subject to tax, while in New York, the threshold is higher.
An inheritance tax, on the other hand, is paid by the beneficiary receiving the assets, not the estate itself. Even fewer states impose an inheritance tax: Iowa, Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. The rates and exemptions for inheritance taxes often depend on the relationship between the deceased and the beneficiary, with spouses and direct descendants usually receiving more favorable treatment or complete exemption. For instance, in New Jersey, spouses and children are exempt from inheritance tax, but other beneficiaries, like siblings or nieces/nephews, might pay a significant percentage.
For retirees planning their legacy, understanding these taxes is critical. Moving from a state with an estate tax to one without, or vice-versa, can have profound implications for their heirs. Websites like SmartAsset can help individuals understand the nuances of these taxes and how they might affect their estate planning.
Strategies for Retirees in High-Tax Environments
For many retirees, moving to a new state simply isn't an option. They might have deep community ties, family obligations, or a strong desire to stay in their long-time home. If you find yourself in a high-tax state, it doesn't mean you're helpless. There are still proactive steps you can take to mitigate your tax burden and make your retirement savings last longer.
Utilizing State-Specific Exemptions and Credits
Even in states with a generally high tax burden, there are often specific exemptions, deductions, and credits designed to help seniors. It's your responsibility to know about them and claim them! These can vary widely, but they typically include things like:
- Pension and Retirement Income Exclusions: Many states offer a partial or full exclusion for pension income, 401(k) withdrawals, or IRA distributions up to a certain dollar amount or for individuals over a certain age. For instance, New Jersey has been expanding its retirement income exclusion for taxpayers meeting specific income thresholds.
- Social Security Exemptions: While a few states tax Social Security, the vast majority do not. In those states that do tax it, there are often income thresholds below which your benefits are exempt.
- Property Tax Relief: As mentioned, many states and local governments offer programs like homestead exemptions, "circuit breaker" tax credits, or property tax freezes for seniors, veterans, or those with limited incomes. These can significantly reduce your annual property tax bill. For example, in California, the Senior Citizens Property Tax Assistance Program can offer some relief.
- Other Tax Credits: Some states offer credits for dependent care, energy-efficient home improvements, or even specific medical expenses, which could be relevant to retirees. Understanding your state's particular offerings, as covered in topics like State Tax Credits: Solar, College & Dependent Care, can help.
The key here is to be diligent. Don't assume anything. Review your state's tax department website or consult with a tax professional to ensure you're taking advantage of every possible break. A few hours of research or a consultation could save you hundreds or even thousands of dollars each year.
Professional Financial Planning and Tax Advice
Navigating the complexities of state taxes in retirement is not something you have to do alone. In fact, for many, it's best handled with the help of experienced professionals. A qualified financial planner specializing in retirement and tax planning can provide invaluable guidance. They can help you:
- Optimize Withdrawal Strategies: A financial advisor can help you determine the most tax-efficient way to draw income from your various retirement accounts (401(k)s, IRAs, Roth IRAs, brokerage accounts) to minimize your state income tax liability. This might involve converting traditional IRA funds to Roth IRAs in lower-income years or strategically timing distributions.
- Understand Required Minimum Distributions (RMDs): Once you reach a certain age, you must start taking RMDs from traditional IRAs and 401(k)s. A planner can help you manage these distributions in a tax-efficient manner, especially since RMDs and State Taxes are often tied together.
- Proactive Tax Planning: Rather than just reacting to your tax bill each year, a professional can help you plan several years in advance, anticipating changes in your income, deductions, or state tax laws. This foresight can lead to significant savings.
- Connect with Local Expertise: A local tax advisor will be intimately familiar with all the specific nuances of your state's tax code, including local and city income taxes (like those in Ohio or Pennsylvania).
While there's a cost associated with professional advice, the money saved through optimized tax strategies often far outweighs the fees, making it a wise investment for many retirees.
Understanding Residency Rules for Tax Purposes
For retirees who might be considering splitting their time between states, or even fully relocating but still maintaining some ties to a high-tax state, understanding State Tax Residency Rules Explained is paramount. State residency for tax purposes is a complex area, and it's not always as simple as where you spend the most nights. States, especially high-tax ones, are very aggressive in auditing individuals who claim to have moved but still maintain significant connections.
The key concepts here are domicile and statutory residency. Your domicile is your true, fixed, and permanent home—the place where you intend to return whenever you are absent. You can only have one domicile. Statutory residency, on the other hand, is often triggered by spending more than 183 days in a state and maintaining a "permanent place of abode" there, regardless of your intent to make it your permanent home. Our article on The 183-Day Rule for State Taxes offers a deeper dive into this specific trigger.
To successfully change your residency for tax purposes and avoid being taxed by your former high-tax state, you need to demonstrate a clear intent to abandon your old domicile and establish a new one. This involves a pattern of actions, such as:
- Registering to vote in the new state.
- Obtaining a new driver's license and vehicle registration.
- Changing your mailing address and updating it with financial institutions.
- Opening bank accounts in the new state.
- Spending a majority of your time in the new state.
- Severing ties with professional and social organizations in the old state.
States like New York and California are particularly diligent in auditing individuals who claim to have moved, so meticulous record-keeping and a clear break from the old state are essential to avoid potential double taxation.
The Nuances of Relocation: It's Not Just About Taxes
The allure of a "no income tax" state can be powerful for retirees looking to stretch their dollars further. However, making a big move solely based on tax advantages can sometimes lead to unforeseen downsides. Retirement is about lifestyle, community, and well-being as much as it is about finances. It's crucial to consider the full picture before packing your bags.
Cost of Living Beyond Taxes
While saving on state income taxes sounds fantastic, it's just one piece of the financial puzzle. A state with no income tax might have significantly higher costs in other areas, ultimately negating or even outweighing the tax savings. For example, housing costs, whether renting or buying, can be vastly different from one state to another, or even within different regions of the same state. A beachfront condo in Florida might seem attractive, but its price tag could easily swallow any income tax savings.
Utilities, groceries, transportation, and entertainment are all part of your daily expenses, and their costs vary considerably across the country. For example, while Washington state has no income tax, the cost of living in Seattle is notoriously high, especially for housing. Similarly, Texas might have no income tax, but its property taxes can be among the highest in the nation, as discussed in our article, Is Texas Really Tax Free? The Full Picture. A retiree moving there from a high-income tax state might find their overall monthly expenses haven't decreased as much as they'd hoped, or even increased.
Therefore, when evaluating a move, it's essential to create a comprehensive budget that includes all potential expenses in the new location. Look beyond the tax headline and dig into average housing costs, utility bills, and even the price of gas and groceries. This holistic view, often provided by financial planning tools and resources from organizations like SmartAsset, will give you a much more accurate picture of your potential financial well-being.
Access to Healthcare and Amenities
For retirees, healthcare is often a top priority, and the quality and accessibility of medical services can vary significantly by state and even by region. Moving to a state with lower taxes might seem appealing, but if it means sacrificing access to specialized doctors, top-tier hospitals, or preferred health networks, it might not be worth the financial savings. Consider your current healthcare needs and what you anticipate needing in the future. Will your existing doctors be covered? Are there good hospitals nearby? What are the wait times for specialists?
Beyond healthcare, think about the amenities and services that contribute to your quality of life. Do you enjoy cultural events, outdoor activities, or proximity to specific types of shopping or dining? Some states, particularly more rural or less developed ones that might have a lower cost of living and lower taxes, might also have fewer amenities. If you're used to living near museums, theaters, or extensive public transportation, moving to an area without these could lead to a feeling of isolation or dissatisfaction, regardless of the tax benefits.
For instance, while a small town in a low-tax state like Wyoming might offer incredible natural beauty and minimal tax burden, it might not have the extensive medical facilities or cultural opportunities found in larger metropolitan areas in states like Massachusetts or California, even with their higher taxes. It's a trade-off that each individual must weigh carefully based on their personal priorities.
Family, Friends, and Social Support Systems
One of the most profound, yet often underestimated, factors in retirement planning is the importance of social connections. Your family, friends, and community networks are vital for your emotional well-being and overall happiness. Moving away from these established support systems, even for significant tax savings, can lead to loneliness, isolation, and a decrease in life satisfaction.
Imagine moving to a beautiful, tax-friendly state, only to find yourself far from your children and grandchildren, or unable to easily participate in the social clubs and volunteer activities that brought you joy. The emotional cost of such a move can far outweigh any financial gain. Many retirees find that being close to family, or maintaining their established social circle, is a non-negotiable aspect of their retirement.
Therefore, before making any definitive plans, have open conversations with your family and close friends. Understand their perspectives and the potential impact of your move on your relationships. Explore whether a new location offers opportunities to build new social connections, or if it makes it easier for family to visit. Sometimes, a slightly higher tax burden in a familiar environment with strong social ties is a far better choice for overall happiness and well-being than a drastic move for purely financial reasons.
Comparing the "Worst" with the "Best" for a Full Picture
To truly understand the impact of state taxes on retirement, it's helpful to contrast the challenging states with those that actively work to be tax-friendly. This comparison highlights the range of tax environments across the U.S. and underscores why strategic planning is so important for retirees.
States with Broad Retirement Income Exemptions
On the opposite end of the spectrum from the "worst" states are those that go out of their way to exempt significant portions, or even all, of a retiree's income from state taxation. These are the states often lauded as the Most Tax-Friendly States for Retirees 2027.
Many states fall into this category by broadly exempting most, if not all, forms of retirement income, including pensions, 401(k)s, IRAs, and Social Security. For example, Illinois and Pennsylvania are famous for exempting all retirement income. Other states like Mississippi, Alabama, and Louisiana offer significant exemptions for pensions and retirement account withdrawals, while fully exempting Social Security benefits. These states recognize that retirees are a valuable part of their population and seek to alleviate financial strain on fixed incomes.
The impact of these exemptions can be massive. Consider a retiree with a $50,000 pension and $30,000 in IRA withdrawals annually. In a state that taxes all of this income at a 5% rate, that's $4,000 in state income tax. In a state with broad exemptions, that $4,000 stays in the retiree's pocket. Over the course of a 20-year retirement, that's $80,000 in savings, which can be a game-changer for financial security and quality of life.
No Income Tax States as Potential Havens
For many, the ultimate goal is to retire in a state with no income tax at all. These seven states — Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, and Wyoming — do not impose a state income tax on wages, pensions, 401(k) withdrawals, or Social Security. This immediately removes a significant layer of tax complexity and burden for retirees. Our guide on States With No Income Tax (2026 Full List) provides a comprehensive overview.
However, as discussed earlier, "no income tax" doesn't necessarily mean "no taxes." These states still need to generate revenue, and they often do so through higher property taxes or sales taxes. For example, Florida has no income tax, and it's a popular retirement destination, but its property taxes can be high, and its sales tax is substantial. Similarly, Texas has no income tax, but its property tax burden is among the highest in the country.
The suitability of a no-income-tax state as a retirement haven depends heavily on a retiree's financial profile. For those with high retirement incomes who would otherwise pay significant state income taxes, these states can offer substantial savings. For retirees whose primary assets are their homes, and whose income is modest, a no-income-tax state with high property taxes might not be the most advantageous choice. It's a careful balance that requires individualized assessment.
| State Type | Income Tax on Pensions/401(k) | Social Security Tax | Average Property Tax | Average Sales Tax |
|---|---|---|---|---|
| High Tax | Fully Taxed (High Rates) | Often Taxed (High Income) | High | High |
| Mixed Tax | Partial Exemption | Often Exempt | Moderate | Moderate |
| No Income Tax | Exempt | Exempt | Can Be High | Can Be High |
This table provides a generalized comparison. Specific rates and exemptions vary widely by state.
Keeping an Eye on Future Tax Changes and Beyond
The tax landscape is rarely static, and state tax laws are no exception. What holds true for retirees today might change in a few years, making it imperative to stay informed about potential legislative shifts. For retirees, especially those considering a move or already living in a high-tax state, anticipating these changes can be a crucial part of long-term financial planning.
Legislative Trends Affecting Senior Taxes
States are constantly re-evaluating their tax codes, often driven by economic conditions, political shifts, or demographic changes. For retirees, this means keeping an eye on several key legislative trends:
- Social Security Taxation: We've seen a trend over recent years of states repealing or phasing out their tax on Social Security benefits (e.g., Missouri, Nebraska, Kansas recently eliminated theirs, and West Virginia is phasing theirs out). This is a positive trend for seniors, but there's no guarantee it will continue indefinitely in all remaining states. Conversely, budget shortfalls could theoretically lead some states to reconsider this, though it's politically unpopular.
- Retirement Income Exemptions: Many states periodically adjust their exemptions or subtractions for pension income and retirement account withdrawals, often increasing them to be more competitive or to provide relief to seniors. It's important to monitor these adjustments, as they can significantly impact your taxable income.
- Property Tax Relief Programs: With rising home values and property taxes, many states are under pressure to offer more relief to seniors, often through expanded homestead exemptions, freezes, or "circuit breaker" programs. These programs are often dynamic and can change annually.
- Flat Tax Proposals: Some states with progressive income tax systems are considering a shift to a flat tax model, which could either benefit or harm retirees depending on their income level and the specific flat rate chosen. Our article on States With a Flat Income Tax (2026) explains how these systems work.
- Local Tax Changes: Don't forget local taxes! City and county income taxes, as seen in places like Philadelphia or many cities in Ohio, and local property tax rates, are constantly being adjusted. These changes can often fly under the radar but have a direct impact on your retirement budget.
Staying abreast of these legislative trends, perhaps by following state tax news or consulting resources from financial organizations, is key to informed retirement planning.
Importance of Staying Informed
Given the dynamic nature of state tax laws, simply making a decision based on current information and then forgetting about it could prove costly. Tax codes are living documents, influenced by everything from state budgets to voter initiatives. What makes a state tax-friendly today could change tomorrow.
For example, a state might increase its standard deduction for seniors, or perhaps introduce a new tax credit for specific retirement expenses. Conversely, a state facing a budget deficit might reduce exemptions or even introduce new taxes. Regularly reviewing your state's Department of Revenue website, consulting with a tax professional annually, and keeping up with financial news specific to retirees are all crucial actions.
Think of it as an ongoing process. Just as you review your investment portfolio regularly, your tax strategy in retirement also needs periodic assessment and adjustment. Many reputable financial news outlets and organizations, including platforms often cited by SmartAsset, provide excellent up-to-date information on state tax changes relevant to seniors. By staying informed, you empower yourself to adapt your financial plan, seize new opportunities for savings, and avoid unexpected tax surprises, ensuring your retirement years are as financially secure and stress-free as possible.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute tax, financial, or legal advice. Tax laws are complex and subject to change, and their application can vary widely based on individual circumstances. It is essential to consult with a qualified tax professional or financial advisor for personalized advice regarding your specific situation. We make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the information contained herein for any purpose.