Which States Give Credit for 529 Contributions?
Saving for college or vocational training can feel like a monumental task, often leaving parents and grandparents wondering if there are any financial breaks out there to ease the burden. You're already doing the smart thing by looking into 529 plans, but figuring out which states actually give you a little back for your efforts can be a real head-scratcher. This comprehensive guide is here to untangle the complexities of state tax credits and deductions for 529 contributions, helping you understand your options and maximize your savings.
Understanding 529 Plans and State Tax Benefits
Let's be honest, the world of taxes and financial planning often feels like it's designed to confuse us. You hear about 529 plans, and the federal tax benefits—tax-free growth and tax-free withdrawals for qualified educational expenses—are certainly appealing. But then you start digging into state-level benefits, and suddenly it's a patchwork quilt of different rules, deductions, and credits that can make your head spin. It’s completely understandable to feel overwhelmed when trying to make the best decision for your family’s future education savings.
A 529 plan, named after Section 529 of the Internal Revenue Code, is an investment account that offers tax advantages when used to pay for qualified education expenses for a designated beneficiary. These aren't just for four-year universities; they can cover community college, trade schools, and even K-12 tuition up to a certain amount. While the federal tax treatment is generally consistent across the board, it's the state-level benefits that really vary and can make a big difference in your overall savings strategy.
The Difference Between Tax Credits and Tax Deductions
Before we dive into which states offer what, it's really important to understand the fundamental difference between a tax credit and a tax deduction. This isn't just semantics; it's about how much money stays in your pocket.
A tax deduction reduces your taxable income. For example, if you have a taxable income of $70,000 and you make a $5,000 deductible contribution to a 529 plan, your state taxable income drops to $65,000. The amount you save depends on your marginal tax rate. If your state's tax rate is 5%, that $5,000 deduction would save you $250 ($5,000 * 0.05). It’s a good benefit, but it doesn't directly reduce your tax bill dollar-for-dollar. Many states offer income tax deductions, and it’s a popular way to encourage savings. You can learn more about how deductions work in our guide on State Standard Deduction vs Itemized (2026).
On the other hand, a tax credit directly reduces the amount of tax you owe. If you have a state tax liability of $3,000 and you receive a $250 tax credit, your tax bill immediately drops to $2,750. A credit is generally more valuable than a deduction of the same amount because it’s a dollar-for-dollar reduction of your tax liability. While less common than deductions, some states do offer credits, which can be incredibly beneficial.
Why State Residency Matters for 529 Benefits
This is where things can get a little tricky, and it's a common point of frustration for many. Most states that offer a tax credit or deduction for 529 plan contributions impose residency requirements. This often means that to claim the state tax benefit, you, the account owner, must be a resident of that state. More importantly, many states only offer these benefits if you contribute to their specific state-sponsored 529 plan.
For instance, if you live in Georgia, you might get a deduction for contributing to the Georgia Path2College 529 Plan. But if you decide to contribute to, say, New York's 529 plan because you like their investment options, your Georgia income tax return might not see a dime of benefit. However, some states are more generous and offer a tax benefit regardless of which state's 529 plan you contribute to. This is often referred to as "529 tax parity" or "any state's plan" benefit. It pays to check these specific rules for your state of residence, especially if you're considering an out-of-state plan.
States Offering Tax Credits for 529 Contributions
Okay, let's get to the good stuff! Tax credits are the golden ticket of state 529 benefits because they directly slash your tax bill. While not as common as deductions, several states understand the power of a direct credit to incentivize college savings. Remember, these credits usually come with caps, and often require you to contribute to your home state's 529 plan.
It's also worth noting that states can change their tax laws, so what's true today might be slightly different next year. Always double-check with your state's revenue department or a trusted tax professional.
Detailed Breakdown of States with 529 Credits
As of the current understanding, very few states offer a direct credit for 529 contributions. Most states opt for deductions. However, this landscape can shift, and sometimes a state might implement a credit that functions similarly to a deduction but is framed as a credit for lower-income taxpayers, or a specific matching program that acts like a credit.
Historically, states like South Carolina have been known for offering a 529 credit. For example, South Carolina often provides a credit for contributions to their Future Scholar 529 plan. The credit amount is usually tied to a percentage of your contributions, with certain maximums. This means if you contribute, say, $2,000 to South Carolina's 529 plan, and the credit is 7%, you'd get $140 directly off your state tax bill. It's a fantastic way to encourage residents to save locally.
Similarly, states might have programs that essentially function like a credit, perhaps a matching grant for low-income families that contribute to a 529 plan. These aren't always explicitly called "tax credits" in the traditional sense, but they provide a similar direct financial boost. When researching, it's beneficial to look beyond just the term "credit" and also investigate "matching grants" or "special programs" related to 529 contributions in your state.
For example, a low-income family in Rhode Island might qualify for a matching grant program for contributions to their CollegeBound Saver 529 plan, which effectively acts like a credit by increasing the funds in the account without the need for additional contributions. While not a tax credit you claim on your return, the net effect is similar to directly reducing your educational cost burden.
It's important to differentiate these from broader tax credits. For instance, while a state might have a general State Child Tax Credits 2026 or State Earned Income Tax Credits (EITC) Guide, these are separate from specific 529 contribution credits. The key is finding those direct incentives aimed at encouraging college savings.
States Offering Tax Deductions for 529 Contributions
This is where the majority of state-level 529 benefits reside. Most states that offer any income tax break for 529 contributions provide a deduction. These deductions can significantly reduce your taxable income, and consequently, your state income tax bill.
The rules for these deductions vary wildly. Some states offer unlimited deductions, others have generous caps, and many require you to use their specific state plan. Let's look at some examples of how these deductions typically work.
Common Deduction Structures
States usually structure their 529 deductions in a few ways:
- Deduction up to a Cap: Many states allow you to deduct contributions up to a certain dollar amount per year. For example, in New York, residents can deduct contributions to the New York's 529 College Savings Program, Direct Plan, up to $5,000 for single filers and $10,000 for married couples filing jointly. This is a substantial benefit that encourages ongoing savings. You can explore this further in our article on the New York 529 Deduction Limit.
- Deduction of the Full Contribution: A few states are incredibly generous and allow you to deduct the entire amount of your 529 contributions, with no cap. Pennsylvania is a fantastic example of this, allowing residents to deduct the full amount contributed to any state's 529 plan. This "any state's plan" benefit is a huge plus, as it gives you the flexibility to choose a plan based on investment options rather than just tax benefits.
- Deduction for Contributions to Any State's Plan: As mentioned, some states offer deductions even if you contribute to an out-of-state 529 plan. This is a less common but highly valuable feature. States like Arizona, Kansas, Missouri, and Montana are examples of states that offer this kind of "529 tax parity." This flexibility can be a game-changer if you have specific investment preferences or if a relative in another state set up a plan for your child. It truly gives you the freedom to pick the best investment options available, without sacrificing a state tax break.
States With No State Income Tax or No Specific 529 Benefit
It’s important to remember that not every state offers a direct tax benefit for 529 contributions. There are a few reasons for this:
- No State Income Tax: Seven states currently have no state income tax, meaning there's no income tax deduction or credit to claim in the first place. These states are Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, and Wyoming. While you won't get a state tax break for contributing, the federal tax benefits of 529 plans still apply, which are significant. You can learn more about these states in our article on States With No Income Tax (2026 Full List).
- State Income Tax, but No 529 Benefit: Some states that do have an income tax simply don't offer any specific tax deduction or credit for 529 contributions. This means you'll still get the federal tax benefits, but your state won't give you an additional incentive. Currently, states such as California, Delaware, Hawaii, Kentucky, Massachusetts, Minnesota, New Jersey, North Carolina, and Vermont typically fall into this category, though rules can always change. If you live in one of these states, your focus will naturally shift to maximizing federal benefits and choosing a plan with strong investment performance and low fees, regardless of its home state. For instance, a Californian might explore various state plans without a local tax incentive, often turning to resources like SmartAsset to compare plan performance and fees.
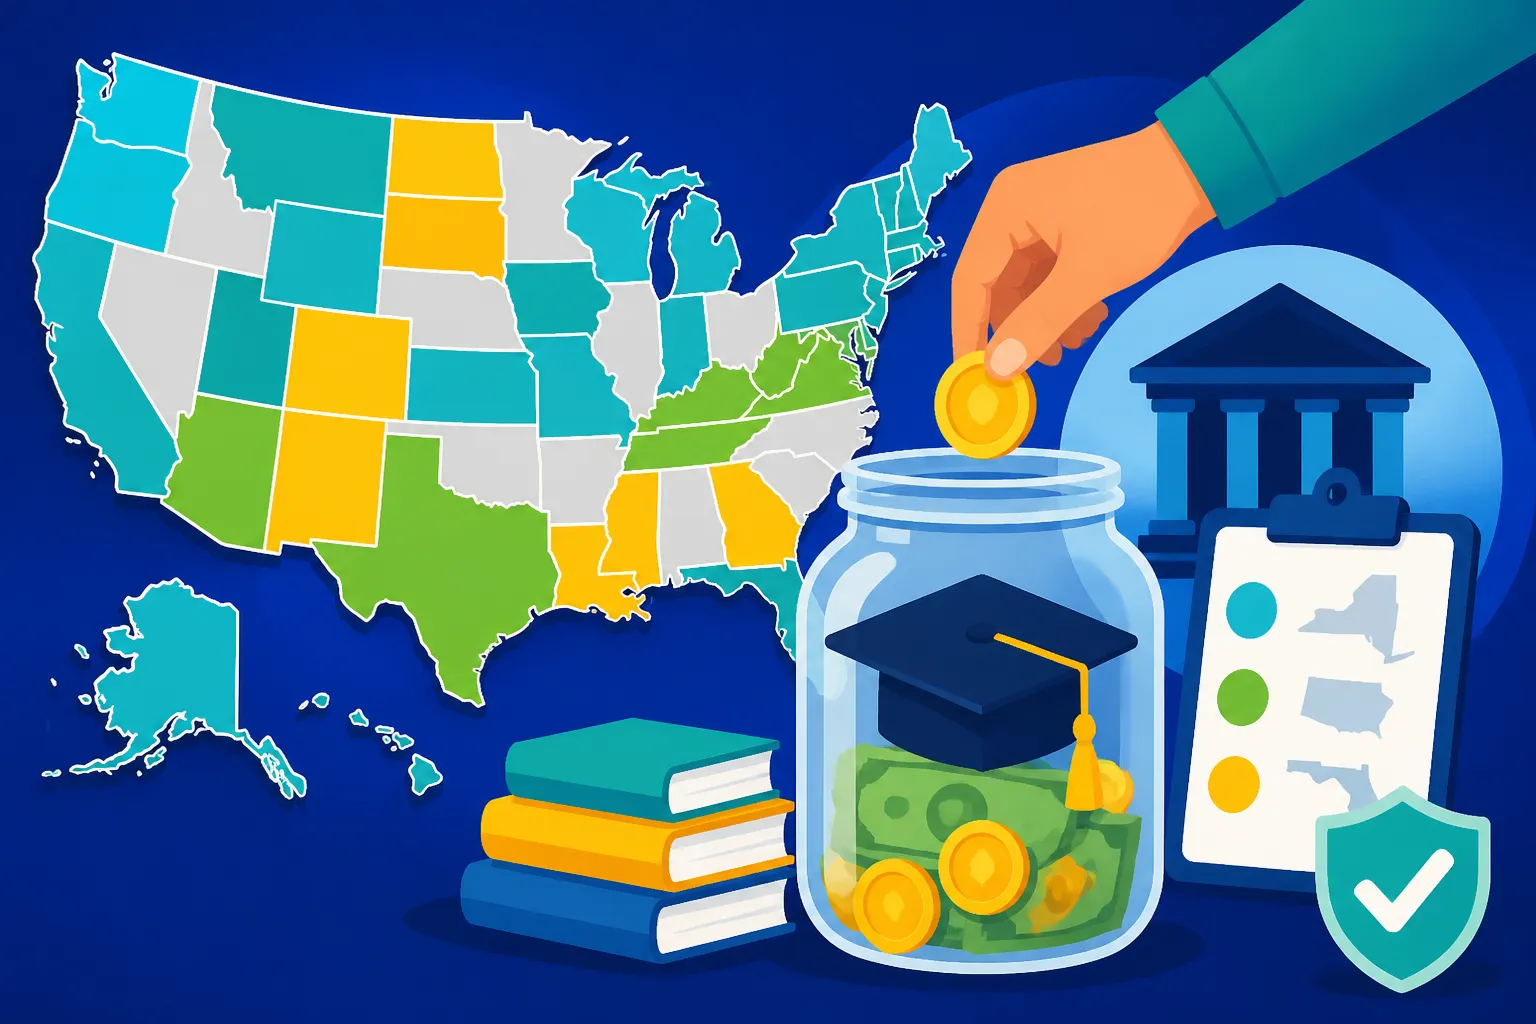
Here's a quick overview of states and their 529 tax treatment, highlighting the general approach. Keep in mind that specific limits and requirements apply to each state.
| State | State Income Tax Benefit Type | Resident Plan Only / Any Plan | Max Benefit Example (Individual) |
|---|---|---|---|
| Alabama | Deduction | Resident Plan Only | $5,000 |
| Arizona | Deduction | Any Plan | $2,000 |
| Arkansas | Deduction | Resident Plan Only | $5,000 |
| Colorado | Deduction | Any Plan | Full Contribution |
| Connecticut | Deduction | Any Plan | $10,000 |
| Idaho | Deduction | Resident Plan Only | $6,000 |
| Illinois | Deduction | Any Plan | $10,000 |
| Indiana | Credit | Resident Plan Only | 20% credit up to $1,000 |
| Iowa | Deduction | Any Plan | $3,970 (2024, adjust annually) |
| Kansas | Deduction | Any Plan | $3,000 |
| Louisiana | Deduction | Resident Plan Only | $2,400 |
| Maine | Deduction | Resident Plan Only | $1,000 |
| Maryland | Credit & Deduction | Resident Plan Only | Credit up to $2,500, Deduction up to $2,500 |
| Michigan | Deduction | Resident Plan Only | $10,000 |
| Mississippi | Deduction | Resident Plan Only | $10,000 |
| Missouri | Deduction | Any Plan | $8,000 |
| Montana | Deduction | Any Plan | $3,000 |
| Nebraska | Deduction | Any Plan | $10,000 |
| New Mexico | Deduction | Resident Plan Only | Full Contribution |
| New York | Deduction | Resident Plan Only | $5,000 |
| North Dakota | Deduction | Resident Plan Only | $5,000 |
| Ohio | Deduction | Any Plan | $4,000 (per beneficiary) |
| Oklahoma | Deduction | Resident Plan Only | $10,000 |
| Oregon | Credit/Deduction (depends on AGI) | Resident Plan Only | Varies by AGI |
| Pennsylvania | Deduction | Any Plan | Full Contribution |
| Rhode Island | Deduction | Resident Plan Only | $500 |
| South Carolina | Deduction (formerly Credit) | Resident Plan Only | Full Contribution |
| Utah | Credit | Resident Plan Only | Varies by AGI (up to $2,460) |
| Virginia | Deduction | Resident Plan Only | Full Contribution |
| West Virginia | Deduction | Resident Plan Only | Full Contribution |
| Wisconsin | Deduction | Resident Plan Only | $3,860 (2024, adjust annually) |
Note: This table provides general information and examples. Specific caps, phase-outs, and rules can change. Always verify current laws with your state's tax department or a financial advisor. "Full Contribution" indicates no specific state dollar limit, though general gifting limits and federal tax laws still apply.
Navigating Specific State Rules and Maximizing Your Benefits
The world of 529 plans and state tax benefits is certainly nuanced, but with a bit of research, you can absolutely make the most of what's available to you. Don't let the complexity deter you from exploring these valuable savings tools.
What to Do If Your State Offers No 529 Tax Benefit
If you live in a state like California or New Jersey that doesn't offer a state income tax deduction or credit for 529 contributions, or one of the states without an income tax, you might feel a little left out. But don't despair! The federal tax benefits alone make 529 plans a powerful savings vehicle. Tax-free growth and tax-free withdrawals for qualified expenses are a huge advantage.
In these situations, your strategy should pivot to finding the 529 plan with the best investment options, lowest fees, and a strong track record, regardless of which state sponsors it. Many people living in states without benefits often choose popular, low-cost plans from other states, such as the Utah Educational Savings Plan (UESP) or New York's 529 College Savings Program. These plans are open to residents of any state. Tools from financial analysis sites like SmartAsset can be incredibly helpful here, allowing you to compare different plans side-by-side on factors like fees, investment performance, and underlying fund options.
Considering "Any State's Plan" vs. "Home State Plan"
The "any state's plan" benefit is a major perk, as it allows you to shop around for the best plan without losing your state tax incentive. If your state offers this (like Arizona, Kansas, Missouri, Montana, Colorado, or Illinois), you have a lot of flexibility. You can compare various plans, looking at things like:
- Investment Options: Do they offer diverse portfolios, age-based options, or static portfolios that align with your risk tolerance?
- Fees: Are the administrative and underlying fund fees competitive?
- Customer Service: Is the plan administrator responsive and easy to work with?
However, if your state's tax benefit is contingent on contributing to its own 529 plan, that's usually the financially savvy move. The immediate tax savings often outweigh slight differences in fees or investment performance from an out-of-state plan. The key here is to run the numbers: calculate your potential state tax savings from using your home state's plan versus the potential gains (or savings from lower fees) of an alternative plan. For many, the guaranteed state tax break is a clear winner.
Don't Forget About Rollovers and Portability
Life happens, and sometimes you might move states, or decide a different 529 plan would better suit your needs. The good news is that 529 plans are generally portable. You can roll over funds from one 529 plan to another 529 plan for the same beneficiary once every 12 months without incurring federal taxes or penalties. If you move from a state with a specific plan requirement to one with an "any plan" benefit, or vice versa, this can be a valuable option. For instance, if you were living in Michigan and contributing to their MI 529 plan for the deduction, then moved to Pennsylvania, you could keep your Michigan plan or roll it over into a new one and still benefit from Pennsylvania's full deduction for contributions to any plan.
Remember, changing beneficiaries is also an option if your original beneficiary decides not to pursue higher education. You can change the beneficiary to another eligible family member without penalty, including siblings, first cousins, nieces, or nephews.
When it comes to filing your taxes, especially if you're utilizing 529 deductions or credits, tax software like TurboTax can guide you through the process. It's designed to help you navigate state-specific forms and ensure you claim all eligible benefits correctly. Learning How to Lower Your State Income Tax can involve maximizing all available deductions and credits, and 529 contributions are a significant piece of that puzzle for many families.
Disclaimer
Please note that tax laws are complex and subject to change by state legislatures. The information provided in this article is for informational purposes only and does not constitute tax or financial advice. Always consult with a qualified tax professional or financial advisor for personalized advice regarding your specific situation and the most current tax laws in your state.