Does My State Tax Social Security Benefits?
It's a common worry for many nearing or in retirement: will your hard-earned Social Security benefits be taxed? The short answer, frustratingly, is "it depends." Navigating the complexities of state income tax on Social Security can feel like trying to solve a puzzle with missing pieces, especially when rules change frequently. This comprehensive guide will clear up the confusion, revealing which states tax Social Security benefits, how those taxes are applied, and what recent legislative shifts mean for your retirement planning.
The Federal Layer: Understanding How Social Security is Taxed Nationally
Before we even dive into state-specific rules, it's absolutely crucial to understand that your Social Security benefits might already be subject to federal income tax. This often comes as a surprise to many, who assume their benefits are entirely tax-free. The federal government uses a calculation called "provisional income" to determine if and how much of your Social Security is taxable. It's a foundational piece of the puzzle, and states that do tax Social Security often start with this federally taxable amount.
Understanding the Provisional Income Rule
The IRS has a specific formula for determining your provisional income. It's not just your Social Security; it's a combination of several income sources. Here’s how it generally works: take your modified adjusted gross income (MAGI) – which is your AGI before any Social Security benefits are considered – then add any tax-exempt interest (like interest from municipal bonds) and 50% of your Social Security benefits. That total is your provisional income.
Let's imagine you're a single filer. If your provisional income falls between $25,000 and $34,000, up to 50% of your Social Security benefits could be subject to federal income tax. If it exceeds $34,000, then up to 85% of your benefits could be taxed. For those married filing jointly, these thresholds are higher: between $32,000 and $44,000, up to 50% is taxable, and above $44,000, up to 85% could be taxed. This means even if you're not earning a massive salary in retirement, other income streams can push you into the federal taxation bracket.
The 85% Limit: What It Really Means
When people hear "up to 85% of your Social Security benefits can be taxed," it often causes a wave of panic. But let’s clear the air: this doesn't mean you'll automatically pay tax on 85% of your benefits. It simply means that at most, 85% of your Social Security benefits will be included in your taxable income. The actual percentage depends entirely on your provisional income level.
For instance, if you're a single filer with a provisional income of exactly $30,000, a portion of your benefits will be taxed, but it won't be the full 85%. You'd fall into the 50% bracket. Only if your provisional income is over $34,000 (single) or $44,000 (married filing jointly) would you even potentially hit the 85% threshold. It’s a sliding scale, designed to capture more tax from higher earners in retirement, while generally shielding those with lower incomes. Keep in mind, this is just the federal picture; states then add another layer of complexity.
The Evolving Landscape: States That Tax Social Security (and Those That Used To)
Understanding state income tax on Social Security is where things get truly tricky because there's no national standard. Each state has its own set of rules, and these rules are constantly changing. What was true last year might not be true today, as states evaluate their tax policies to attract retirees or balance their budgets. It's a dynamic situation that demands staying informed.
The Current List for 2026
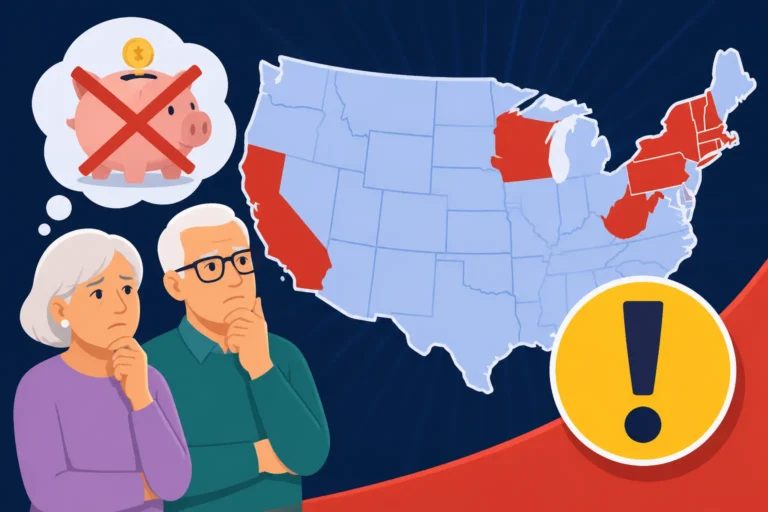
For 2026, the number of states that tax Social Security benefits has continued to shrink, reflecting a broader trend towards making states more retiree-friendly. As of our current understanding, the following states may still tax a portion of your Social Security benefits, often based on income thresholds similar to or different from the federal ones:
- Colorado: This state provides an income exclusion for Social Security benefits, but it’s not universal. For taxpayers age 65 and older, if your total income is below a certain threshold (which adjusts annually), your benefits may be fully exempt. If your income exceeds that, a portion could be taxed.
- Connecticut: Known for having higher income thresholds before taxing Social Security. For single filers, if your adjusted gross income (AGI) is below $75,000, your benefits are exempt. For those married filing jointly, the threshold is $100,000. Surpass those numbers, and a percentage of your benefits become taxable.
- Minnesota: This state has a subtraction for Social Security benefits, but it's largely income-dependent. Higher-income retirees will find more of their Social Security benefits subject to state income tax, while those with more modest incomes will see a larger reduction or full exemption.
- Montana: Montana taxes Social Security benefits to the extent they are federally taxable, but it does offer a small exclusion amount that can reduce the taxable portion for some. This can make it tricky to calculate without careful attention to detail.
- New Mexico: This state has been a bit of a rollercoaster for retirees, but for 2024 and beyond, they've introduced much higher income thresholds for Social Security exemptions. For single filers, benefits are fully exempt if your AGI is below $100,000. For joint filers, it's $150,000. If you're below those, you're in the clear.
- Rhode Island: Similar to Connecticut, Rhode Island exempts Social Security benefits for those whose federal AGI falls below certain thresholds. For single filers, the AGI threshold for exemption is around $95,850, and for joint filers, it's about $119,825.
- Utah: While Utah taxes some retirement income, it offers a nonrefundable retirement income tax credit that can significantly offset or even eliminate the state tax on Social Security benefits for lower to moderate-income individuals.
- Vermont: This state generally follows federal rules regarding Social Security taxation, but it does provide a partial exemption for individuals with lower AGIs (e.g., up to $50,000 for single filers, $60,000 for joint). Beyond these, a portion of your benefits could be taxed.
Each of these states presents its own nuances, which is why personalized advice or a robust tax calculation tool like one offered by SmartAsset can be invaluable.
Recent Repeals and Phase-Outs (Why This List Shrinks)
The good news for retirees is that several states that previously taxed Social Security have recently repealed or are phasing out these taxes. This is a significant trend, as states compete to attract retirees and their spending power.
- Kansas, Missouri, and Nebraska: These three states notably repealed their Social Security income tax for tax year 2024 and beyond. This means if you're a resident of Kansas, Missouri, or Nebraska, your Social Security benefits will no longer be subject to state income tax, regardless of your income level. This is a huge relief for many retirees in the Midwest, and you can learn more about the specifics in our detailed guide on the Missouri, Kansas & Nebraska SS Tax Repeal (2024).
- West Virginia: This state has been phasing out its Social Security tax over several years and will have fully repealed it for the 2026 tax year. This gradual reduction provided relief to many, and the full repeal makes West Virginia a more attractive destination for retirees. We cover this in depth in our article on West Virginia Social Security Tax Phase-Out (2026).
These changes highlight how crucial it is to stay updated on state tax laws. A state that taxed benefits last year might be tax-free for Social Security this year or next.
States That Don't Tax Social Security (The Majority!)
The vast majority of U.S. states do not tax Social Security benefits. This is a huge advantage for retirees looking to maximize their income in retirement. These states fall into two main categories: those that don't have a state income tax at all, and those that have an income tax but specifically exempt Social Security benefits.
A Welcome Relief: The "No Income Tax" States
The most straightforward way to avoid state income tax on your Social Security benefits is to live in one of the nine states that have no state income tax whatsoever. If a state doesn't tax income, it logically follows that it won't tax Social Security benefits either. These states often make the list of the Most Tax-Friendly States for Retirees 2027 and include:
- Alaska: Known for its Permanent Fund Dividend, Alaska has no state income tax or statewide sales tax.
- Florida: A perennial favorite for retirees, Florida boasts no state income tax, making it an attractive option for those looking to stretch their retirement dollars further. Our guide, Does Florida Tax Retirement Income?, dives deeper into its policies.
- Nevada: Famous for its vibrant cities and natural beauty, Nevada also offers residents the benefit of no state income tax.
- South Dakota: A more rural option, South Dakota also has no state income tax.
- Tennessee: While it used to tax interest and dividends (the "Hall Tax"), Tennessee fully repealed its state income tax, making it a state with no broad-based income tax. You might be interested in knowing Does Tennessee Have State Income Tax?.
- Texas: Everything is bigger in Texas, including the lack of state income tax. This makes it a popular destination for many. You can explore Does Texas Tax Retirement Income? for more details.
- Washington: Despite having a capital gains tax for high earners, Washington state has no general income tax.
- Wyoming: The Equality State also joins the ranks of those without a state income tax.
- New Hampshire: While New Hampshire doesn't have a general income tax, it traditionally taxed interest and dividends above a certain threshold. However, this tax is being phased out and will be fully repealed by 2027. So, for 2026, it's effectively a state with no broad income tax for most. For more on the specific changes, check out New Hampshire Interest & Dividends Tax Repeal.
Choosing one of these states can significantly impact your retirement finances, particularly if a large portion of your income comes from Social Security. You can find a complete overview in our article, States With No Income Tax (2026 Full List).
States with Specific Exemptions or Deductions
Beyond the no-income-tax states, many other states do have a state income tax but have specific provisions that exempt Social Security benefits from taxation, either fully or partially, regardless of income level or with very generous thresholds. This means you might pay state income tax on other forms of income, but your Social Security check remains untouched.
These states generally recognize the importance of Social Security as a lifeline for many retirees and choose not to add an additional tax burden on these benefits. This includes a broad spectrum of states from Alabama to Wisconsin. For instance, states like Pennsylvania and Illinois are known for being very friendly to retirees when it comes to pension and Social Security income, often exempting these entirely from state income tax. Even states with higher income tax rates like Georgia offer significant retirement income exclusions, such as the Georgia $65,000 Retirement Exclusion (2026), which can cover a substantial portion of most retirees' income, including Social Security. Similarly, New Jersey offers a substantial New Jersey Retirement Income Exclusion, providing relief for many seniors.
The exact rules can vary; some states might exempt 100% of federally taxable Social Security, while others might offer a large deduction or credit that effectively eliminates the tax for most residents. This is why it’s always wise to consult your state's Department of Revenue website or resources like SmartAsset to understand the specific rules that apply to your situation, as they can sometimes change year by year.
Here’s a simplified table illustrating the current status of Social Security taxation by state in 2026, keeping in mind that "taxed" often means "may be taxed above certain income thresholds."
| State Category | States Included (Examples for illustration) | General Rule for Social Security Benefits |
|---|---|---|
| No State Income Tax | Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, Wyoming, New Hampshire (no general income tax) | Not Taxed. No state income tax means no tax on Social Security benefits. |
| States with Full Exemption | Alabama, Arizona, Arkansas, California, Delaware, Georgia, Hawaii, Idaho, Illinois, Indiana, Iowa, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Michigan, Mississippi, New Jersey, New York, North Carolina, North Dakota, Ohio, Oklahoma, Oregon, Pennsylvania, South Carolina, Virginia, Wisconsin | Not Taxed. These states have an income tax but fully exempt Social Security benefits, often regardless of income level. (Some may have small exclusions but generally lead to no tax for most). |
| States that May Tax (with thresholds/subtractions) | Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, Vermont | May be Taxed. These states tax Social Security benefits, but often with generous income thresholds, subtractions, or credits that can significantly reduce or eliminate the tax for many retirees. Higher earners are more likely to see a portion taxed. (e.g., CT: AGI > $75k/$100k; NM: AGI > $100k/$150k for full exemption). |
Note: This table provides a general overview. Specific income thresholds, phase-outs, and credits can change, and it's essential to verify details with official state tax agencies or a qualified tax professional.
Planning for State Social Security Taxes in Retirement
Retirement planning isn't just about saving enough money; it's also about strategically managing that money to minimize your tax burden. For many, Social Security benefits form a significant portion of their retirement income, so understanding how these benefits are taxed (or not taxed) at the state level is a critical piece of the puzzle. It can genuinely impact your quality of life in your golden years.
Understanding Your Personal Tax Situation
Every retiree's financial situation is unique. Your total income, marital status, and even the source of your other retirement funds (like pensions, 401(k)s, or IRAs) all play a role in how your Social Security benefits might be taxed. For example, if you live in a state that taxes Social Security based on federal adjusted gross income (AGI) thresholds, and you have substantial income from other sources, you might find yourself owing state tax on your benefits.
It's not just about Social Security in isolation. You need to look at your entire income picture. If you're still asking Do Retirees Pay State Income Tax?, the answer is almost always yes on some forms of income, even if Social Security is exempt. Some states are very friendly to all retirement income, while others might tax pensions but not Social Security, or vice-versa. Tools and calculators, like those provided by financial services companies, can help you estimate your total state tax liability based on your projected retirement income. Many people find it useful to consult with a financial advisor or tax professional to get a clear picture tailored to their specific circumstances.
Strategies to Potentially Minimize Your Tax Burden
Once you understand how your state (or potential future state) handles Social Security taxation, you can explore strategies to potentially lower your overall tax burden.
One popular strategy, especially for those who anticipate higher income in retirement, is Roth conversions. Converting traditional IRA or 401(k) funds to a Roth account now means you pay taxes on those contributions today, but qualified withdrawals in retirement are generally tax-free. This can reduce your future adjusted gross income (AGI) and, consequently, your provisional income, which might help keep your Social Security benefits from being taxed at both federal and state levels.
Another significant consideration is where you choose to live in retirement. Moving to a state that doesn't tax Social Security benefits or other forms of retirement income can lead to substantial savings over decades. This is a common motivation for retirees who are actively considering Moving to a Tax-Friendly State for Retirement. However, it's not just about income tax; you also need to weigh other taxes like property taxes and sales taxes, as well as the overall Cost of Living vs Taxes by State. For instance, while Florida has no state income tax, property taxes in some areas can be quite high. It's about finding the right balance that suits your financial and lifestyle goals.
Furthermore, being mindful of your withdrawal strategies from various retirement accounts can impact your AGI and provisional income. Spreading out withdrawals, or leveraging different types of accounts, can help keep your income below state-specific thresholds for Social Security taxation. This complex interplay of federal and state rules means that an informed, proactive approach to your retirement income strategy is always the best defense against unexpected tax bills. For a deeper dive into the nuances of retirement income taxation across all 50 states, our How Each State Taxes Retirement Income (50-State Guide) offers extensive details.
Recent State Tax Cuts and Future Outlook
The trend towards lowering taxes on Social Security benefits is part of a broader movement among states to make themselves more attractive, particularly to retirees. As the population ages, states recognize the economic power of older residents, who often have stable incomes and contribute significantly to local economies through spending.
Many states are continually evaluating their tax structures, and tax cuts are often a popular legislative initiative. This could mean further adjustments to income thresholds, new exemptions, or even complete repeals of Social Security taxes in states where they currently exist. For example, some states are implementing State Income Tax Cuts & Changes for 2026 which could indirectly or directly benefit retirees. Keeping an eye on these legislative developments is crucial, as what applies today may change tomorrow. Resources like the SmartAsset tax map can be helpful for staying current on the tax landscape, as they often update information in real-time as state laws evolve.
Disclaimer
Please remember that tax laws are complex and subject to change. The information provided in this guide is for informational purposes only and does not constitute financial or tax advice. We highly recommend consulting with a qualified tax professional or financial advisor for personalized advice regarding your specific tax situation.