Moving to a Tax-Friendly State for Retirement
The dream of a comfortable retirement can feel a little out of reach when you're constantly worried about how much of your hard-earned savings and income will be gobbled up by state taxes. Many folks find themselves eyeing the map, wondering if a change of scenery could mean a more financially secure golden age. This comprehensive guide is here to walk you through everything you need to know about making that move to a tax-friendly state for retirement, helping you maximize your nest egg and truly enjoy your later years.
Understanding What "Tax-Friendly" Really Means for Retirees
When you hear the term "tax-friendly," it’s easy to immediately think "no state income tax!" And while that's certainly a huge part of the puzzle for many, it's really just one piece. A truly tax-friendly state for retirees takes into account all the ways your money might be taxed, not just your pension or 401(k) distributions. It's about looking at the big picture to see where your overall tax burden will be the lightest.
Beyond Just Income Tax: A Holistic View
Imagine you move to a state with no income tax, only to find that your property taxes double, or the sales tax on every purchase feels exorbitant. That's a real eye-opener, isn't it? Many retirees, especially those on a fixed income, realize quickly that what they save in income tax might be lost in other areas. It’s critical to consider the full spectrum of state and local taxes that will impact your budget.
For instance, property taxes can vary wildly, even within the same state. A beachfront property in Florida might have a much higher property tax bill than a similar home inland, even though Florida boasts no state income tax. Sales taxes are another big one. If you're planning on spending a fair bit on goods and services, a high sales tax rate can really add up. Some states also have excise taxes on specific goods like fuel or tobacco, or even significant vehicle registration fees. You'll want to dig into the details on these to avoid any unwelcome surprises. Think about how your spending habits will align with the tax structure of a potential new state. Do you plan to travel extensively, or will you be spending more time at home, perhaps renovating or gardening? These lifestyle choices can dictate which hidden taxes will hit your wallet the hardest.
Domicile vs. Statutory Residency and Why It Matters
This is where things can get a little tricky, and it's something many people overlook until it's too late. When you move to a new state, you're not just changing your mailing address; you're often looking to change your tax domicile. Your domicile is essentially your true home, the place you intend to return to whenever you're away. It's where your principal residence is, where you register to vote, get your driver's license, and generally conduct your life. For tax purposes, your domicile determines which state has the primary right to tax your worldwide income.
Then there's statutory residency. This is a legal status often determined by how many days you spend in a particular state, regardless of your intent to make it your permanent home. For example, states like New York and California are notorious for their aggressive residency rules. Even if you claim another state as your domicile, if you spend more than 183 days (the common threshold, but it varies) in one of these states and maintain a "permanent place of abode" there, you could still be considered a statutory resident and subject to their income taxes. This is a huge concern for "snowbirds" or anyone who splits their time between states.
To truly establish a new domicile and ensure your old, high-tax state doesn't come calling, you need to create a clear paper trail. This includes changing your driver's license, registering your vehicles, registering to vote, opening bank accounts, and updating your will and estate documents in your new state. It's about demonstrating a clear intent to make that new state your permanent home. Getting this wrong can lead to costly residency audits and the dreaded double taxation, so understanding the nuances of Domicile vs Statutory Residency is incredibly important.
Key Retirement Income Types and State Taxation
The way states tax different types of retirement income is a primary factor for many retirees. There’s a huge spectrum, from states that tax virtually nothing to those that take a slice out of almost every income stream. This is where a little upfront research can save you a bundle.
Social Security Benefits: The Eight States That Still Tax It
It might seem unfair that states would tax your Social Security benefits, especially after you've paid into the system for decades, but it's a reality in a few places. While the federal government taxes a portion of Social Security benefits for many recipients (depending on their combined income), most states do not follow suit.
However, as of recent updates, there are still a handful of states that tax Social Security benefits. These include Colorado, Connecticut, Kansas, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont. It’s worth noting that some of these states offer significant exemptions or deductions based on income level, so not every retiree in these states will end up paying taxes on their Social Security. For instance, Colorado offers a substantial deduction for senior citizens. Kansas, Missouri, and Nebraska have all recently moved to repeal their Social Security taxes or phase them out, reflecting a growing trend of states trying to become more appealing to retirees. For a full breakdown, you'll want to check out our detailed guide on States That Don't Tax Social Security 2026.
Pensions, 401(k)s, and IRA Withdrawals
This is often the largest component of retirement income for many people, and state taxation here varies wildly. Some states are incredibly generous, completely exempting all types of retirement distributions from state income tax. Others treat pension and 401(k)/IRA withdrawals just like any other income, taxing them at your standard state income tax rate.
For example, states like Illinois and Mississippi completely exempt all qualified retirement income from state income tax. This means your private pension, public pension, 401(k), and IRA withdrawals will pass through without a state tax bill. On the other hand, states like California and New York tax these distributions as regular income. Many states fall somewhere in the middle, offering partial exemptions or deductions. Some might exempt military retirement pay, or offer a specific income exclusion for certain age groups or income levels. For instance, Pennsylvania broadly exempts retirement income from its flat income tax, which is a huge draw for many. To get a comprehensive view, our article on States That Don't Tax Pensions 2026 and States That Don't Tax 401(k) & IRA Withdrawals can be immensely helpful.
Other Income Sources: Capital Gains, Interest, and Dividends
Beyond your regular retirement distributions, many retirees rely on income from investments like stocks, bonds, mutual funds, and real estate. This income often comes in the form of capital gains, interest, and dividends.
- Capital Gains: Most states with an income tax will tax capital gains, treating them much like regular income. However, some states differentiate between short-term and long-term capital gains, or offer specific exemptions. States without an income tax generally don't tax capital gains. Washington state is a unique case; while it generally has no income tax, it does levy a 7% capital gains tax on the sale or exchange of long-term capital assets over a certain threshold.
- Interest and Dividends: Again, states with an income tax typically include interest and dividend income in their taxable base. New Hampshire is a notable example here; historically, it only taxed interest and dividends, but it's currently phasing out this tax, with full repeal expected in 2026. This is a significant change, making New Hampshire even more attractive for retirees. Other states that don't have a broad income tax generally won't tax these.
Understanding how each state approaches these investment income streams is crucial, especially if your retirement strategy involves living off your investment portfolio. Consulting resources like SmartAsset can provide you with detailed state-by-state breakdowns, which can be invaluable when planning your move.
| State Type | Social Security Taxed | Pension/401(k)/IRA Taxed | Capital Gains/Interest/Dividends Taxed | Key Takeaway for Retirees |
|---|---|---|---|---|
| No Income Tax States | No | No | No (with exceptions like WA capital gains) | Generally the most straightforward low-tax option. |
| Income Tax with Exemptions | Maybe (with limits) | Often exempted/deducted | Often taxed (with deductions/exemptions) | Requires careful review of specific exclusions for seniors. |
| Full Income Tax | Yes (8 states) | Yes | Yes | Highest potential tax burden for most income types. |
Top States Generally Considered Tax-Friendly for Retirees
So, where are these mythical tax havens for retirees? While "tax-friendly" is subjective and depends heavily on your individual income and assets, some states consistently rank high due to their overall lighter tax burdens on retirees.
The No-Income-Tax Havens
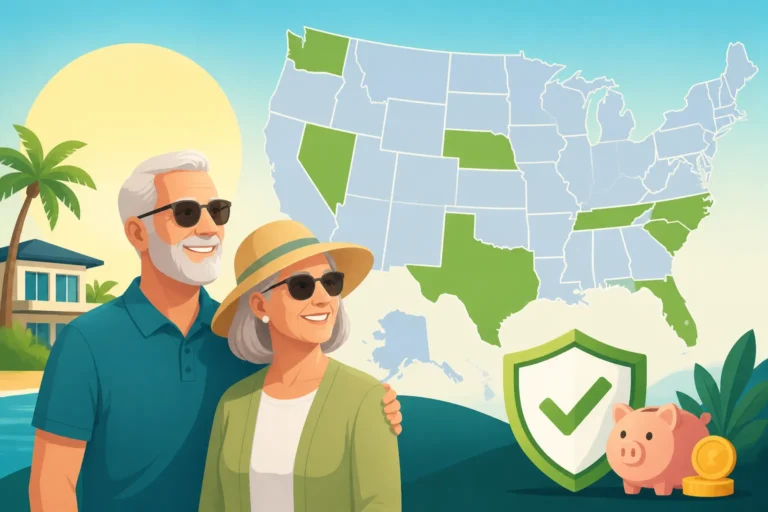
These states are often the first ones people think of when considering a tax-friendly retirement. Nine states currently have no state income tax on wages, salaries, or retirement income: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. New Hampshire previously taxed only interest and dividends, but it is phasing out even that by 2026, essentially joining the no-income-tax club for most purposes.
- Florida: A perennial favorite for retirees, Florida truly lives up to its reputation. No state income tax means your pensions, 401(k) withdrawals, and Social Security benefits are completely free from state taxation. However, you'll still encounter sales tax (6% statewide, plus local options) and property taxes, which can be high in popular coastal areas. Establishing How to Establish Florida Domicile is a common goal for many seeking sunshine and tax savings.
- Texas: Similar to Florida, Texas boasts no state income tax, making it very attractive for retirees with substantial retirement income. Property taxes, however, are among the highest in the nation. It's a trade-off many are willing to make, especially if they value a larger home or land, but it requires careful budgeting.
- Nevada: Another no-income-tax state, Nevada is popular for its dry climate and access to outdoor activities. Like Texas, it relies heavily on sales and property taxes, and tourist-heavy areas can have significant sales tax rates.
- Tennessee: No income tax on wages or salaries, and its prior tax on interest and dividends (the "Hall Tax") has been fully phased out. This makes Tennessee an excellent choice for retirees, offering a lower overall tax burden compared to many other states.
- Washington: While Washington has no state income tax, be aware of its capital gains tax mentioned earlier. For retirees with significant investment portfolios, this could still be a consideration. Property and sales taxes are also substantial.
If you're looking for the complete rundown, check out our guide on States With No Income Tax (2026 Full List). But remember, no income tax doesn't mean no taxes. You'll need to weigh the other tax burdens carefully.
States with Generous Exemptions and Deductions
Beyond the no-income-tax states, many other states with income taxes have carved out significant tax breaks specifically for retirees. These often come in the form of generous exemptions or deductions for Social Security, pensions, or other retirement income.
- Pennsylvania: As mentioned, Pennsylvania is very popular among retirees because it generally exempts all qualified retirement income (pensions, 401(k), IRA distributions) from state income tax, regardless of income level. Its flat income tax rate of 3.07% only applies to earned income and certain other categories, making it very attractive for those living off retirement accounts.
- Mississippi: Another standout, Mississippi completely exempts all retirement income, including Social Security, private and public pensions, and withdrawals from IRAs and 401(k)s. This makes it a surprisingly tax-friendly state for many retirees, despite having a state income tax.
- Illinois: This state has a flat income tax rate (currently 4.95%) but offers a huge benefit: all retirement income, including Social Security, pensions, and 401(k)/IRA distributions, is exempt from state income tax. This makes it a top choice for many, even with a relatively high property tax burden in some areas.
- Georgia: This Southern state offers a significant exclusion for retirement income. For individuals aged 62 or older, up to $65,000 per person of retirement income (pensions, annuities, interest, dividends, net rentals, capital gains, IRAs, 401(k)s, etc.) is exempt from state income tax. This can effectively eliminate state income tax for many retirees.
Other states like Alabama, Arkansas, and New Jersey also offer various exclusions or deductions that can make them quite friendly for retirees, depending on your income level and the types of retirement income you receive. It's truly a state-by-state, and sometimes even county-by-county, puzzle to solve. SmartAsset's tools and analyses are great for helping navigate these complex state tax landscapes for retirees. If you want to dive deeper into how various states treat different income streams, take a look at our guide, How Each State Taxes Retirement Income (50-State Guide), which offers a fantastic resource for comparing options.
Potential Pitfalls and Considerations When Moving
While the allure of lower taxes is powerful, a successful retirement move requires looking beyond just the tax rates. You need to consider how a new state will impact your overall financial health and, more importantly, your quality of life.
The Cost of Living Trade-Off
Saving money on taxes is great, but what if the cost of everything else goes up? This is a crucial question. Some states with low income taxes might have higher costs of living in other areas, negating some of those tax savings. For instance, while California has a high income tax, its property taxes are relatively low compared to some other states. Conversely, a state with no income tax might have significantly higher property taxes, sales taxes, or even elevated utility costs.
Think about everyday expenses: groceries, gasoline, utilities, insurance (home, auto, health), and entertainment. A lower cost of living might mean your retirement savings simply stretch further, allowing you to enjoy more experiences or have a larger financial cushion. Tools that compare the Cost of Living vs Taxes by State can be incredibly insightful here. It's worth running a detailed budget analysis for any prospective state, not just focusing on one tax category. Don't forget that housing costs can dramatically alter your overall financial picture, whether you plan to buy or rent.
Healthcare Costs and Quality of Life
For retirees, access to quality healthcare at an affordable price is often paramount. Healthcare costs can be a significant drain on retirement funds, and these costs can vary considerably from state to state. Research hospitals, specialist availability, and average insurance premiums in your potential new home. Even within a state, rural areas might have fewer healthcare options compared to metropolitan areas.
Beyond financial considerations, think about your desired quality of life. Are you looking for a vibrant city with cultural amenities, or a quiet rural retreat? What about climate, proximity to family, recreational opportunities, and community engagement? Moving to a state solely for tax benefits, only to find you're unhappy with the lifestyle, can be a much more costly mistake than paying a bit more in taxes. For example, some retirees might prioritize being near their grandchildren, even if it means staying in a state with higher taxes. Others might crave a specific climate or outdoor activity that only certain states offer, regardless of the tax implications.
Establishing New Residency and Avoiding Residency Audits
Once you've chosen your dream tax-friendly state, the work isn't over. You need to formally establish your new residency – and convincingly so – to avoid your old state claiming you still owe them taxes. This process is about creating a clear, undeniable trail of intent to live in your new state permanently.
Here are some key steps, which can also be found in our guide on How to Change Your State Residency for Taxes:
- Update your driver's license and vehicle registration: This is usually one of the first and most tangible steps.
- Register to vote: Voting in your new state solidifies your intent.
- Change your mailing address: Forward your mail and update all your financial accounts, subscriptions, and important contacts with your new address.
- Open bank accounts: Use local banks or credit unions in your new state.
- Update estate documents: Your will, trusts, and other legal documents should reflect your new state of residence.
- Sever ties with your old state: Close old bank accounts, sell your previous home (or lease it out with a clear rental agreement), and end memberships to clubs or organizations there.
- Spend sufficient time in your new state: This is crucial, especially if you're coming from states with aggressive residency audit policies like California or New York. Keep records of your travel to demonstrate you meet the physical presence requirements of your new domicile. Our article on What Triggers a State Residency Audit? is a must-read for anyone considering a move.
It's not enough to simply say you've moved; you need to prove it with actions and documentation. Many states are vigilant about retirees moving away to avoid taxes, and they will look for any reason to claim you still owe them. This can become even more complex if you plan on being a "snowbird" and splitting your time between two states, which may lead to Dual State Residency Can You Be Taxed Twice?.
The Moving Process: Steps to Take Before and After
Making a move in retirement is a big undertaking, emotionally and logistically. Having a clear plan can significantly reduce stress and ensure you don't miss any critical steps, especially when it comes to the financial and tax implications.
Financial Planning and Professional Advice
Before you even pack your first box, a thorough financial review is in order. This isn't just about looking at tax rates but about understanding your entire financial picture. How much income will you have from Social Security, pensions, 401(k)s, IRAs, and investments? What are your expected expenses in your new state, including housing, healthcare, and daily living?
This is where consulting with a financial advisor or a tax professional specializing in multi-state taxation for retirees becomes invaluable. They can help you:
- Model different scenarios: A good advisor can help you project your tax burden and overall financial health in several potential states. This can go beyond generic advice and provide personalized insights based on your specific income streams and asset levels. SmartAsset offers tools that can connect you with qualified financial advisors who can provide this kind of tailored guidance.
- Understand state-specific rules: Tax laws are complex and constantly changing. A professional will have up-to-date knowledge on specific exemptions, deductions, and credits available to retirees in various states.
- Navigate residency requirements: They can offer clear, actionable steps to properly establish domicile and avoid common pitfalls that lead to residency audits.
- Plan your withdrawals: Depending on how your new state taxes different income types, a professional can advise on the most tax-efficient way to draw down your retirement accounts. For example, if a state offers a large exclusion for pension income but fully taxes IRA withdrawals, you might strategically prioritize pension distributions.
Getting expert advice is an investment that can save you significant money and headaches down the road. It ensures you're making an informed decision, not just an impulsive one driven by a single tax rate.
Practical Steps for a Smooth Transition
Once the financial planning is done and you've chosen your new state, it's time for the practicalities of moving. This involves a lot of logistics, but a systematic approach can make it much smoother.
- Decluttering and downsizing: Retirement is often a time to simplify. Consider what you truly need and want to bring. Donating, selling, or gifting items can make the move easier and potentially even provide a small income boost.
- Researching moving companies: Get multiple quotes, read reviews, and understand what's included in each service. For larger moves, consider companies like United Van Lines or Atlas Van Lines. For smaller moves or those who prefer a DIY approach, PODS containers can be a flexible option.
- Setting up utilities and services: Before you arrive, arrange for electricity, water, internet, and other essential services to be connected at your new home.
- Finding new doctors and healthcare providers: This is particularly important for retirees. Transfer medical records well in advance and ensure you have prescriptions refilled before the move.
- Getting to know your new community: Once settled, actively seek out new social connections, clubs, and activities. This helps establish your new life and reinforce your intent to live there permanently. It’s not just about taxes; it’s about making a happy, fulfilling life.
- Updating your federal tax information: Ensure your W-4 forms for any ongoing income sources reflect your new state. For estimated taxes, ensure you adjust for state tax implications.
Remember that moving is a process, not a single event. It takes time to settle in, meet new people, and adjust to your new surroundings. Be patient with yourself and embrace the adventure. The goal is a financially secure and personally fulfilling retirement, and choosing the right state is a huge step in that direction.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.