Annuity Taxation by State
Navigating the world of retirement income can feel like wading through quicksand, especially when you're trying to figure out how annuities fit into your state tax picture. It’s a common frustration to have saved diligently, only to feel blindsided by unexpected tax implications when you start receiving those hard-earned payouts. This guide is here to shed light on how different states approach annuity taxation, helping you understand your obligations and empower you to plan more effectively for your financial future.
Understanding What Annuities Are for Tax Purposes
Before we dive into the nitty-gritty of state taxation, let’s make sure we're all on the same page about what an annuity actually is from a tax perspective. It's not just a simple savings account; it's a contract, often with an insurance company, where you make payments (either a lump sum or a series of payments) in exchange for future income. The real kicker for taxes comes into play because annuities grow tax-deferred, meaning you don't pay taxes on the investment gains until you start withdrawing money.
The Basics: Premiums, Growth, and Payouts
Think of an annuity as having three main phases: the accumulation phase, where your money goes in and ideally grows; the annuitization phase, where that growth starts turning into regular income payments; and the distribution phase, which is when those payments hit your bank account. The money you put in, your "cost basis" or premiums, has already been taxed (unless it was from a qualified retirement plan). It's the growth portion that gets the special tax treatment – or, more accurately, the deferred tax treatment.
When you start receiving payments, a portion of each payment is considered a return of your original principal (which isn't taxed again), and another portion is considered the taxable earnings. This separation is key to understanding why annuities aren't taxed quite like a regular paycheck or even some other retirement distributions. It's a structured return of capital plus the accrued interest or gains.
Qualified vs. Non-Qualified Annuities
The tax rules for your annuity largely depend on whether it's a "qualified" or "non-qualified" annuity. This distinction is really important for how you'll be taxed at both the federal and state levels.
A non-qualified annuity is one you funded with after-tax dollars – money that has already been subject to income tax. Because you've already paid taxes on the principal, only the earnings portion of your withdrawals will be taxed when you receive them. This is where that "exclusion ratio" comes into play, which we’ll discuss shortly. Many people choose non-qualified annuities as a way to supplement other retirement savings, especially if they've maxed out their contributions to 401(k)s or IRAs.
On the other hand, a qualified annuity is purchased with pre-tax money, typically within a retirement plan like a 401(k), 403(b), or an IRA. Since you haven't paid taxes on any of the money yet – neither the contributions nor the earnings – all withdrawals from a qualified annuity are fully taxable as ordinary income. This is essentially the same way that distributions from a traditional IRA or 401(k) are taxed. It's a big difference, so knowing which type of annuity you have is your first step in understanding its tax implications.
Immediate vs. Deferred Annuities and Their Tax Implications
Beyond the qualified/non-qualified distinction, the type of annuity payout schedule you choose also significantly impacts how your state taxes will be applied. Generally, annuities fall into two broad categories: immediate and deferred. Each has its own rhythm when it comes to the flow of income and, consequently, the timing of tax payments.
Immediate Annuities: Income Now, Tax Implications Now
An immediate annuity, sometimes called a Single Premium Immediate Annuity (SPIA), is pretty straightforward. You hand over a lump sum of money, and in return, the insurance company starts sending you regular income payments almost immediately – usually within a year. These payments are often guaranteed for a set period, like 10 or 20 years, or for the rest of your life.
For tax purposes, each payment you receive from a non-qualified immediate annuity is treated partly as a return of your principal (your original investment) and partly as taxable interest earnings. The Internal Revenue Service (IRS) provides a formula to determine this split, known as the "exclusion ratio." This ratio helps you figure out what percentage of each payment is tax-free return of principal and what percentage is taxable income. States generally follow this federal treatment for the income portion. If it's a qualified immediate annuity, meaning it was funded with pre-tax dollars (like from a rollover IRA), then 100% of each payment is taxable income, just like any other withdrawal from a traditional retirement account.
Deferred Annuities: Growth First, Taxes Later
Deferred annuities are designed for long-term growth. You pay premiums (either a lump sum or over time), and your money grows tax-deferred until you decide to start taking withdrawals, often in retirement. When you eventually choose to "annuitize" the contract, it converts into a stream of income payments, much like an immediate annuity. Or, you can take lump-sum withdrawals.
With a non-qualified deferred annuity, if you take withdrawals before annuitization, the IRS uses a "LIFO" (Last-In, First-Out) rule. This means any money you pull out is considered to come from the earnings first until all the gains have been withdrawn. Only after the earnings are exhausted are withdrawals considered a return of your principal. This is important because it means your early withdrawals from a non-qualified deferred annuity will be fully taxable until all the accumulated earnings are paid out. Once you annuitize, the exclusion ratio calculation kicks in, similar to an immediate annuity.
If you have a qualified deferred annuity (from a 401(k) or IRA rollover, for instance), then every penny you withdraw, whether as a lump sum or annuitized payments, is considered taxable income, mirroring the tax treatment of other traditional retirement plan distributions.
The "Exclusion Ratio" for Non-Qualified Annuities
The exclusion ratio is truly the heart of non-qualified annuity taxation. It’s a simple concept but vital for understanding your taxable income. Essentially, it determines what portion of each annuity payment is considered a tax-free return of your original investment (your premiums paid) and what portion is taxable income (the investment gains).
Here’s a simplified look at how it works: you divide your total investment in the contract by the total expected return. The result is a percentage – your exclusion ratio. For example, if you invested $100,000 and the annuity is expected to pay out $200,000 over its lifetime, your exclusion ratio would be 50%. This means 50% of each payment you receive is tax-free, and the other 50% is taxable income. This ratio remains constant for life annuities, even if you live longer than expected and receive more than your expected return; however, once your investment is fully recovered, all subsequent payments become fully taxable. State income tax typically applies to the taxable portion of these payments.
State-by-State Breakdown of Annuity Taxation
This is where things get really interesting, and frankly, a bit complex. While the federal government has its rules, each state gets to decide how it taxes various forms of income, including annuities. There's no one-size-fits-all answer, which often leads to confusion for retirees. Some states are very retirement-friendly, while others might take a bigger bite out of your annuity income. It's truly a patchwork, and what applies in one state like Florida might be completely different in, say, New York. You really need to dig into the specifics for where you live.
States With No Income Tax: A Simple Picture
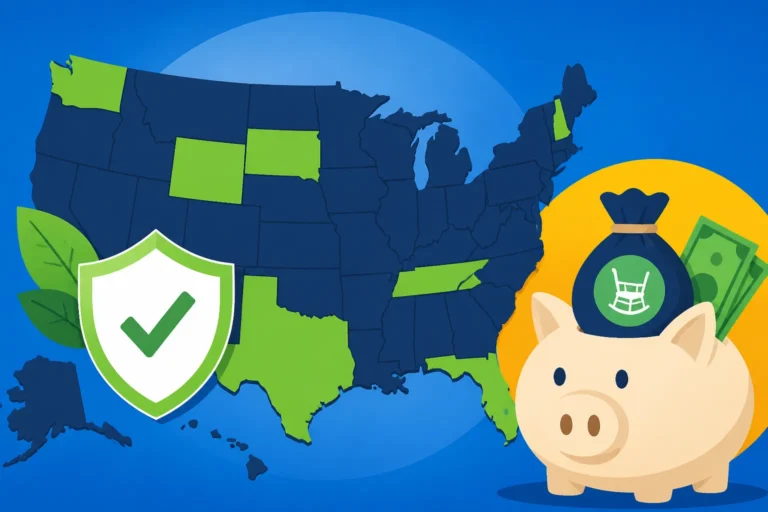
Let's start with the good news for many retirees: there are nine states that currently don't levy a statewide income tax at all. If you live in one of these states – Alaska, Florida, Nevada, New Hampshire (though it taxes interest and dividends, not earned income), South Dakota, Tennessee, Texas, Washington, or Wyoming – your annuity income generally won't be subject to state income tax. This is a huge draw for retirees, as it can significantly boost your net retirement income.
For example, if you're a long-time resident of Florida, enjoying the sunshine and the beaches, your annuity payments, whether immediate or deferred, qualified or non-qualified, won't face a state income tax. The same goes for someone who decides to establish Florida domicile in retirement. It simplifies tax planning immensely, as you only have the federal taxation to worry about. This is a primary reason why many retirees consider moving to one of these states, as it directly impacts their overall tax burden. SmartAsset provides excellent tools and calculators to help you compare tax burdens across different states, which can be particularly useful when considering a move.
States with Partial Exemptions or Special Rules
Many states fall into this category, offering some relief but not a full exemption. These states often have specific rules for how they tax retirement income, and annuities usually fall under these general categories. For instance, a state might exempt a certain amount of retirement income, or it might have age-based exemptions. This means that if your annuity income, combined with other retirement sources like pensions or IRA distributions, falls below a certain threshold, it might not be taxed at the state level.
- Pennsylvania is a great example of a state that is very friendly to retirement income. It generally exempts most retirement income, including annuities, from state income tax for those 60 and older. This means that while Pennsylvania does have an income tax, it largely spares retirees from paying it on their annuity earnings.
- Mississippi also offers a generous retirement income exclusion. If you're 59 1/2 or older, your eligible retirement income, which includes annuity payments, is exempt from state income tax.
- Georgia is another state to consider. For 2026, it offers a generous exclusion for retirement income, including annuities, for those aged 62 or older, or permanently disabled. The exclusion can be quite substantial, reaching up to $65,000 per person. This means if your annuity income (and other retirement income) is below that threshold, it could be entirely state tax-free.
It's crucial to look at the specific rules for your state and check for any age requirements or income limitations. What constitutes "retirement income" can vary slightly from state to state, so always verify that annuities are included in any exemptions. Understanding these nuances is essential for how to minimize state taxes in retirement.
States that Tax Annuities as Ordinary Income
Then there are states that generally tax the taxable portion of your annuity payments as ordinary income, much like your wages. These states typically follow federal guidelines for what constitutes the taxable portion of an annuity (the earnings, not the return of principal for non-qualified annuities, and the full amount for qualified annuities).
- California, for example, is known for its higher tax rates. While it does not specifically target annuities, the taxable portion of your annuity income will be subject to the state's progressive income tax rates, just like other forms of income.
- New York also taxes the taxable portion of annuity income as ordinary income, though it does offer some pension and annuity income exclusions for individuals meeting certain age requirements and income thresholds. However, for many, a significant portion of their annuity payments will be subject to New York’s income tax brackets.
- Oregon and Vermont are other states where you can expect your taxable annuity income to be treated as regular income. They don't offer broad exclusions for retirement income that would cover most annuity payments, meaning you'll pay their standard income tax rates on the taxable portion.
For residents of these states, careful planning and understanding your specific tax bracket are vital. You'll want to ensure your withholding is accurate and explore any potential deductions or credits your state might offer that could indirectly reduce your overall tax burden. This is where personalized advice from a financial advisor can be invaluable. SmartAsset's online tools can also give you a good preliminary estimate of your tax situation in various states.
Here's a simplified table summarizing state approaches to annuity taxation, keeping in mind that "partial exemption" can mean a wide range of specific rules. This is for general informational purposes only and not exhaustive for every specific scenario or tax change.
| State Type | Examples | General Annuity Tax Treatment |
|---|---|---|
| No Income Tax States | Florida, Texas, Nevada, Washington, Wyoming, Alaska, South Dakota, Tennessee, New Hampshire (no earned income tax) | No state income tax on any annuity income (or other income). |
| Tax-Friendly States | Pennsylvania, Mississippi, Illinois, Kentucky | Often exempt all or most annuity income from state tax, usually with age or income qualifications. |
| Moderately Tax-Friendly States | Georgia, Colorado, New Jersey, Alabama, Delaware | May offer significant exclusions or deductions for a portion of retirement income, including annuities, often age-based or income-tiered. |
| States Taxing as Ordinary Income | California, New York, Oregon, Vermont, Minnesota, Wisconsin | Generally taxes the federally taxable portion of annuity income at standard progressive state income tax rates. May have limited exclusions. |
Remember that states constantly review and sometimes adjust their tax laws. For instance, some states have been working on state income tax cuts & changes for 2026, which could impact how retirement income is treated. It's always a good idea to check the most current information for your specific state.
Common State Tax Exemptions and Deductions for Retirement Income
Even in states that do tax annuity income, you might not be out of luck entirely. Many states offer various exemptions, deductions, or credits that can reduce your overall taxable income, including the portion derived from annuities. These provisions are often designed to make retirement more affordable and encourage seniors to remain in or move to the state.
General Retirement Income Exclusions
A common way states provide tax relief to retirees is through general retirement income exclusions. These allow you to subtract a certain amount of eligible retirement income from your gross income before calculating your state tax. Annuities, particularly the taxable portion of non-qualified annuities and the full amount of qualified annuities, often fall under this umbrella.
For example, New Jersey has a substantial retirement income exclusion. If your total income is below a certain threshold, you might be able to exclude a significant amount of your pension and annuity income from state taxation. This can be a huge benefit for those relying on annuities for their living expenses. Similarly, Maryland offers a subtraction modification for a certain amount of pension exclusion, which can often include private annuity payments if they meet specific criteria. Understanding these limits is critical to optimizing your tax strategy. These exclusions are usually adjusted for inflation or changed by state legislatures, so it's always worth checking the latest figures.
Age-Based Deductions
Another common relief mechanism is age-based deductions. Many states recognize that older retirees often have fixed incomes and higher healthcare costs, and they offer deductions for taxpayers above a certain age, commonly 62 or 65. These deductions can sometimes be applied against your total income, reducing the portion that includes your annuity payments.
Colorado, for example, offers a "pension/annuity subtraction" for those 55 and older. This allows eligible taxpayers to subtract a certain amount of their taxable pension and annuity income from their state taxable income. The amount of the subtraction can vary based on your age and the type of income. Even in states with seemingly higher income taxes, these age-based deductions can provide substantial relief, making the effective tax rate on your annuity income much lower than it initially appears. When you're trying to figure out if your state is tax friendly for retirees, these details matter a lot more than just the top tax rate.
How to Navigate Annuity Taxation When Moving States
Moving to a new state is a big decision, and the tax implications are often a primary concern, especially for retirees. When annuity income is a significant part of your financial picture, understanding how your residency impacts state taxation is paramount. It’s not just about picking a state with no income tax; it's about properly establishing your new residency to ensure you're not inadvertently creating a dual-tax situation.
Establishing Domicile vs. Statutory Residency
This is arguably the most crucial concept when moving states, particularly from a high-tax state to a low-tax or no-tax state. Domicile refers to your true home, the place where you intend to live permanently and return to whenever you're away. It's about your intent and actions. Statutory residency, on the other hand, is a more objective test, often based on the number of days you spend in a state. Many states, like New York and California, have very strict statutory residency rules, often involving the infamous 183-day rule for state taxes.
For annuity taxation, your state of domicile is usually the one that will tax your worldwide income, including annuity payments. If you merely spend a lot of time in a state and become a statutory resident there, that state might attempt to tax income sourced within its borders, but your annuity income would typically be taxed by your state of domicile. The challenge arises when a state believes you haven't truly changed your domicile, which can lead to residency audits and battles over where you actually owe taxes. Properly understanding domicile vs statutory residency is critical.
Impact of State Reciprocity on Annuity Income
While reciprocity agreements are more common for earned income when you live in one state and work in another, they generally don't apply to retirement income like annuities. State reciprocity agreements explained are typically designed to prevent double taxation on wages. Annuity income, being passive investment income, is usually taxed by your state of residence (domicile).
So, if you move from, say, Ohio (which taxes annuities as ordinary income) to Florida (no income tax), and properly establish your Florida domicile, you generally won't owe Ohio state income tax on your annuity payments anymore. However, if you maintain a strong connection to Ohio (like owning a home, having family there, or spending significant time), Ohio might still try to claim you as a resident for tax purposes, leading to potential double taxation or audits. The key is a clear, unequivocal break with your old state.
Planning Your Move: What to Consider
If you're considering a move primarily for tax reasons, especially concerning your annuity income, you need a solid plan. It's not enough to just change your mailing address. States, particularly those with high income taxes that see many residents leave (like California or New York), are often aggressive in auditing former residents.
To effectively change your state residency for taxes and protect your annuity income from your old state's taxes, you should:
- Sever ties: Sell your previous home or rent it out. Change your driver's license, car registration, and voter registration to the new state.
- Establish new ties: Open bank accounts in the new state, register with local doctors, join clubs, and make sure your primary social and financial activities are centered in your new home.
- Document everything: Keep meticulous records of your move, utility bills in your new home, and receipts for services performed in your new state.
- Spend time wisely: Be mindful of how many days you spend in your former state, especially if it has a statutory residency rule. This is particularly important for snowbird & dual-residency taxes.
For comprehensive advice on changing residency, it’s often beneficial to consult with a tax professional who specializes in multi-state taxation. SmartAsset also offers valuable insights into the tax implications of moving, which can be a helpful starting point for your research.
Strategies to Minimize State Annuity Taxes
It’s natural to want to keep as much of your hard-earned retirement savings as possible. While you can't magically erase all taxes, there are definitely proactive steps you can take to legally minimize the state tax bite on your annuity income. These strategies often involve understanding your state’s specific rules and planning your withdrawals carefully.
Understanding Your State's Specific Rules
This might sound basic, but it's truly the foundation of any good tax minimization strategy. As we've discussed, every state is different. What works in Pennsylvania won't necessarily apply in Massachusetts. You need to know:
- Does your state tax retirement income at all? If you live in one of the states with no income tax (2026 full list), your job is much easier on the state level.
- Are there age-based exclusions or general retirement income exclusions? Many states offer these, and your annuity income might qualify. For instance, is there a specific dollar amount you can exclude, or does it depend on your total income? You'll find details on these kinds of benefits in resources covering retirement income exclusions by state.
- How does your state differentiate between qualified and non-qualified annuity income? Most states follow the federal distinction, but it's good to confirm.
- Are there any special credits for seniors or those with low to moderate income? These might not directly target annuities but could reduce your overall state tax liability.
Staying informed about these rules, perhaps by checking your state's Department of Revenue website or consulting with a local tax professional, is your best defense against unexpected tax bills.
Timing Your Withdrawals
For deferred non-qualified annuities, the timing of your withdrawals can significantly impact your state tax liability due to the LIFO rule (Last-In, First-Out). Since earnings are taxed first, if you can delay withdrawals until after you've moved to a state with lower or no income tax, or until you qualify for more favorable state tax exclusions (e.g., age 65), you could potentially reduce the overall state tax paid on those earnings.
Consider this scenario: you're 58, living in a high-tax state, and have a non-qualified deferred annuity with significant gains. If you need money, taking a withdrawal now would mean those gains are taxed at your current state's high rate. If you could wait until you turn 65 and move to a state like Pennsylvania, where most retirement income is exempt, those same withdrawals could be state tax-free. This isn't always feasible, as life happens, but it highlights the power of strategic timing.
Utilizing Other Tax-Advantaged Accounts
While annuities are a fantastic tool for retirement income, they are just one piece of the puzzle. A holistic approach to retirement planning means looking at all your income sources and how they are taxed at the state level.
- 401(k)s and IRAs: Many states have different rules for how they tax these traditional retirement accounts compared to annuities. Understanding these differences can help you decide which account to draw from first. For example, some states that fully exempt pension income might treat 401(k) and IRA withdrawals differently, or vice-versa.
- Roth IRAs: Withdrawals from Roth IRAs are generally tax-free at both the federal and state levels, provided you meet the requirements (age 59 1/2 and the account has been open for at least five years). If you have Roth savings, drawing from them can provide completely state tax-free income, reducing the need to tap into taxable annuity income.
- 529 Plans: While primarily for education, if you have a 529 plan, understanding the 529 plan tax deductions by state can impact your overall tax picture. While not directly related to annuity income, any tax savings you can achieve elsewhere frees up more of your other income.
By understanding how all your retirement assets are treated, you can develop a strategy that draws down your accounts in the most state-tax-efficient order. It's about looking at the big picture and leveraging every tool in your financial toolbox. This is where personalized financial guidance, perhaps using resources like SmartAsset's financial advisor matching tool, can be incredibly beneficial. They can help you connect with fiduciaries who can tailor advice to your specific state and financial situation.
Disclaimer
Please remember that tax laws are complex and subject to change. The information provided in this guide is for informational purposes only and does not constitute tax, legal, or financial advice. Always consult with a qualified tax professional or financial advisor for advice tailored to your specific situation. State tax laws can change frequently, so it's crucial to verify the most up-to-date information.