Does California Tax Social Security?
It's a question that keeps many future retirees up at night, especially those who've worked hard and are looking forward to enjoying their golden years in the Golden State: "Will California take a slice of my Social Security benefits?" The anxiety is real, with federal taxes already looming and state tax laws feeling like a labyrinth. This guide is here to untangle that knot of worry and provide a comprehensive, realistic look at how California treats your Social Security income and other retirement finances, so you can plan with confidence.
Understanding California's Approach to Social Security Benefits
The good news, and let's just get this out there upfront because it's a huge relief for many, is that California has a distinct policy regarding Social Security income. This stands in stark contrast to its reputation for generally higher taxes, and it's a critical detail for anyone planning their retirement finances here.
The Golden State's Tax Philosophy
California does not tax Social Security benefits. Let that sink in for a moment. Whether you're receiving retirement, disability, or survivor benefits, the state of California will not levy income tax on that money. This is a significant advantage for retirees in California, often overlooked amidst discussions of the state's overall tax burden. For many, Social Security forms a foundational part of their retirement income, and knowing it's fully exempt from state income tax can provide a great deal of peace of mind.
Imagine Maria, who spent her career in the Bay Area, working diligently and contributing to her Social Security. Now, as she approaches retirement in San Francisco, the relief she feels knowing that the state won't take a slice of that hard-earned benefit is immense. Her monthly check will be fully available to cover her living expenses, rather than being diminished by state-level taxation. This policy ensures that a fundamental safety net for seniors remains intact and untaxed by the state government.
It's a point of clarity that often surprises people, especially when they hear generalized statements about California being a high-tax state. While California does indeed have a progressive income tax system, with some of the highest marginal rates in the country for high earners, its stance on Social Security is unequivocally pro-retiree in this specific area. This exemption can make a tangible difference in the monthly budget of countless seniors across the state, from the sprawling suburbs of Los Angeles to the quieter communities of the Central Valley.
Comparing California to Other States
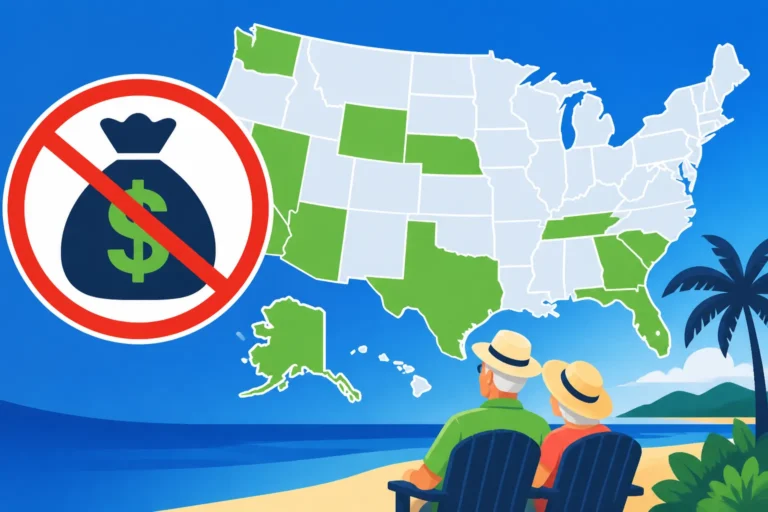
California's policy on Social Security benefits truly shines when you compare it to what's happening in other parts of the country. While the federal government does tax a portion of Social Security benefits for many recipients, state-level taxation varies wildly. As of recent data, there are still about ten states that tax Social Security benefits to some degree, including Colorado, Connecticut, Kansas, Minnesota, Montana, New Mexico, Rhode Island, Utah, Vermont, and West Virginia (though West Virginia is phasing out its tax). Some of these states have income thresholds that trigger the tax, while others have more comprehensive taxation policies.
Think about a couple, the Johnsons, who were considering moving from their long-time home in San Diego to, say, Minnesota for retirement. They might have been enticed by lower housing costs in certain areas of Minnesota, but they would soon discover that unlike in California, a portion of their Social Security benefits would be subject to state income tax there. This direct taxation would be a significant new hit to their retirement income that they simply wouldn't face back home in California. Such differences highlight why a clear understanding of each state's tax laws is crucial for retirement planning.
This exemption in California places it in a favorable light for retirees when it comes to this specific income stream. Many financial planning platforms, like SmartAsset, offer tools that allow you to compare the overall tax burden on retirees across different states, and this Social Security exemption is almost always a positive factor for California. While the Highest Income Tax States in 2026 might still include California for other income types, it certainly isn't in that category for Social Security. This distinction is vital for those weighing their options or simply wanting to understand their current tax landscape. It's a testament to the state's commitment to protecting a core element of senior financial well-being. If you're looking for States That Don't Tax Social Security (2026), California is firmly on that list.
What Income is Taxed in California for Retirees?
While the news about Social Security is undoubtedly excellent, it's important to have a clear-eyed view of your entire retirement income picture. California's tax policies, like those of most states, are complex, and while one income stream may be exempt, others are certainly not. Understanding which sources are taxable is key to effective financial planning in your retirement years.
Common Retirement Income Sources
Unfortunately, the state's generosity with Social Security doesn't extend to all forms of retirement income. Most other common sources of retirement income are generally subject to California's progressive state income tax. This includes distributions from private pensions, withdrawals from traditional 401(k)s, and distributions from traditional IRAs. These income streams are typically taxed as ordinary income, meaning they are included in your adjusted gross income and then taxed according to the state's income tax brackets.
Consider David, a retired tech executive from San Jose, who receives a substantial monthly pension from his former company and also takes regular distributions from his large IRA. While his Social Security benefits are completely untouched by the state, every dollar he receives from his pension and IRA withdrawals will be factored into his taxable income. Depending on the total amount of these distributions, he could find himself in one of California's higher marginal tax brackets, meaning a significant portion of that income will go towards state taxes. It's a stark reminder that while one benefit is exempt, others contribute to your overall tax liability.
This also applies to other forms of investment income, such as interest, dividends, and capital gains from the sale of investments not held within tax-advantaged retirement accounts. These are all typically subject to California's income tax rules. The state's tax system is designed to tax most forms of income, and retirement accounts, once they are distributed, generally fall into this category. Roth IRA qualified distributions, however, are typically tax-free at both the state and federal levels, offering a powerful planning tool for those who contributed to them. Understanding the difference between these various income types is crucial for accurately projecting your tax obligations. You can review the specifics of California Income Tax Brackets 2026 to see where your projected income might fall.
Exemptions and Deductions for Seniors
Even with other retirement income being taxable, California does offer some avenues that can help reduce a retiree's overall tax burden. Like the federal system, California allows taxpayers to choose between a standard deduction or itemizing deductions. The state sets its own standard deduction amounts, which can be particularly beneficial if your itemized deductions (like mortgage interest or charitable contributions) don't exceed the standard amount. For seniors, there's often an additional silver lining.
California provides a nonrefundable Senior Exemption Credit for taxpayers who are 65 or older by the end of the tax year. This credit is a flat dollar amount per eligible senior, and while it's not a deduction that reduces your taxable income, it directly reduces the amount of tax you owe. If both spouses in a married couple filing jointly are 65 or older, they can each claim this credit, doubling its impact. These small adjustments, when combined with other potential deductions, can lead to a noticeable difference in your overall tax liability.
For example, Sarah, living in Orange County, relies on her state standard deduction to lower her taxable income from her pension. On top of that, since she is over 65, she also claims the Senior Exemption Credit. While her pension income is still taxable, these provisions help to chip away at the total amount she owes the state. Financial planning tools and resources, like those offered by SmartAsset, can be immensely helpful in modeling these deductions and credits to get a clearer picture of your potential tax savings. Understanding California Standard Deduction 2026 and other available credits is an important step in managing your tax liability effectively.
Here’s a quick overview of how different retirement income sources are generally treated for California state income tax purposes in 2026:
| Income Source | California State Tax Treatment (2026) | Federal Tax Treatment (Up to 85% taxable) | Notes |
|---|---|---|---|
| Social Security Benefits | NOT TAXED | Potentially Taxed | A significant advantage for CA retirees compared to some other states. |
| Private Pensions | Taxed as Ordinary Income | Taxed as Ordinary Income | Subject to CA's progressive income tax rates. This includes most employer-sponsored defined benefit plans. |
| 401(k) / IRA Withdrawals | Taxed as Ordinary Income | Taxed as Ordinary Income | Qualified Roth IRA distributions are generally tax-free at both state and federal levels. |
| Investment Income | Taxed as Ordinary Income/Capital Gains | Taxed as Ordinary Income/Capital Gains | Includes interest, dividends, capital gains from non-retirement accounts. |
| Military Retirement Pay | Not taxed | Taxed as Ordinary Income | California fully exempts military retirement pay from state income tax, a notable benefit for veterans. |
Navigating Your Tax Situation as a California Retiree
Retirement in California involves more than just understanding how Social Security is taxed; it's about a holistic approach to your financial well-being. The state's unique characteristics, from its stringent residency rules to its diverse cost-of-living areas, mean that proactive and informed planning is absolutely essential.
The Importance of Residency
One of the most critical aspects of state taxation, especially in a state like California, is residency. You are generally liable for state income taxes to the state where you are considered a legal resident. California, often dubbed one of the "hardest states to leave" for tax purposes, has notoriously strict rules about determining residency and domicile, and its tax agency, the Franchise Tax Board (FTB), is quite aggressive in enforcing them. Simply declaring yourself a resident of another state isn't enough; your actions must consistently support your claim of having moved your "domicile"—your true home—elsewhere.
Take the hypothetical case of Robert, a wealthy individual who decided to "move" to Nevada to avoid California income taxes after selling his successful business. However, he still spends more than half the year at his sprawling second home in Palm Springs, maintains his California driver's license, keeps his primary doctor in Los Angeles, and continues to be deeply involved with local California charities. Despite his declared Nevada residency, the California FTB is very likely to consider him a statutory resident. This means they would assert their right to tax his worldwide income, regardless of his stated domicile in a no-income-tax state. Such cases are not uncommon and highlight the stringent nature of California's State Tax Residency Rules Explained.
The FTB uses a "facts and circumstances" test, looking at a multitude of factors to determine if you truly severed your ties with California. This can include where you register your vehicles, where you vote, the location of your bank accounts, professional licenses, and even where your family members reside. Understanding the nuances of California's residency requirements is paramount for anyone considering a move out of state, or for those who split their time between California and another state. Falling afoul of these rules can lead to a California Residency Audit & FTB, which can be a complex and stressful experience.
Planning for Your California Retirement
Given California's unique tax landscape – high cost of living, progressive income taxes on most retirement income (but not Social Security), and strict residency rules – proactive tax planning isn't just a good idea; it's a necessity. It’s not enough to simply know that Social Security is exempt; you need to understand how all your income streams, deductions, and credits interact to affect your overall tax bill. This requires a comprehensive strategy tailored to your personal financial situation and retirement goals.
Consider Linda, who recently retired after decades as a small business owner in Sacramento. Knowing her substantial business sale proceeds and investment portfolio would generate taxable income, she worked closely with a financial planner and tax professional well before her retirement. They strategized her 401(k) withdrawals, aiming to spread them out over several years to avoid pushing her into the highest marginal tax brackets unnecessarily. This thoughtful approach helped her manage her overall tax burden more effectively, even with substantial taxable retirement income from other sources. She also considered using services like SmartAsset to find local financial advisors specializing in retirement planning.
This kind of forward-thinking approach can help you make informed decisions about when to take distributions from various accounts, how to leverage available deductions and credits, and even whether a Roth conversion might make sense in certain circumstances. It's about optimizing your financial picture to minimize tax leakage throughout your retirement. Exploring strategies on How to Lower Your State Income Tax can provide additional insights. Without careful planning, even with the Social Security exemption, retirees might find their overall financial comfort challenged by other elements of California’s tax and economic environment.
Beyond Social Security: Other California Retirement Taxes
While the focus here is often on income tax, particularly how Social Security is treated, it's crucial for retirees in California to consider the full spectrum of taxes they might encounter. State income tax is just one piece of a much larger financial puzzle, and other taxes can significantly impact a retiree's budget, especially in a state with a high cost of living like California.
Property Taxes and Senior Exemptions
California's property tax system is famously unique, thanks to Proposition 13, enacted in 1978. This proposition limits a property's assessed value to its 1975 level or its most recent purchase price, plus an annual increase capped at 2% or the rate of inflation, whichever is lower. This means that long-term homeowners, especially those who bought their homes decades ago, often pay significantly less in property taxes than if their homes were assessed at current market values. For many seniors who have lived in their homes for a long time, this can be an enormous financial advantage, acting as a de facto exemption on their property values.
Imagine the Chen family, who purchased their home in San Francisco back in 1980 for a fraction of its current multi-million-dollar market value. Their property taxes are still based on that original purchase price, with only minimal annual increases, ensuring their property tax bill remains relatively low. If their taxes were reassessed at current market rates, they would be astronomical. This protection allows them to remain in their cherished home, contributing to their quality of life in retirement without being taxed out of their residence. Without Proposition 13, many seniors would be unable to afford the property taxes in their long-held homes.
While Prop 13 offers broad protection, there are also some specific programs designed to provide further relief for certain seniors. These can include property tax deferral programs for low-income seniors, allowing them to postpone paying property taxes until they sell their home or pass away. Additionally, there are often homestead exemptions or specific relief programs available for veterans. While these are not as universally impactful as Prop 13, they can offer targeted relief. Understanding these nuances, as discussed in guides about Property Tax Credits & Homestead Exemptions by State, is vital for homeowners in their retirement years.
Sales Taxes and Cost of Living
Beyond property taxes, retirees in California also need to contend with sales taxes and the overall high cost of living. California has one of the highest statewide sales tax rates in the nation. When local sales taxes are added on top, many cities and counties see combined sales tax rates that can reach over 10%. This means that almost every purchase, from groceries and clothing to home repairs and entertainment, comes with an additional tax burden. While a retiree might not have income tax on their Social Security, they will certainly feel the pinch of sales taxes on their daily expenditures.
It's a valid frustration many retirees express: while it's fantastic that Social Security isn't taxed, the everyday reality of living in California can still be expensive. Many retirees find their overall budget significantly strained by the cumulative effect of high sales tax on nearly every transaction and the sheer expense of housing, utilities, and transportation, even if they've paid off their mortgage. The state's beautiful weather and amenities come with a price tag that extends well beyond income tax. This means that while some states with no income tax might appear appealing, a holistic view of all taxes and living expenses is crucial. You can find more comprehensive comparisons in articles like Cost of Living vs Taxes by State.
The high cost of living, particularly for housing, is a dominant factor for many, especially if they are new to the state or haven't benefited from Prop 13's protections for long-term homeowners. Even without state income tax on Social Security, the combined effect of sales taxes, excise taxes, and the general expense of goods and services means that California may not necessarily be the cheapest place to retire. It's a trade-off many are willing to make for the lifestyle, climate, and amenities, but it's essential to enter retirement with a clear understanding of these financial realities. For a deeper dive into the overall tax picture, exploring Is California Tax Friendly? Full Breakdown is highly recommended.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.