Retirement Income Exclusions by State
As you approach or enter retirement, one of the biggest financial puzzles you might face is understanding how different states treat your hard-earned retirement income. It's a frustrating reality that what might be tax-free in one state could be significantly taxed in another, leaving many feeling overwhelmed and worried about their financial security. This comprehensive guide is designed to demystify state retirement income exclusions, helping you navigate the complex landscape of state taxation so you can make informed decisions about where to live and how to manage your retirement savings.
Understanding State Retirement Income Taxation
The world of state income tax for retirees is anything but uniform. Unlike federal taxes, where rules generally apply across the board, each state has its own unique approach to taxing retirement income. This can create a real headache for folks trying to plan their golden years, especially if they're considering a move or even just splitting their time between different states. It’s not just about income tax rates; it’s about what types of income are subject to those rates, and how much of it gets excluded.
The Patchwork Quilt of State Tax Laws
Imagine a literal patchwork quilt, where each square represents a different state, and each square has its own distinct pattern of rules. That’s essentially what you’re dealing with when it comes to state retirement income taxes. Some states are incredibly generous, exempting most or even all forms of retirement income, while others tax everything from your Social Security benefits to your 401(k) withdrawals. There's no single, easy answer for "how are retirement benefits taxed across the U.S.?" because the answer literally changes when you cross state lines. This is why a thorough understanding of a state's specific exclusions is far more important than just glancing at its overall income tax rate. A state with a moderate income tax rate might actually be more tax-friendly for retirees if it offers substantial exclusions for retirement income compared to a state with a lower nominal rate but no such exclusions.
Differentiating Income Types for Retirees
To really get a handle on state tax exclusions, you first need to understand that not all retirement income is treated equally. States often categorize income into different buckets, and each bucket might have its own set of rules. For example, your Social Security benefits, pension payouts, distributions from 401(k)s and IRAs, and military retirement pay are all distinct types of income, and a state might choose to tax one, partially tax another, and completely exempt a third.
Let's say you're receiving Social Security, a private pension, and taking distributions from a traditional IRA. In State A, they might tax your pension and IRA distributions but fully exempt Social Security. In State B, they might tax all three, but offer an exclusion amount based on your age or income level. It's these specific nuances that can dramatically impact your actual take-home income in retirement. This is also where things can get confusing, as what constitutes a "pension" or "retirement income" can sometimes have slightly different definitions depending on the state's tax code. Getting clear on these distinctions is the first step to figuring out where you stand.
States with Broad Retirement Income Exclusions
When you're dreaming about retirement, often those dreams involve less stress, more leisure, and certainly less tax burden. The good news is that several states have decided to make that dream a reality for their retirees by offering broad exclusions on retirement income. These states are often at the top of lists for retirees looking to stretch their savings further.
States That Don't Tax Income At All (The "No Income Tax" Crew)
Let's start with the champions of tax-friendly retirement: the states that simply don't have a broad state income tax to begin with. If there's no income tax, there's no tax on any income, including retirement income! This is often the simplest and most straightforward way to ensure your pensions, 401(k) withdrawals, and Social Security benefits remain untouched by state income tax.
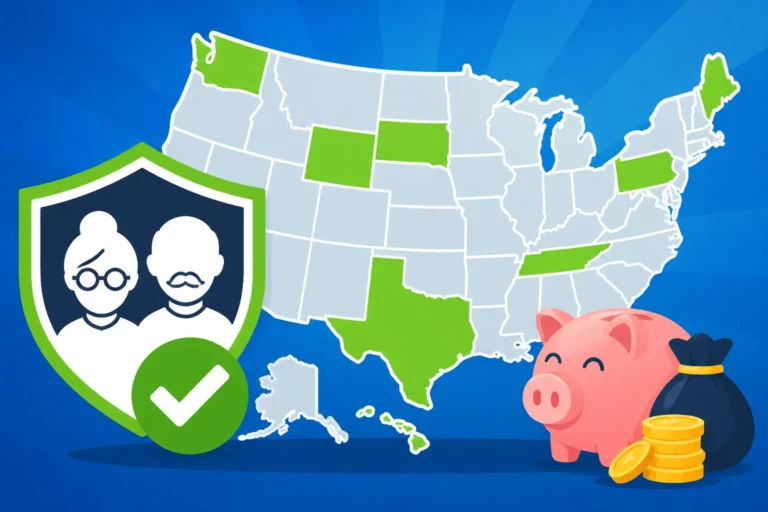
Currently, there are nine such states. These include Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. New Hampshire technically doesn't tax earned income but does tax interest and dividends, though this tax is being phased out. So, if you're primarily living off retirement distributions, these states offer a significant advantage. For instance, if you're a long-time New Yorker and are considering Moving From California to Avoid State Tax, places like Florida or Texas become very attractive. Imagine living in Naples, Florida, enjoying the sunshine, and knowing that your pension income from a career in California isn't being dinged by state income tax. This can translate into thousands of dollars in savings annually, allowing you to enjoy a higher quality of life or leave more to your heirs.
States Offering Full Exemptions for Qualified Retirement Income
Beyond the no-income-tax states, there's another group that is incredibly friendly to retirees: those states that do have an income tax but choose to fully exempt most or all forms of qualified retirement income. These states understand the value retirees bring and aim to make their golden years as financially comfortable as possible.
One prime example is Illinois. While Illinois has a flat income tax, it explicitly exempts all retirement income, including Social Security benefits, public and private pensions, and distributions from IRAs and 401(k)s. This means if you spent your career in Illinois, you won't pay state income tax on those distributions in retirement. Pennsylvania is another gem, known for its generous treatment of most pension and retirement distributions. Similar to Illinois, if you receive income from a qualified retirement plan, chances are it's fully exempt from state income tax in Pennsylvania. Other states like Mississippi are also very pension-friendly, excluding all forms of qualified retirement income. It's crucial to look beyond just the income tax rate, as you can see, because a state like Pennsylvania, with a flat income tax rate, can still be very advantageous for retirees due to its exclusions. For a deeper dive into this, check out our guide on States That Don't Tax Pensions (2026).
Common Exclusion Types Across States
Even in states that do tax retirement income, it's rare that everything is taxed. Most states offer some form of exclusion, which means a portion or all of a specific type of retirement income is exempt from state income tax. Understanding these common exclusions is key to navigating your state tax liability.
Social Security Benefit Exclusions
Social Security benefits are often the cornerstone of retirement income for many Americans, and thankfully, most states recognize this importance by choosing not to tax them. The vast majority of states that have an income tax fully exempt Social Security benefits. This is a huge relief for retirees, as it ensures this vital income stream isn't eroded by state taxes.
However, there are a few exceptions. As of 2026, there are still a handful of states that continue to tax Social Security benefits to some degree, often mirroring the federal taxation rules or applying their own thresholds. These states include Colorado, Connecticut, Kansas, Minnesota, Montana, New Mexico, Rhode Island, Utah, Vermont, and West Virginia. Some of these states, like Colorado, offer significant income-based subtractions or credits that effectively exempt most lower and middle-income retirees from the tax, but it's not a blanket exemption. For example, if you reside in Minnesota, your Social Security benefits might be partially taxable depending on your overall income, much like at the federal level. It's absolutely critical to confirm the specific rules for your state, especially if you live in one of these few states. For a complete breakdown, our article on States That Don't Tax Social Security (2026) offers invaluable detail.
Pension and Annuity Exclusions
Pensions and annuities are another major source of retirement income, and how states treat them varies widely. Some states offer broad exemptions, while others tax them just like regular income. This area can be particularly complex due to the different types of pensions (public vs. private) and annuities.
Many states provide exclusions for at least a portion of pension and annuity income. For instance, New Jersey offers a generous exclusion for eligible retirement income, which includes pensions, annuities, and IRA withdrawals, for those meeting specific age and income requirements. Likewise, states like Georgia allow a significant exclusion for all types of retirement income, including pensions, once you reach a certain age, such as 65. The exact exclusion amount and any age or income limitations are unique to each state. Some states might differentiate between military pensions, public employee pensions (like teachers or state workers), and private company pensions, offering full exemption for some but only partial for others. Always dig into the specific language of your state's tax code or consult a local tax professional to understand the nuances of your pension.
401(k) and IRA Withdrawal Exclusions
For many modern retirees, 401(k)s and IRAs are their primary retirement savings vehicles. The tax treatment of withdrawals from these accounts is a major concern. Similar to pensions, how states tax these distributions is far from consistent.
In the states that don't have an income tax (like Texas or Florida), or those that broadly exempt all retirement income (like Illinois), your 401(k) and IRA withdrawals will generally be state tax-free. However, in states with an income tax that don't offer such broad exemptions, these withdrawals are typically treated as taxable income, just like wages. This means they are subject to the state's regular income tax rates. Some states, like Pennsylvania, extend their general retirement income exemptions to cover 401(k) and IRA distributions from qualified plans, making them largely tax-free. On the other hand, a state like California taxes all traditional IRA and 401(k) withdrawals at its regular, progressive income tax rates. It’s important to note the distinction between traditional and Roth accounts; Roth IRA withdrawals, when qualified, are generally tax-free at both the federal and state levels because contributions were made with after-tax dollars. Our guide on States That Don't Tax 401(k) & IRA Withdrawals delves into this in more detail.
Military Retirement Pay Exclusions
For retired servicemembers, military retirement pay can be a significant portion of their income. Recognizing the service and sacrifice of veterans, many states offer full or partial exemptions for military retirement pay. This is a benefit designed to attract and retain military retirees within their borders.
The landscape here is quite favorable for military retirees. The vast majority of states fully exempt military retirement pay from state income tax. This includes states like Arizona, North Carolina, and Virginia, which have a significant military presence. This can be a huge financial boon for veterans, as it means their entire military pension is shielded from state income tax. However, there are still a handful of states that tax military retirement pay, though some may offer partial exclusions or subtractions based on age or income. For example, in New Mexico, military retirement pay is fully exempt up to a certain amount, and then a portion above that might be taxed. It's an evolving area, with more states moving towards full exemption, so it's always good to check the most current laws. For an in-depth list, see our resource on Military Retirement Tax by State (Full List).
Age and Income-Based Exclusions
Beyond the type of income, two other major factors often play a role in state retirement income exclusions: your age and your overall income level. Many states design their tax breaks to specifically benefit older taxpayers or those with more modest incomes, aiming to provide relief where it's most needed.
The Role of Age in State Tax Exemptions
It's common for states to offer enhanced tax benefits once you reach a certain age, typically 65 or sometimes 62. These age-based exclusions are often designed to recognize that older retirees may have fixed incomes and higher healthcare costs, making them more vulnerable to tax burdens.
For example, Georgia allows taxpayers aged 65 or older to exclude a substantial amount of their retirement income from state tax. This broad exclusion covers income from pensions, annuities, interest, dividends, and capital gains, up to a certain dollar limit. Similarly, in Maryland, once you reach age 65 or are totally disabled, you may be able to subtract a significant amount of your pension and retirement annuity income. This means that two individuals with the exact same pension could pay different amounts in state tax purely because one is 65 and the other is 60. These age-based breaks are a significant consideration when planning your retirement location and strategy. It's not just about when you can retire, but when you will qualify for these valuable state tax exemptions.
Income Thresholds and Phase-Outs
While some states offer broad exclusions regardless of income, many tie their retirement income exemptions to specific income thresholds. This is especially true for Social Security benefits (in the few states that tax them) and for general retirement income subtractions. The idea is to provide relief to lower and middle-income retirees while still taxing higher earners.
Consider states like Colorado or Connecticut, which tax Social Security. They often have income limitations for their subtractions or credits, meaning if your adjusted gross income (AGI) exceeds a certain amount, your Social Security benefits may become partially or fully taxable at the state level. The same can apply to broader retirement income exclusions. New Jersey, for instance, offers an exclusion for various types of retirement income, but it's only available if your total income is below a certain threshold. Once your income goes above that amount, the exclusion either disappears or phases out gradually. This means you need to be mindful of your total income from all sources – including part-time work, investments, and other benefits – as it can impact the state taxability of your otherwise exempt retirement income. SmartAsset provides excellent tools for retirees to model these scenarios, helping them understand how different income levels might affect their state tax bill. Understanding these thresholds is critical, as miscalculating could lead to an unexpected tax bill.
| State Type | Social Security Benefits | Qualified Pensions/IRAs/401(k)s | Military Retirement Pay | Common Age/Income Limitations |
|---|---|---|---|---|
| No Income Tax States | Fully Exempt (No State Tax) | Fully Exempt (No State Tax) | Fully Exempt (No State Tax) | N/A |
| Full Exclusion States | Fully Exempt | Fully Exempt (from qualified plans) | Fully Exempt | Often none, or broad age criteria |
| Partial Exclusion States | Partially Taxed (income limits) | Partially Taxed (age/income limits) | Often Fully Exempt | Significant age and/or income tiers |
| Tax All States | Taxed (with potential credit/subtraction) | Taxed (like regular income) | Taxed (with potential subtraction) | Limited or no specific exclusions |
Specific State Examples and Their Nuances
To really bring these concepts to life, let's dive into some specific states and look at the actual retirement income exclusions they offer. Each state has its own personality when it comes to taxes, and understanding these individual quirks is crucial.
New York's Retirement Income Exclusions
New York, often seen as a high-tax state, actually offers some significant relief for retirees, especially when it comes to specific types of retirement income. While it does have a progressive income tax system, it provides a fairly generous exclusion for most private and public pensions, annuities, and IRA distributions.
For taxpayers aged 59 1/2 or older, New York allows you to exclude up to $20,000 of pension and annuity income from your taxable income. This applies to both public and private pensions, as well as withdrawals from IRAs and other qualified retirement plans. However, this exclusion does not apply to income from non-qualified plans or general investment income. So, if you have a traditional pension from a company, or you're taking distributions from your 401(k) or IRA, that first $20,000 each year is generally free from New York state income tax. Social Security benefits, on the other hand, are fully exempt from New York state income tax, regardless of your income level. This means if you're living in New York and primarily relying on Social Security and a modest pension, you might find your state income tax burden to be lower than you expected. You can explore more about New York Retirement Income Exclusion for specific details.
Pennsylvania's Generous Pension Exclusions
Pennsylvania stands out as one of the most retirement-friendly states when it comes to pension and retirement income. Despite having a flat state income tax, its approach to retirement income exclusions is exceptionally generous, especially for qualified plans.
In Pennsylvania, income from qualified retirement plans, which includes most pensions, 401(k)s, and IRAs, is generally fully exempt from state income tax, regardless of your age or income level. This is a significant advantage for retirees in the Keystone State. This means if you retired from a company with a pension plan, or you're drawing income from your traditional IRA or 401(k), Pennsylvania typically won't tax it. There are specific rules around what constitutes a "qualified" plan, and generally, distributions from non-qualified deferred compensation plans or early withdrawals before retirement age may still be taxable. However, for the vast majority of retirees relying on standard retirement savings, Pennsylvania offers a significant tax break. Social Security benefits are also completely exempt from Pennsylvania state income tax. This makes Pennsylvania a very attractive option for retirees, especially those with substantial pension or retirement account assets.
Illinois and its Full Exemption for Retirement Income
Illinois, another state often thought of as having a high tax burden, offers a pleasant surprise for retirees: a full exemption for virtually all retirement income. This policy is a huge draw for those planning to retire in the state.
Despite having a flat state income tax rate, Illinois explicitly excludes all distributions from qualified employee benefit plans, IRAs, and Social Security benefits from state income tax. This means that income from your private or public pension, your 401(k) or 403(b) accounts, traditional IRA withdrawals, and your Social Security checks are completely exempt from Illinois state income tax. This is a comprehensive exclusion that provides substantial tax relief to retirees. So, if you've spent your career in Chicago, enjoying the city life, you can likely retire there without state income tax eating into your retirement savings from these sources. This broad exemption makes Illinois remarkably tax-friendly for retirees, often surprising people who only look at the state's general income tax rate.
Navigating Georgia's Retirement Income Exclusion
Georgia is another state that offers significant tax breaks for retirees, especially once they reach a certain age. The state has a progressive income tax structure, but it provides a substantial exclusion for various types of retirement income.
For taxpayers aged 65 or older, Georgia allows an exclusion of up to $65,000 per person of retirement income. This exclusion is quite broad, covering income from pensions and annuities, interest, dividends, net rentals, capital gains, and IRA/401(k) withdrawals. For married couples filing jointly, this effectively doubles to $130,000 if both qualify. For those under 65, there's a smaller exclusion amount for specific retirement income types, or if you are permanently and totally disabled. Additionally, Social Security benefits are fully exempt from Georgia state income tax. This means if you're a senior living in Georgia, a significant portion of your retirement income could be state tax-free. For example, if you're receiving $70,000 in pension income and you're 65 or older, only $5,000 of that would be subject to state income tax. This makes Georgia a very attractive state for retirees, especially those with diverse income streams that fall within these exclusion limits. For more information, you can read our article on Georgia $65,000 Retirement Exclusion (2026).
Strategies for Maximizing Your State Tax Savings in Retirement
Understanding state exclusions is one thing; actively using that knowledge to your advantage is another. With careful planning, you can significantly reduce your state tax burden in retirement, leaving more money for your lifestyle, hobbies, or loved ones.
Understanding Your Domicile and Residency
One of the most powerful strategies for state tax savings, especially if you're considering a move, involves establishing your domicile and residency in a tax-favorable state. Your domicile is your true, fixed, and permanent home, and it's the state where you intend to return whenever you're away. Your residency is where you actually live for a period. These two concepts are critical because your domicile usually determines where you owe state income tax on all your income.
If you're looking to move to a state with broad retirement income exclusions, or one of the States With No Income Tax (2026 Full List), you need to take concrete steps to establish domicile there. This isn't just about moving your furniture. It involves things like obtaining a new driver's license, registering your car, updating your voter registration, opening bank accounts, and severing ties with your old state. For instance, if you're moving from California to Florida to benefit from Florida's no-income-tax status, you'd want to establish How to Establish Florida Domicile. The more evidence you have of your intent to make the new state your permanent home, the stronger your case will be if your former state tries to claim you as a resident for tax purposes. Some states, particularly those with high income taxes like California and New York, are very aggressive in auditing former residents to ensure they've truly changed their domicile. Therefore, a clear, well-documented plan is essential. For more detailed guidance, consider our article on How to Change Your State Residency for Taxes.
Planning for RMDs and State Taxes
Required Minimum Distributions (RMDs) from traditional IRAs and 401(k)s can often be a surprise source of state tax liability for retirees. Once you reach a certain age (currently 73), you generally have to start taking withdrawals from these accounts, whether you need the money or not. These distributions are federally taxable, and in many states, they are also subject to state income tax.
Strategic planning around RMDs is crucial. If you live in a state that taxes IRA withdrawals, you might consider strategies like qualified charitable distributions (QCDs) from your IRA directly to a charity, which can satisfy your RMD requirement and potentially reduce your taxable income. Another strategy might be to convert some funds to a Roth IRA before RMDs begin, especially if you anticipate being in a higher tax bracket in retirement or if your state taxes traditional IRA withdrawals but not Roth withdrawals. While Roth conversions are federally taxable, paying the tax now might prevent state tax on future withdrawals if your state doesn't tax Roth distributions. Working with a financial advisor can help you forecast your RMDs and understand their state tax implications, allowing you to proactively manage your withdrawals and potentially reduce your tax bill. Understanding How RMDs Are Taxed by States is vital for long-term tax planning.
Seeking Professional Tax Advice
The state tax landscape for retirees is incredibly complex and constantly changing. While this guide provides a comprehensive overview, it's impossible to cover every single nuance for all 50 states. This is where professional tax advice becomes invaluable.
A qualified tax advisor specializing in multi-state taxation or retirement planning can help you navigate the specific rules of your state, or states if you have dual residency or significant ties to multiple locations. They can help you understand the full impact of various retirement income types on your state tax bill, advise on domicile changes, and help you identify all eligible exclusions and deductions. Tax software can handle basic returns, but for complex retirement scenarios, especially if you're dealing with different types of retirement income, multiple states, or significant assets, a human expert can offer tailored, nuanced advice that generic software might miss. Many financial planning firms, like some recommended by SmartAsset, offer services specifically designed for retirees. Investing in good advice upfront can save you significant money and stress in the long run.
What to Watch Out For: Common Pitfalls and Changes
Even with the best planning, the state tax environment is dynamic. Retirees need to stay vigilant to avoid common pitfalls and adapt to legislative changes that could impact their carefully crafted tax strategies.
The Impact of Legislative Changes
State tax laws are not set in stone. Legislatures regularly consider and implement changes to their tax codes, and these changes can directly affect retirement income exclusions. A state that is tax-friendly today might become less so tomorrow, and vice-versa.
For example, states might modify existing exclusion amounts, introduce new income thresholds, or even repeal exemptions altogether. We've seen several states, like Missouri, Kansas, and Nebraska, recently repeal their tax on Social Security benefits, making them more attractive for retirees. Conversely, a state facing budget shortfalls might look to expand its tax base, potentially targeting retirement income. It's essential to stay informed about proposed and enacted tax legislation in your state, especially if you rely heavily on specific exclusions. Reputable financial news sources, state revenue department websites, and tax professionals usually track these changes closely. Being aware of these potential shifts allows you to adjust your financial planning proactively rather than being caught off guard when tax season rolls around. Our article State Income Tax Cuts & Changes for 2026 can help you stay current on upcoming modifications.
Overlooking Local and Other Taxes
Focusing solely on state income tax exclusions can sometimes lead retirees to overlook other significant tax burdens that can impact their overall financial picture. Even if a state has no income tax, or generous exclusions, it might make up for that lost revenue through other taxes.
Property taxes are a prime example. States like New Hampshire, which doesn't have a broad income tax (beyond interest and dividends), tend to have higher property taxes to fund local services. Florida, another no-income-tax state, also has property taxes and a sales tax. Sales taxes, excise taxes, and local property taxes or even city income taxes (like the Philadelphia Wage Tax 2026 or NYC Income Tax Explained (2026 Rates)) can all add up, sometimes negating the benefits of state income tax exclusions. It's crucial to evaluate the total tax burden of a state or locality, not just the income tax component, when making retirement location decisions. A state with a low income tax but high property taxes might not be as "tax-friendly" for your specific situation, especially if you own an expensive home. Therefore, always consider the full picture of taxes you'll be paying.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change, and your individual circumstances may vary. We strongly recommend consulting with a qualified tax professional or financial advisor for personalized advice regarding your specific retirement income and state tax situation.