States With No Tax on IRA Distributions
Retiring can feel like a well-deserved victory lap after years of hard work, but the joy of leaving the daily grind can quickly turn to dread when you start thinking about taxes on your hard-earned retirement savings. Many retirees worry about how their Individual Retirement Account (IRA) distributions will be taxed, especially when considering a move. This guide will meticulously break down which states offer a reprieve from state income tax on those crucial IRA distributions, helping you plan for a more financially secure retirement.
The Landscape of State Retirement Income Taxation
It's easy to get overwhelmed when you start looking into how states tax retirement income. Each state seems to have its own playbook, and what applies to one type of income doesn't necessarily apply to another. This is why digging into the specifics, like IRA distributions, is so important. You’ve spent decades contributing to these accounts, often with the understanding that you’d pay taxes later. Now that "later" is here, knowing the rules is your superpower.
Navigating Different Retirement Income Streams
When we talk about retirement income, we're not just talking about one big bucket. It's actually a collection of different streams, and states treat each one a little differently. You might have Social Security benefits, private pensions, government pensions (like federal FERS or CSRS, or state teacher pensions), 401(k) withdrawals, and, of course, IRA distributions.
For instance, many states don't tax Social Security benefits at all, even some that have robust income taxes on other forms of income. Then there are pensions, where some states offer significant exclusions or even full exemptions, especially for military or government pensions. Your 401(k) and IRA distributions often get lumped together because they share similar tax characteristics from a federal perspective – they were often funded with pre-tax dollars, and withdrawals are taxed as ordinary income. However, at the state level, these rules can diverge wildly. It's this patchwork of rules that makes planning so tricky, and why focusing on specific components like IRA distributions is a smart move for anyone looking to optimize their retirement finances. Understanding How Each State Taxes Retirement Income (50-State Guide) can be incredibly valuable here.
Why IRA Distributions Require Special Attention
IRA distributions, particularly from traditional IRAs, are a cornerstone of many retirees' income. The money you contributed was likely pre-tax, meaning you didn't pay income tax on it when you earned it or when it grew inside the account. The federal government taxes these withdrawals as ordinary income in retirement, but what about your state? This is where the landscape can get confusing and potentially costly.
Unlike Roth IRAs, where qualified distributions are generally tax-free (since contributions were made with after-tax dollars), traditional IRA withdrawals are fair game for state income taxes unless a specific exemption applies. And for many retirees, these distributions, especially once Required Minimum Distributions (RMDs) kick in at age 73, can form a significant portion of their annual income. Imagine doing all the hard work of saving, only to find a substantial chunk eaten away by unexpected state taxes. This is a common frustration, and it highlights why it’s so important to understand the state-level specifics, especially if you're eyeing a move to a new state for your golden years.
States That Completely Shield IRA Distributions from Income Tax
The ultimate goal for many retirees is to find a place where their hard-earned retirement income, including those crucial IRA distributions, won't be subject to state income tax. Thankfully, there are several states that fit this bill, falling into two main categories: those with no broad income tax whatsoever, and those that, despite having a general income tax, offer specific, sweeping exemptions for retirement income.
The No-Income-Tax Havens
Let's start with the most straightforward category: the states that simply don't levy a general state income tax on wages or retirement income. If a state doesn't have an income tax, it naturally follows that it won't tax your IRA distributions. These states are often popular destinations for retirees precisely for this reason.
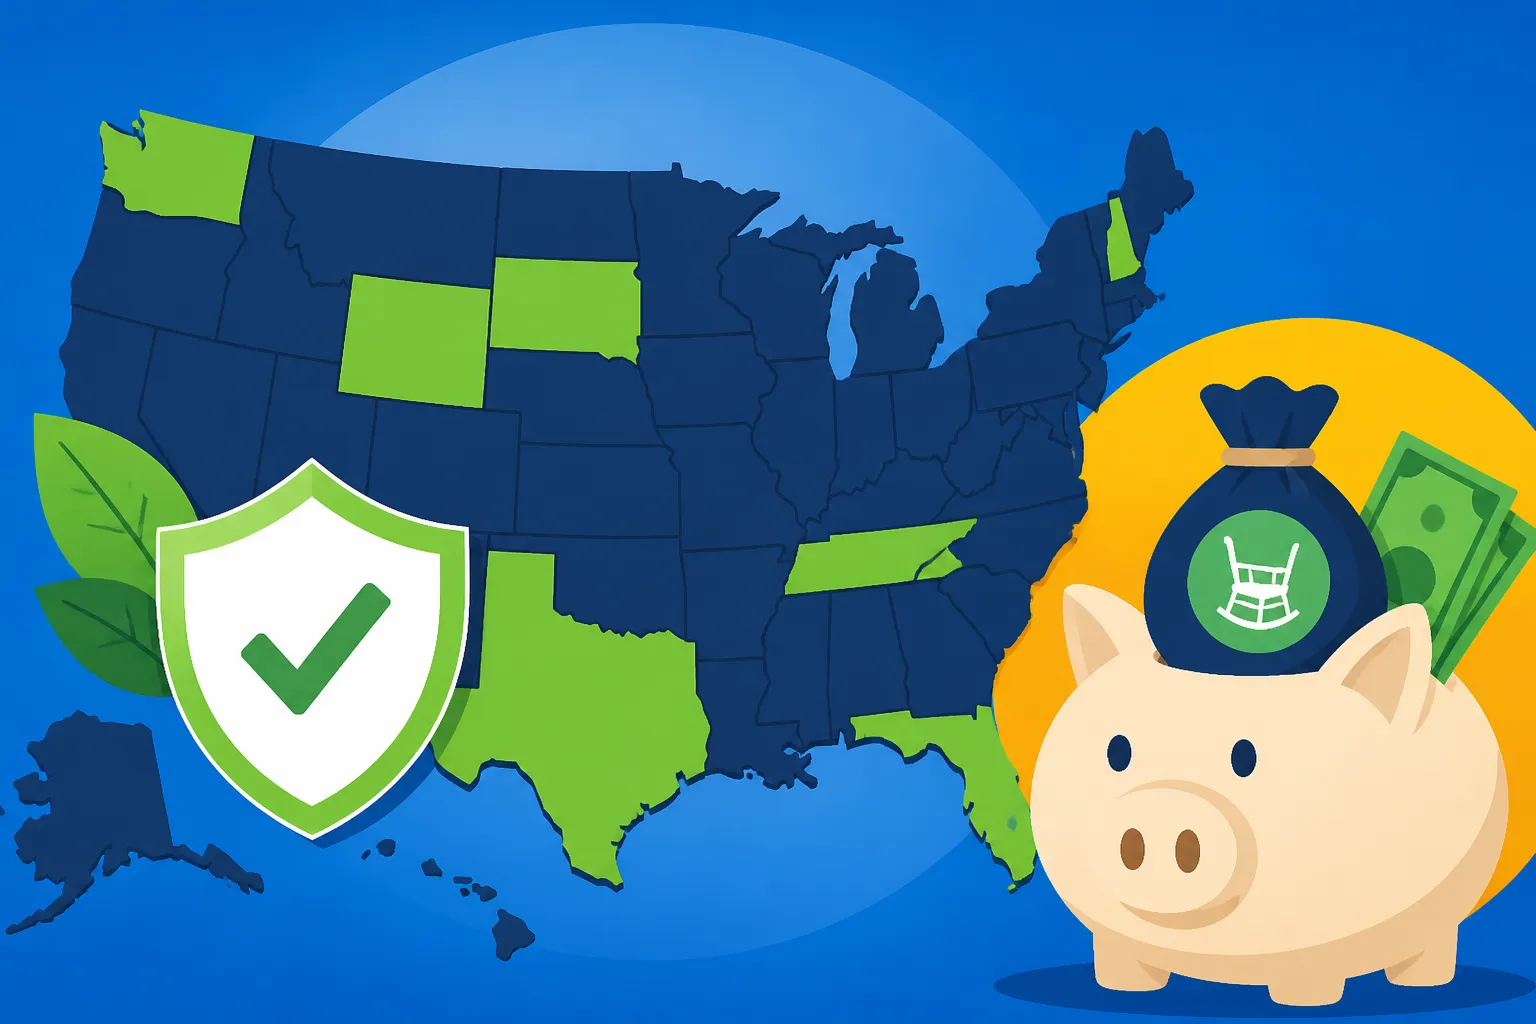
The nine states that currently have no state income tax are:
- Alaska: Known for its vast wilderness, Alaska also offers financial perks for residents, including no state income tax.
- Florida: A perennial favorite for retirees, Florida's sunny beaches come with the added bonus of no state income tax. Establishing residency here is a common strategy for those looking to avoid state income taxes. You can learn more about How to Establish Florida Domicile.
- Nevada: Beyond the bright lights of Las Vegas, Nevada offers residents a tax-friendly environment with no state income tax.
- South Dakota: The "Mount Rushmore State" is also a haven for those looking to keep more of their retirement income, as it has no state income tax.
- Tennessee: While Tennessee does have a Hall Income Tax on interest and dividends, it specifically repealed it for tax years beginning on or after January 1, 2021. So, for all intents and purposes, it's a no-income-tax state, meaning your IRA distributions are safe.
- Texas: The Lone Star State boasts no state income tax, making it a popular choice for many, especially those moving from high-tax states.
- Washington: Although Washington state enacted a capital gains tax, it still does not have a broad income tax on wages or retirement distributions, including IRAs.
- Wyoming: With its stunning natural beauty, Wyoming also offers the benefit of no state income tax.
- New Hampshire: Similar to Tennessee, New Hampshire has historically taxed interest and dividends, but it's phasing out that tax entirely by 2027. Crucially, it does not tax earned income or retirement distributions like those from an IRA. So, your IRA distributions are exempt from state income tax in New Hampshire. Check out New Hampshire Interest & Dividends Tax Repeal for more details.
For anyone looking to completely eliminate state income tax on their IRA distributions, these states are the obvious first stop. They offer a clear-cut advantage by simply not having the tax in the first place. You can find a complete listing of these no-income-tax states in our guide to States With No Income Tax (2026 Full List).
Income-Tax States with Full IRA Distribution Exemptions
Now, this is where it gets a little more nuanced, but equally important for retirees. Some states do have a state income tax on wages and other forms of income, but they offer broad exemptions specifically for retirement income, which includes IRA distributions. This means you could live in a state with an income tax but still not pay state tax on your IRA withdrawals if you meet their criteria.
Three standout states in this category are:
- Illinois: This is a big one. Illinois completely exempts all retirement income, including distributions from IRAs, 401(k)s, and private and public pensions, from state income tax. This is a massive benefit for retirees, allowing them to keep all of their retirement savings without state-level taxation, regardless of their income level.
- Mississippi: The Magnolia State is another excellent option. Mississippi exempts all qualified retirement income from state income tax, which includes distributions from IRAs, 401(k)s, and public and private pensions. This makes it a very attractive state for retirees who rely heavily on these accounts for their living expenses.
- Pennsylvania: For residents aged 59½ or older, Pennsylvania offers a full exemption on qualified retirement income, including distributions from IRAs and 401(k)s. This means that if you're a qualifying retiree, your IRA distributions will not be subject to Pennsylvania state income tax.
These states demonstrate that you don't necessarily have to move to a no-income-tax state to enjoy tax-free IRA distributions. Their specific exemptions for retirement income make them incredibly retiree-friendly. It's always wise to look up the specific details for the current tax year, but generally, these states have consistently offered these strong exemptions. For a broader perspective, you might want to look into States That Don't Tax 401(k) & IRA Withdrawals.
States Offering Partial Exemptions or Specific Deductions
Beyond the clear-cut cases of no income tax or full exemptions, many states operate in a middle ground. They do tax retirement income, including IRA distributions, but they also offer various forms of relief. This can come in the form of age-based exclusions, income-limited deductions, or other specific credits that can reduce your taxable burden. These states might not offer full exemption, but they can still be tax-friendly depending on your income level and age.
Age-Based and Income-Limited Exclusions
A significant number of states recognize the financial needs of retirees and offer specific exclusions or deductions for retirement income. These aren't blanket exemptions, but they can still substantially lower your state tax bill on IRA distributions.
Let's look at a few examples:
- Delaware: The First State allows residents aged 60 and over to exclude a certain amount of pension and eligible retirement income, which can include IRA distributions, from their state taxable income. This isn't an unlimited exemption, but it provides a meaningful break for many retirees.
- Colorado: Colorado offers a retirement income subtraction for individuals aged 55 and older, with different amounts for those 55-64 and those 65 and older. While it's not a full exemption for all IRA income, this subtraction can significantly reduce the taxable portion of your distributions. You can learn more about Colorado Retirement Subtraction ($20k/$24k).
- Georgia: For those 62 or older, Georgia offers a substantial exclusion for retirement income, which covers IRAs, pensions, and Social Security. The exclusion amount is quite generous (up to $65,000 per person in 2026), meaning many retirees could see a significant portion, if not all, of their IRA distributions effectively untaxed. Dive into Georgia $65,000 Retirement Exclusion (2026) for more specifics.
- New Jersey: The Garden State provides an exclusion for retirement income for those aged 62 or older, with the amount depending on your filing status and total income. While New Jersey has a reputation for being a higher-tax state, this exclusion can provide a notable tax break on IRA distributions for qualifying retirees. You can review New Jersey Retirement Income Exclusion for more details.
- Michigan: Michigan has been in the process of phasing out its tax on retirement income, including IRA distributions. For certain birth years, retirees may be eligible for significant deductions or exemptions, effectively making some or all of their retirement income untaxed. It’s a nuanced system that is worth exploring if you’re considering Michigan.
These states represent a compromise: they tax income, but they also provide specific mechanisms to ease the burden on retirees. It means doing a bit more homework to see if your specific income level and age qualify for these benefits, but the effort can definitely pay off. For more detailed insights into these benefits, our article on Retirement Income Exclusions by State is an excellent resource, as is Senior & Retirement Tax Exclusions by State.
Roth IRA Rules Across States
It's crucial to distinguish between traditional IRAs and Roth IRAs when discussing state taxation. For federal tax purposes, qualified Roth IRA distributions are entirely tax-free because you contributed after-tax dollars to the account. This generally holds true at the state level as well.
Most states follow the federal treatment of Roth IRAs, meaning that qualified distributions – those made after the five-year waiting period and after reaching age 59½, becoming disabled, or passing away – are not subject to state income tax. This is a huge benefit for those who have consistently funded their Roth accounts. However, non-qualified Roth distributions, which might include early withdrawals of earnings (not contributions), could potentially be subject to state income tax if the state doesn't have an explicit exemption. Thankfully, this is rare, but it's always good practice to double-check your specific state's rules, especially if you anticipate making non-qualified withdrawals. The general rule of thumb, though, is that if your Roth IRA distribution is tax-free federally, it's likely tax-free at the state level too.
Beyond IRA Distributions: A Holistic View of Retirement Taxes
While finding a state that doesn't tax your IRA distributions is a fantastic goal, it's crucial to remember that state income tax is just one piece of the larger financial puzzle. A truly "tax-friendly" state for retirement considers the entire spectrum of taxes you'll face. It's a common misconception that a state with no income tax is automatically the cheapest place to retire. This often isn't the case once you factor in other significant levies.
The Total Tax Burden: Sales, Property, and Estate Taxes
When evaluating a state for retirement, you absolutely need to look at the whole picture. States that forgo income tax often make up for it with higher sales taxes, property taxes, or other fees.
Consider this:
- Sales Tax: While you might not pay income tax on your IRA withdrawals, a high sales tax rate means every purchase you make—from groceries to a new appliance—will cost you more. For instance, while Florida has no state income tax, its combined state and local sales tax rates can be significant. Similarly, states like Washington, while income-tax-free, have some of the highest sales tax rates in the country.
- Property Tax: This can be a huge expense for homeowners in retirement. Some states with no income tax, like Texas, tend to have higher property tax rates to fund local services. Conversely, states with a moderate income tax might have lower property taxes. It's essential to understand the average property tax burden in specific areas you're considering. For example, Is Texas Really Tax Free? The Full Picture reveals that high property taxes can offset the lack of income tax. You should also be aware that some states offer Homestead Exemption by State or other property tax credits to seniors.
- Estate Tax/Inheritance Tax: While not an annual tax, some states levy estate or inheritance taxes, which can impact what your heirs receive. If leaving a legacy is important to you, this is another tax to consider.
The takeaway here is that a low or non-existent state income tax is wonderful, but it doesn't tell the whole story. A state like Hawaii, which has a progressive income tax, might still be more affordable in terms of overall tax burden for some retirees than a no-income-tax state with extremely high property taxes, depending on individual spending habits and assets. This is why resources like SmartAsset, with their "retiree tax-friendliness" rankings, can be invaluable. They provide a holistic view of the tax landscape, considering all these factors, helping you compare total tax burdens rather than just one component. Our guide on States With No Income Tax but High Other Taxes expands on this concept. Ultimately, for a truly tax-friendly retirement, you'll want to explore the Most Tax-Friendly States for Retirees 2027.
The Role of Required Minimum Distributions (RMDs) in State Tax Planning
Required Minimum Distributions (RMDs) are a critical factor for many retirees over age 73 (or 75 for those born in 1960 or later, thanks to SECURE Act 2.0). These are mandatory withdrawals from traditional IRAs, 401(k)s, and similar retirement accounts, designed to ensure that you eventually pay taxes on your pre-tax savings. The IRS sets these rules, and states generally follow suit in terms of recognizing the income.
The challenge with RMDs is that they force you to take income, whether you need it or not, and that income is taxable at both the federal and, often, state levels unless specific exemptions apply. If you're living in a state that fully taxes IRA distributions, RMDs will automatically increase your taxable income, potentially pushing you into a higher tax bracket or reducing your eligibility for other income-based deductions or credits.
For example, imagine you're living in a state that fully taxes IRA distributions, and your RMD is $30,000 this year. That $30,000 is added to your other income and taxed accordingly by the state. If you were instead living in Illinois or Florida, that $30,000 RMD would pass through without a state income tax hit. This stark difference underscores why knowing your state's stance on IRA distributions is so vital. Failing to plan for RMDs in a high-tax state can lead to unexpected tax bills and erode your retirement savings faster than anticipated. For comprehensive advice on managing these distributions, refer to our article on RMDs and State Taxes and strategies on How to Minimize State Taxes in Retirement.
| State Category | Examples (IRA Distributions) | State Income Tax | Sales Tax Rate (State) | Property Tax Burden (Approx. % of Home Value) | Social Security Taxed? |
|---|---|---|---|---|---|
| No Income Tax | Florida, Texas, Nevada, Washington, Wyoming, Alaska, South Dakota, Tennessee, New Hampshire | No | Varies (e.g., FL 6%, TX 6.25%, WA 6.5%) | Varies (e.g., TX High, WY Low, FL Moderate) | No |
| Income Tax, Exempts IRAs | Illinois, Mississippi, Pennsylvania (59.5+) | Yes | Varies (e.g., IL 6.25%, MS 7%, PA 6%) | Varies (e.g., IL High, MS Moderate, PA Moderate) | No |
| Income Tax, Partial Exemption | Delaware (60+), Colorado (55+), Georgia (62+), New Jersey (62+), Michigan | Yes | Varies (e.g., DE 0%, CO 2.9%, GA 4%, NJ 6.625%, MI 6%) | Varies (e.g., DE Moderate, CO Moderate, GA Moderate, NJ High, MI Moderate) | No (most) |
Note: Sales and Property Tax rates are approximations and can vary significantly by local jurisdiction and specific tax year. Social Security taxation refers to state-level taxes only.
Smart Planning for a Tax-Friendly Retirement
Navigating the complexities of state taxation in retirement can feel like a full-time job. But with a strategic approach, you can significantly optimize your financial picture. It's not just about picking a state; it's about making informed choices that align with your overall financial goals.
Establishing Legal Domicile and Residency
If you're planning to move to a state that offers favorable tax treatment for IRA distributions (or any other retirement income), simply buying a house there isn't enough. You need to officially establish domicile. Domicile is your true, fixed, and permanent home, the place you intend to return to whenever you are absent. States like California and New York, known for their rigorous residency audits, will look for concrete proof of your intent to abandon your old state and establish roots in your new one.
This means more than just changing your mailing address. You should take a series of deliberate steps, such as:
- Obtaining a new driver's license in the new state.
- Registering to vote in the new state.
- Registering your vehicles in the new state.
- Closing bank accounts in the old state and opening new ones.
- Changing your professional licenses (if applicable).
- Spending a significant portion of your time in the new state (often more than 183 days, though this is a guideline, not a strict rule for domicile).
- Updating your will and other legal documents to reflect your new residency.
Without a clear demonstration of intent to change your domicile, high-tax states may continue to assert you are a resident, thus attempting to tax your worldwide income, including those IRA distributions you thought were safe. Understanding the difference between Domicile vs Statutory Residency is crucial. For a comprehensive guide on making this transition smooth, our article on How to Change Your State Residency for Taxes is a must-read, particularly for those looking at Moving to Florida From New York: Taxes or Moving to Texas From California: Taxes.
Leveraging Expert Resources and Tools
The world of state retirement taxes is constantly evolving, with legislative changes happening all the time. This makes it challenging to stay on top of the latest rules and ensure you're making the most tax-efficient decisions. That's why leveraging expert resources and financial planning tools is not just helpful, it’s essential.
Online platforms like SmartAsset offer fantastic tools that can help you understand the tax implications of different states. Their "retirement tax-friendliness" tools can give you a personalized look at how various states would tax your specific income streams, including IRA distributions, pensions, and Social Security, as well as property and sales taxes. This kind of comprehensive overview is invaluable when you're making a big decision like where to retire.
Beyond online tools, don't underestimate the power of a qualified tax professional or financial advisor who specializes in retirement planning and multi-state tax issues. They can provide tailored advice based on your unique financial situation, helping you navigate complex state residency rules, understand the nuances of specific tax exclusions, and ensure you're compliant while maximizing your savings. An advisor can help you create a personalized strategy for Moving to a Tax-Friendly State for Retirement, ensuring that all aspects of your financial life, from IRA distributions to estate planning, are handled correctly. Their expertise can save you significant money and stress in the long run, making the investment well worth it.
Disclaimer
The information provided in this article is for informational purposes only and does not constitute financial, legal, or tax advice. Tax laws are complex and subject to change. It is essential to consult with a qualified financial advisor or tax professional to discuss your specific situation and ensure compliance with all applicable laws and regulations.