What States Should Retirees Avoid for Taxes?
Retirement is supposed to be a golden age, a time to relax and enjoy the fruits of your labor. But for many, the thought of navigating state taxes and making sure their hard-earned savings last can be a huge source of anxiety. It feels like every state has its own set of confusing rules, and trying to figure out where your money will go furthest is a daunting task. This guide is here to cut through that confusion, helping you identify states that might not be the most tax-friendly for retirees, so you can make informed decisions about where to spend your retirement years.
Understanding What Makes a State Less Tax-Friendly for Retirees
When you're planning your retirement, taxes are a major piece of the puzzle, and often, it's not just about a high state income tax rate. What really stings for retirees are states that relentlessly tax the very income sources you depend on – your Social Security, your pensions, and those hard-won 401(k) and IRA distributions. It's a frustrating reality that some states, unfortunately, cast a wider net when it comes to taxing these essential retirement funds.
How States Tax Retirement Income
One of the most critical factors in determining a state's tax-friendliness for retirees is how it treats various forms of retirement income. It's not a one-size-fits-all situation; some states are incredibly generous, while others take a significant bite out of every dollar. This distinction is paramount, especially when every penny counts in retirement.
Let's break it down:
- Social Security Benefits: The federal government taxes a portion of Social Security benefits if your combined income exceeds certain thresholds. However, most states thankfully do not tax these benefits. Yet, there are still a handful of states that choose to tax Social Security, often mirroring the federal rules or having their own set of exclusions. This can be a real hit to your fixed income. If a significant portion of your retirement relies on Social Security, these states could quickly become less appealing. You'll want to review the current list of states that still tax Social Security.
- Pension and Annuity Income: This is where things get really varied. Some states fully exempt all pension income, whether it's from a private employer, a government agency, or the military. Other states offer partial exemptions, often based on age or income level. Then there are those that tax pension income just like any other ordinary income, which can significantly reduce your take-home amount, especially if you have a substantial pension. It’s worth checking out which states don't tax pensions for a comparison.
- 401(k) and IRA Withdrawals: Generally, distributions from traditional 401(k)s and IRAs are taxed as ordinary income, both at the federal and state levels, because you contributed to them pre-tax. However, just like pensions, some states offer exemptions or deductions for these withdrawals, particularly for older taxpayers or those with lower incomes. Roth IRA withdrawals, on the other hand, are typically tax-free at both federal and state levels, provided you meet the requirements (age 59½ and account open for 5+ years).
- Other Investment Income: This includes things like interest, dividends, and capital gains from selling stocks, bonds, or other assets. Many states tax these types of income, though some have special provisions or lower rates for capital gains.
The complexity of these different income types means that simply looking at a state's overall income tax rate isn't enough. You need to dive into the specifics of your retirement income sources. For example, a state might have a low overall income tax rate, but if it taxes your military retirement income more aggressively than a neighboring state, it might not be the best fit for you. Financial resources like SmartAsset offer detailed state-by-state guides that can help illuminate these nuanced differences.
Other Tax Burdens Beyond Income
It’s easy to get fixated on income taxes, but savvy retirees know that the true tax burden is a complex beast, with other major players that can secretly eat away at your retirement budget. These often include property taxes and sales taxes, which can have a massive impact regardless of what your income tax situation looks like.
- Property Taxes: For many retirees, their home is their biggest asset and often their largest ongoing expense. Property taxes are levied at the local level (county, city, school district), and they can vary wildly even within the same state. A state with no income tax might have shockingly high property taxes. Imagine finally paying off your mortgage, only to face a property tax bill that feels like another monthly payment! This is a major concern, especially if you plan to age in place in an expensive area. States like New Jersey and Illinois, for instance, are known for their high property taxes, which can be a significant drain on a fixed income.
- Sales and Excise Taxes: These taxes are collected when you purchase goods and services. While they might seem minor compared to income or property taxes, they can add up, particularly for everyday necessities. Some states have high statewide sales tax rates, and many cities and counties add their own local sales taxes on top. Excise taxes are levied on specific goods like gasoline, tobacco, and alcohol. If you're someone who enjoys frequent shopping or drives a lot, these taxes can quietly erode your purchasing power. States without an income tax often rely heavily on sales and property taxes to fund their services.
- Estate and Inheritance Taxes: While not every retiree will be affected by these, they are a serious consideration for those planning to leave a substantial legacy. Estate taxes are levied on the value of a deceased person's estate before it's distributed to heirs. Inheritance taxes are paid by the heirs themselves on the assets they receive. Most states do not have these taxes, but a few still do, and their thresholds and rates can vary. If leaving an inheritance is important to you, and your estate is significant, you'll want to investigate these taxes carefully in any potential retirement state.
Specific States to Watch Out For: High-Tax Offenders for Retirement Income
When we talk about states that retirees should potentially avoid due to taxes, we're looking at a combination of factors. It's rarely just one type of tax but rather the cumulative effect of various levies that can make a state less appealing. Here, we'll dive into some specific examples and the reasons why they often land on the "less tax-friendly" list for retirees.
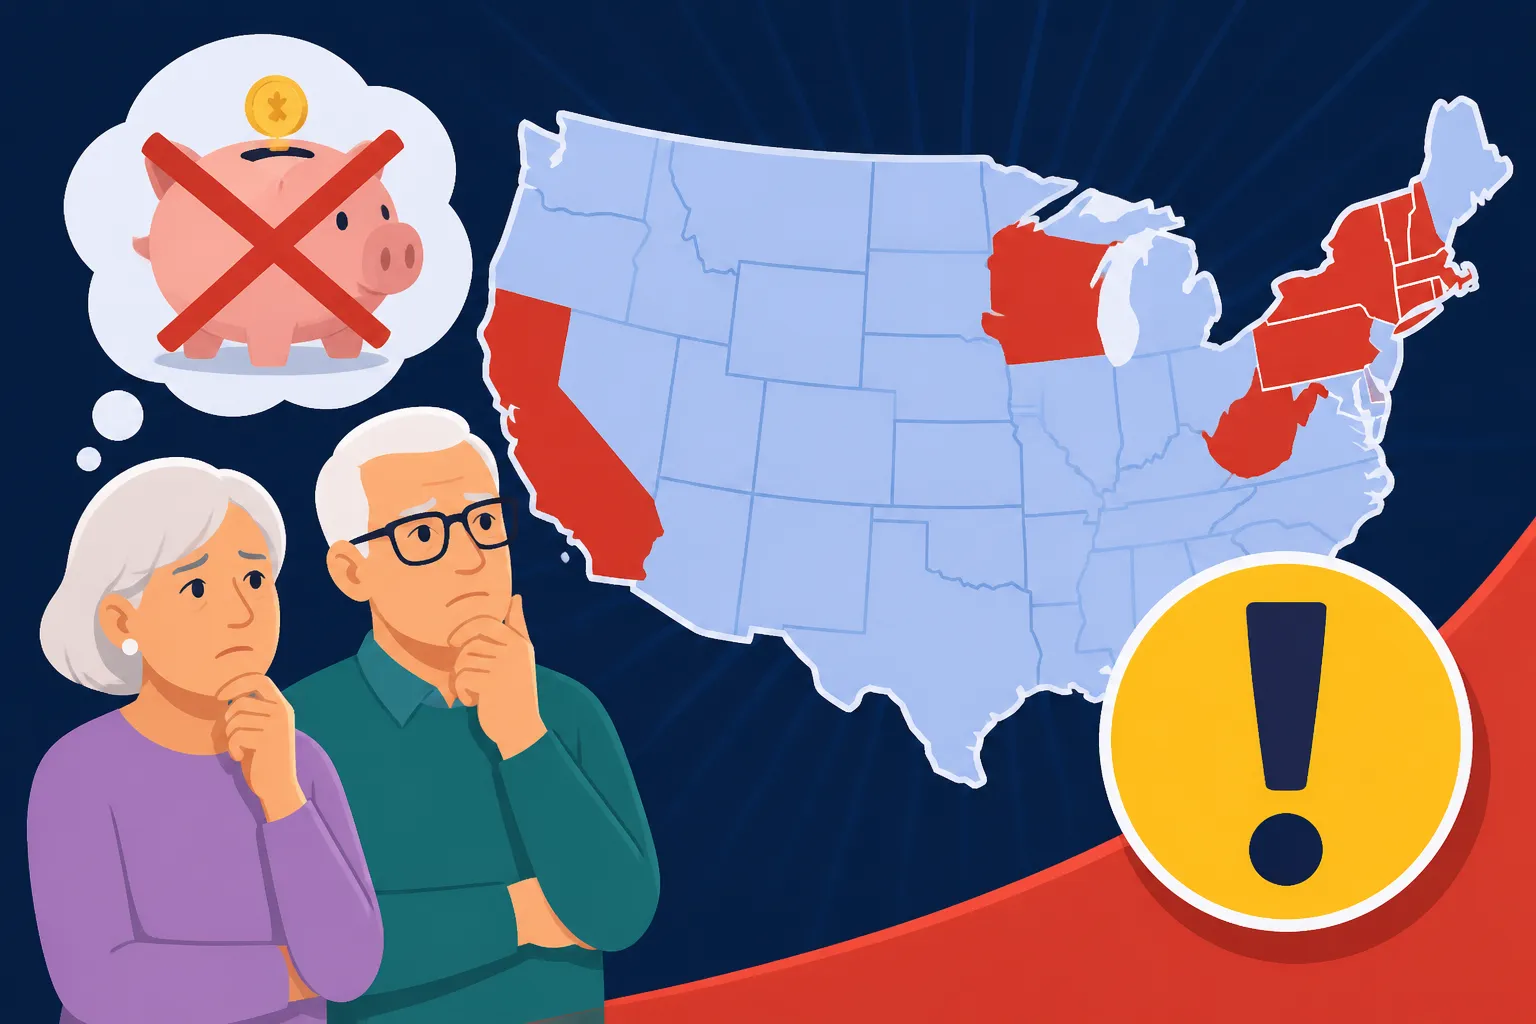
States That Tax All Major Retirement Income
These are the states that often cause the most sticker shock for retirees because they tax multiple forms of retirement income without offering broad exemptions.
- Connecticut: While it offers some exemptions for pension and annuity income based on income thresholds, Connecticut still taxes a portion of Social Security benefits for higher earners, and most other retirement income (like 401(k) and IRA distributions) is subject to its progressive income tax rates. When you combine this with relatively high property taxes in many areas, it can become quite expensive.
- Minnesota: Minnesota is another state that taxes Social Security benefits for many retirees, following a similar structure to federal taxation but with its own thresholds. Pensions and other retirement income are also generally subject to the state's progressive income tax. On top of that, Minnesota has relatively high sales taxes and can have significant property taxes.
- Vermont: This picturesque state often taxes Social Security benefits and does not offer broad exemptions for most other forms of retirement income like pensions or 401(k)/IRA withdrawals. Its top income tax rates can be quite high, which can take a considerable chunk out of retirement savings.
- Rhode Island: Similar to Vermont and Minnesota, Rhode Island also taxes Social Security benefits for many retirees. While it offers a small exclusion for certain pension income, most other retirement distributions are fully taxable under its progressive income tax structure. Like many New England states, it also has a relatively high cost of living and property taxes.
- Massachusetts: The Bay State has a flat income tax rate, but it generally taxes most forms of retirement income, including pensions and 401(k)/IRA distributions. While it does not tax Social Security benefits, the lack of broad exemptions for other retirement income, combined with high property taxes in desirable areas, can make it challenging for retirees.
It's important to note that tax laws are always changing, and states are constantly reviewing their policies. For the most up-to-date details on how each state taxes retirement income, you should consult an authoritative guide like a recent How Each State Taxes Retirement Income (50-State Guide) or States That Don't Tax Social Security (2027) before making any firm plans.
States with High Property Taxes Even Without Income Tax
Don't be fooled by the "no income tax" label. While a lack of state income tax is certainly appealing, other taxes can sneak up on you and make a state surprisingly expensive. Property taxes are often the biggest culprit here.
- New Hampshire: Often lauded for having no state income tax on wages (though it does tax interest and dividends above a certain threshold, though this is being phased out in New Hampshire Interest & Dividends Tax Repeal), New Hampshire offsets this with some of the highest property tax rates in the nation. If you own a home, especially a desirable one, your annual property tax bill could be substantial, potentially negating any income tax savings.
- Texas: Texas is famously one of the States With No Income Tax (2026 Full List). While this is a huge draw for many, especially those moving from high-income tax states, it relies heavily on property taxes to fund local services. Property tax rates in Texas can be quite high, particularly in growing metropolitan areas. For instance, a beautiful home in Dallas or Austin could come with a property tax bill that feels anything but tax-friendly.
- Florida: Another popular destination with no state income tax, Florida also leans on property taxes and sales taxes to generate revenue. While it offers some homestead exemptions, property values have soared in many parts of the state, leading to higher tax bills. The combination of high property insurance costs (especially for coastal properties) and property taxes can significantly impact a retiree's budget, even without an income tax.
The lesson here is clear: always look at the full tax picture. A state might boast "no income tax," but if its property taxes are through the roof, it might not be the tax haven you're dreaming of.
Beyond Income Tax: Other Financial Considerations for Retirees
Choosing a retirement location isn't just about the state income tax rate. It's a holistic decision where a number of other financial and lifestyle factors can either make or break your retirement dreams. Many people mistakenly believe that moving to a state with no income tax automatically solves all their financial woes. While it can certainly help, it's rarely the complete picture.
The True Cost of Living vs. Just Taxes
It's a common misconception: "I'll move to a no-income-tax state and save a fortune!" But often, what you save in income tax, you might end up paying in higher property taxes, sales taxes, or simply a higher overall cost of living. For example, Is It Cheaper to Live in a State With No Income Tax? is a question many retirees ponder, and the answer is often "it depends."
Consider the overall cost of living, which includes expenses like housing (rent or mortgage, plus property taxes and insurance), groceries, transportation, utilities, and healthcare. A state like Hawaii, despite having a relatively low tax burden for some retirement income, has an astronomically high cost of living, making it less affordable for many. Conversely, a state with a moderate income tax might have a much lower cost of living, allowing your retirement dollars to stretch further on everyday expenses. It’s a delicate balance, and sometimes paying a little more in income tax is worth it if your housing and other daily costs are significantly lower. Resources like SmartAsset provide detailed breakdowns of the cost of living by state, which can be incredibly helpful for this analysis.
Healthcare Costs and Accessibility
As we age, healthcare becomes an increasingly important consideration, and these costs can vary significantly from state to state. While Medicare provides federal coverage, out-of-pocket expenses, supplemental insurance premiums, and the quality and accessibility of healthcare services can differ. Some states have a more robust network of hospitals and specialists, while others might have longer wait times or fewer options, particularly in rural areas.
Think about proximity to doctors, specialists, and hospitals that can address your specific health needs. Even if a state is tax-friendly, if it means compromising on essential healthcare or traveling long distances for appointments, the financial savings might not be worth the trade-off in quality of life and peace of mind.
Proximity to Family and Social Networks
While not a direct tax factor, maintaining your social connections and being near family can have an indirect but profound impact on your retirement budget and overall well-being. Think about potential travel costs to visit children or grandchildren in another state. If you have to fly frequently, those airline tickets can add up quickly.
Furthermore, a strong local support system can be invaluable. If you're in a state where you have friends and family, you might spend less on social activities or rely on them for occasional help, reducing the need for paid services. Loneliness and isolation can also lead to increased healthcare costs and a diminished quality of life. The emotional benefits of being near loved ones often outweigh slight tax disadvantages for many retirees.
Making an Informed Decision: Research and Professional Guidance
Choosing where to retire is a monumental decision, blending financial savvy with personal lifestyle preferences. It's easy to get overwhelmed by all the information out there, but taking a structured approach can really simplify the process.
Utilizing Online Resources and Tools
The internet is a treasure trove of information, and many financial websites offer excellent tools to help retirees compare states. You'll find detailed breakdowns of tax policies, cost of living indices, and even quality of life metrics.
- Financial Calculators and Comparison Tools: Websites often feature interactive tools where you can input your estimated retirement income, asset values, and spending habits, and it will give you an estimated tax burden for different states. These are fantastic starting points to narrow down your options. Many reputable financial news sites and aggregators provide comprehensive charts and articles.
- State Government Websites: For the most accurate and up-to-date tax laws, always refer to the official Department of Revenue or Taxation website for each state you're considering. This is where you'll find the specific income tax brackets, exemptions for retirement income, property tax relief programs (like homestead exemptions for seniors), and sales tax rates. Don't rely solely on third-party summaries for the final word, as laws can change quickly.
- Relocation Guides and Lifestyle Blogs: Beyond taxes, consider what your day-to-day life will look like. Are there ample recreational activities? What's the climate like? How are the community services for seniors? Many websites and local chambers of commerce publish guides specifically for retirees considering a move to their area. This will help you weigh the Cost of Living vs Taxes by State.
Consulting a Tax Professional and Financial Advisor
While online resources are great for general information, your personal financial situation is unique. This is where professional advice becomes invaluable.
- Tailored Advice: A qualified tax advisor or financial planner specializing in retirement planning can analyze your specific income streams (Social Security, multiple pensions, investments, part-time work), your assets, and your spending patterns to give you truly personalized advice. They can help you understand the specific implications of moving from a state like New York to a state like Florida, considering both federal and state tax laws. They can model different scenarios for you, showing exactly how much you might save or spend in various states based on your numbers.
- Understanding State-Specific Nuances: Tax laws can be incredibly complex, with subtle differences that an untrained eye might miss. For instance, some states might have specific exclusions for military retirement pay, or offer generous credits for taxes paid to another state if you have income from multiple sources. A professional will be well-versed in these nuances and can guide you through them. They can also help you navigate complex situations like if you are considering Moving From California to Avoid State Tax, or if you plan to become a snowbird and divide your time between two states, which often involves intricate residency rules.
- Proactive Planning: It's not just about current taxes; it's also about future planning. A good advisor can help you understand how potential future tax changes might affect you, or how different withdrawal strategies from your retirement accounts could impact your state tax liability. They can help you proactively establish residency in your chosen state, ensuring you meet all the requirements to truly benefit from its tax policies.
"Test Driving" Your Potential Retirement State
Before you pack up your entire life, consider spending an extended period in your prospective retirement state. This can be one of the most practical steps you take.
- Rent Before You Buy: Instead of immediately buying a home, rent for six months to a year. This gives you time to experience the local rhythms, traffic patterns, weather changes, and assess the true cost of living beyond just the numbers. You'll get a real feel for the property taxes, utility costs, and even how much you're spending on groceries and entertainment in that specific area.
- Experience All Seasons: Taxes might be one thing, but living somewhere year-round is another. If you're considering a state with extreme temperatures, like Arizona or Minnesota, make sure you've experienced both the summer and winter. This helps ensure that the climate aligns with your lifestyle expectations, not just your tax goals.
- Engage with the Community: Join local clubs, volunteer, visit senior centers, and spend time in grocery stores and local parks. This gives you a chance to feel out the community, meet potential new friends, and see if the social scene is a good fit. After all, a tax-friendly state that leaves you feeling isolated might not be worth the financial savings.
By combining thorough research with professional guidance and a practical "test drive," you can confidently choose a retirement location that truly supports your financial well-being and enhances your quality of life. For more insights on this topic, you can also explore articles like Most Tax-Friendly States for Retirees 2027.
State Tax Considerations for Retirees: A Comparison Table
To give you a clearer picture, here's a simplified look at how some states that often pose tax challenges for retirees stack up across various tax categories. Remember, these are general observations, and your specific situation will always dictate the actual impact.
| State | Taxes Social Security? | Taxes Pensions/401(k)/IRA? | Average State Sales Tax Rate | Average Effective Property Tax Rate (as % of home value) |
|---|---|---|---|---|
| Connecticut | Yes (for higher earners) | Yes | 6.35% | 1.98% |
| Minnesota | Yes (for many retirees) | Yes | 6.88% | 1.05% |
| Vermont | Yes (for many retirees) | Yes | 6.00% | 1.83% |
| Rhode Island | Yes (for many retirees) | Yes | 7.00% | 1.55% |
| Massachusetts | No | Yes | 6.25% | 1.14% |
| New Hampshire | No (on wages) | Yes (on interest/dividends) | 0% (no sales tax) | 2.18% |
| Texas | No | No (no income tax) | 6.25% (up to 8.25% local) | 1.69% |
| Florida | No | No (no income tax) | 6.00% (up to 7.5% local) | 0.91% |
| Illinois | No | No | 6.25% (up to 11% local) | 2.05% |
Note: Sales and property tax rates are averages and can vary significantly by county and municipality. Property tax rates are sourced from recent data, but always verify specific rates for your desired location.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change. You should consult with a qualified tax professional or financial advisor for advice tailored to your specific situation.