States That Don’t Tax Social Security (2027)
The thought of retirement often brings with it dreams of golden years, relaxation, and finally having the freedom to enjoy your hard-earned savings. But for many, a nagging worry looms in the background: how much of that precious Social Security income will disappear into state income taxes? It's a common frustration, feeling like you've paid into the system your whole life, only to have another layer of taxation levied once you start receiving benefits. This comprehensive guide is here to shed light on exactly which states will allow you to keep your full Social Security benefits without a state income tax bite, helping you plan your retirement with greater clarity and peace of mind.
Understanding Social Security Taxation at the State Level
It's easy to get confused when it comes to taxes on Social Security. You might know that the federal government can tax a portion of your benefits, but then states add another layer of complexity. The reality is that state tax laws vary wildly, and what applies to your neighbor in another state might be completely different for you.
Why Some States Tax Social Security and Others Don't
The decision of whether to tax Social Security benefits at the state level often comes down to a state's overall revenue strategy and its philosophical approach to taxing its residents, particularly seniors. Historically, many states simply mirrored the federal taxation rules for Social Security, which began in 1983. If the federal government taxed a portion of your benefits, then so did the state. This was a relatively easy way for states to increase their tax base without creating an entirely new tax system from scratch.
However, over the years, as the retiree population grew and advocacy groups highlighted the financial strain on seniors, many states began to rethink this approach. Some states, especially those looking to attract retirees or reduce the tax burden on fixed-income residents, started to implement full or partial exemptions for Social Security benefits. This isn't just about being "nice"; it's often a calculated move to make a state more appealing for retirees who bring their savings and often spend them locally, contributing to the state's economy in other ways, such as through sales or property taxes. For instance, a state might choose to forgo income tax on Social Security but have higher property taxes to compensate.
The Federal Framework: It's Not Always Tax-Free
Before diving into state-specific rules, it's crucial to understand that even if your state doesn't tax Social Security, the federal government still might. This is a common point of confusion for many retirees. The federal government uses a calculation called "provisional income" to determine if any portion of your Social Security benefits will be subject to federal income tax.
Your provisional income is generally the sum of your adjusted gross income (AGI), any tax-exempt interest (like from municipal bonds), and half of your Social Security benefits. For 2026, the federal thresholds for taxing Social Security benefits are likely to remain similar to previous years, meaning:
- If your provisional income is between $25,000 and $34,000 for an individual, or between $32,000 and $44,000 for those filing jointly, up to 50% of your benefits may be taxable.
- If your provisional income exceeds $34,000 for an individual, or $44,000 for those filing jointly, up to 85% of your benefits may be taxable.
So, even if you live in a state like Florida, which has no state income tax, you could still be paying federal income tax on your Social Security benefits if your other income sources push you above these thresholds. It's a dual system, and understanding both the federal and state components is key to a complete picture of your retirement tax burden. You can find more details on how this works in our guide on Social Security Taxation: Federal + the 8 States.
The Golden List: States That Don't Tax Social Security in 2026
For many retirees, finding a state where their Social Security income is completely exempt from state taxes is a top priority. Thankfully, a significant number of states offer this benefit, either because they don't have a broad income tax to begin with, or they have specific exemptions for retirement income. This list includes a healthy majority of the United States.
The "No Income Tax" States: A Clear Win for Retirees
The easiest states to understand when it comes to Social Security taxation are those that simply don't have a state income tax at all. If there's no income tax, there's no mechanism to tax your Social Security benefits (or any other income, for that matter). This makes them incredibly attractive for retirees looking to maximize their take-home income.
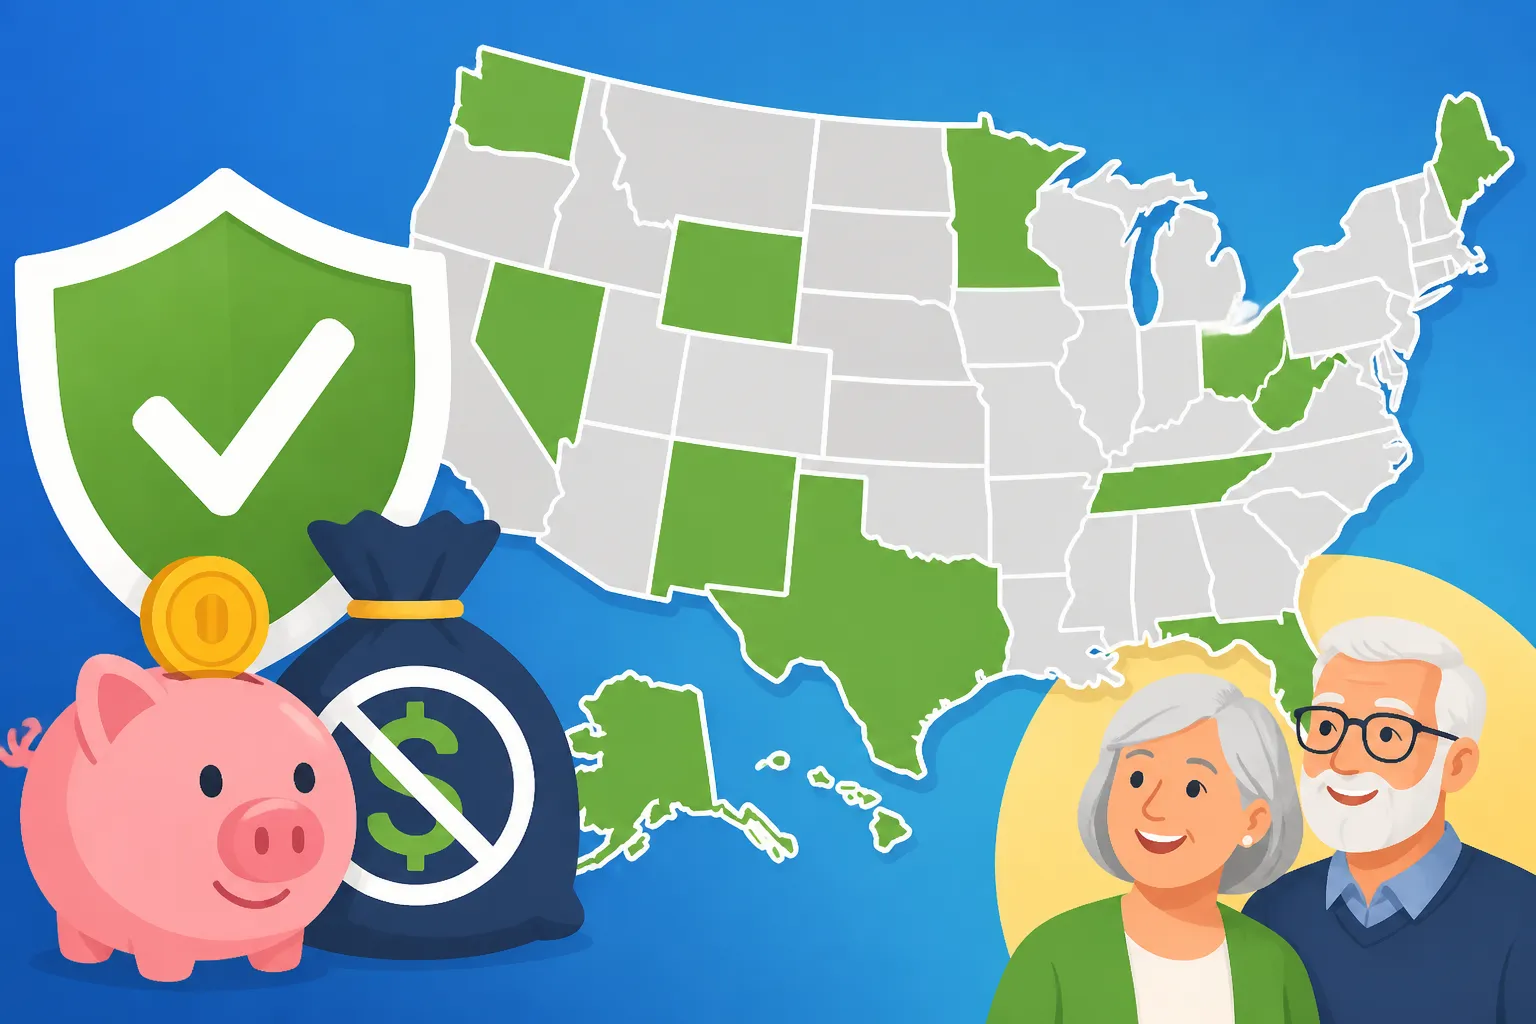
As of 2026, the following nine states are expected to maintain their status as states with no broad-based personal income tax:
- Alaska: Known for its vast wilderness and oil wealth, Alaska doesn't impose a state income tax.
- Florida: A perennial favorite for retirees, Florida boasts warm weather and no state income tax, making it a powerful draw. You can learn more in our guide, Does Florida Have State Income Tax?.
- Nevada: Famous for Las Vegas and stunning desert landscapes, Nevada is another state that offers freedom from state income tax.
- South Dakota: The Mount Rushmore State is known for its low taxes and no state income tax.
- Tennessee: Home of Nashville and the Great Smoky Mountains, Tennessee repealed its Hall Income Tax (which taxed interest and dividends) in 2021, leaving no broad income tax. You can explore Does Tennessee Have State Income Tax? for more details.
- Texas: The Lone Star State is another giant that doesn't levy a state income tax, though property taxes can be substantial. Check out Does Texas Have State Income Tax? for a full breakdown.
- Washington: While it has a capital gains tax, Washington state does not have a general state income tax.
- Wyoming: With its wide-open spaces, Wyoming is another state where residents don't pay state income tax.
- New Hampshire: While New Hampshire doesn't tax earned income, it historically taxed interest and dividends (the "Interest and Dividends Tax"). However, this tax is being phased out, making it effectively a no-income-tax state for most purposes by 2027. For 2026, it will continue its phase-out.
Living in one of these states means your Social Security benefits will be untouched by state income taxes. However, it's vital to remember that "no income tax" doesn't mean "no taxes." These states often rely more heavily on other forms of taxation, such as sales taxes, property taxes, and excise taxes, to fund public services. It's important to consider the full State Tax Burden by State 2026 when evaluating your options.
States with Specific Social Security Exemptions
Beyond the nine states with no income tax, many other states do impose a general state income tax but offer specific exemptions for Social Security benefits. This is fantastic news for retirees, as it means you can often live in a state with beautiful scenery, cultural amenities, or family connections, without your Social Security benefits being subject to state taxation. These exemptions can take various forms: a full exemption, an exemption based on age, or an exemption tied to certain income thresholds.
Here are some key examples of states that have a state income tax but fully or partially exempt Social Security benefits:
- Alabama: Alabama exempts Social Security benefits from state income tax.
- Arizona: Arizona generally exempts Social Security benefits from state income tax.
- Arkansas: Arkansas exempts Social Security benefits.
- California: California, despite its high income tax rates for other types of income, does not tax Social Security benefits. This is a common surprise for many!
- Delaware: Delaware fully exempts Social Security benefits from state income tax.
- Georgia: Georgia provides a substantial exclusion for retirement income, including Social Security, for taxpayers over 62 or totally disabled, meaning most Social Security benefits are not taxed.
- Hawaii: Hawaii exempts Social Security benefits.
- Idaho: Idaho exempts Social Security benefits.
- Illinois: Illinois is well-known for being very tax-friendly toward retirees, as it exempts all retirement income, including Social Security, from state income tax.
- Indiana: Indiana exempts Social Security benefits.
- Iowa: Iowa has phased out its state income tax on retirement income, including Social Security.
- Kentucky: Kentucky provides a significant exclusion for retirement income, which covers Social Security benefits.
- Louisiana: Louisiana exempts Social Security benefits from state income tax.
- Maine: Maine provides a deduction for Social Security benefits.
- Maryland: Maryland offers an exclusion for a portion of retirement income, including Social Security, for taxpayers meeting certain age and income requirements.
- Massachusetts: Massachusetts fully exempts Social Security benefits from state income tax.
- Michigan: Michigan generally exempts Social Security benefits, though some high-income earners may see a portion taxed depending on their age and total retirement income.
- Mississippi: Mississippi is very retirement-friendly, as it fully exempts all retirement income, including Social Security, from state income tax.
- New Jersey: New Jersey excludes Social Security benefits from state income tax for many retirees, especially those whose total income falls below certain thresholds.
- New York: While New York has a progressive income tax, it does not tax Social Security benefits. You can find more information about New York Income Tax Brackets 2026 and other exemptions.
- North Carolina: North Carolina does not tax Social Security benefits.
- North Dakota: North Dakota has recently implemented a full exemption for Social Security benefits.
- Ohio: Ohio generally exempts Social Security benefits from state income tax.
- Oklahoma: Oklahoma provides a deduction for Social Security benefits.
- Oregon: Oregon generally exempts Social Security benefits.
- Pennsylvania: Pennsylvania is one of the most retirement-friendly states, as it fully exempts all retirement income, including Social Security, pensions, and 401(k)/IRA distributions.
- South Carolina: South Carolina offers a significant deduction for retirement income that effectively exempts most Social Security benefits.
- Virginia: Virginia offers a substantial subtraction for retirement income, which typically covers Social Security benefits for most retirees.
- Wisconsin: Wisconsin generally exempts Social Security benefits from state income tax.
It's important to note that while these states exempt Social Security, their tax treatment of other retirement income, such as pensions or 401(k) withdrawals, can vary. Some may fully exempt all retirement income, while others may only exempt Social Security. For a deeper dive into how all states treat retirement income, our guide on How Each State Taxes Retirement Income (50-State Guide) is an invaluable resource.
States That Still Tax Social Security Benefits (and Why)
While the trend in recent years has been for states to either fully exempt Social Security benefits or phase out existing taxes on them, a handful of states still include a portion of these benefits in their taxable income. This can be a significant factor for retirees planning where to settle down, especially if Social Security makes up a substantial part of their retirement income.
The Remaining Few: Who They Are and Their Tax Structure
As of 2026, following several states' recent decisions to eliminate or significantly phase out their Social Security taxes, the list of states that still tax these benefits has become shorter. The remaining states generally do so by adopting tax rules similar to the federal government's provisional income calculations, or by applying their standard income tax rates to a portion of the benefits.
Based on current legislation and projections for 2026, here are the states that are expected to continue taxing Social Security benefits:
- Colorado: Colorado taxes Social Security benefits to some extent, though it offers a subtraction for some retirement income for those over age 55.
- Connecticut: Connecticut taxes Social Security benefits for individuals and couples above certain income thresholds.
- Minnesota: Minnesota is one of the states with a more aggressive approach to taxing Social Security, mirroring federal rules and taxing benefits above certain income levels.
- Montana: Montana taxes Social Security benefits in a similar fashion to the federal government, based on provisional income.
- New Mexico: New Mexico includes Social Security benefits in its taxable income, though it offers an exemption for low to middle-income seniors.
- Rhode Island: Rhode Island taxes Social Security benefits for those whose federal adjusted gross income (AGI) exceeds certain thresholds.
- Utah: Utah taxes Social Security benefits, though it offers a retirement tax credit that can reduce the impact for many seniors.
- Vermont: Vermont fully taxes Social Security benefits for higher-income individuals, while offering a phased-in exemption for those below specific income thresholds.
It's important to note that states like Kansas and Missouri, which previously taxed Social Security, have now repealed their taxes on these benefits, making the list of taxing states even smaller. Similarly, Nebraska has fully phased out its tax on Social Security, and West Virginia is on a path to fully phasing out its tax on Social Security and other retirement income by 2026. This trend highlights the dynamic nature of state tax laws and the increasing desire among states to be more attractive to retirees. You can find more specific details on this evolving landscape in our article on The 8 States That Still Tax Social Security.
Understanding the "Taxable Portion" in These States
Even in the states that do tax Social Security benefits, it's very rare for all of your benefits to be subject to state income tax. Just like the federal system, these states typically have their own set of rules, exemptions, and income thresholds that determine how much of your Social Security will actually be included in your taxable income.
For example, a state might adopt a system where:
- Income Thresholds Apply: Similar to the federal rules, only benefits above a certain provisional income level become taxable. For instance, in Colorado, you might get a significant retirement income subtraction if you're over a certain age, which effectively shields a large portion of your Social Security income from state tax.
- Age-Based Exemptions: Some states might offer a larger exemption or completely exclude Social Security once you reach a certain age, such as 65 or 67.
- Tax Credits: Rather than a direct exemption, a state might offer a tax credit for retirement income, which can offset the tax liability on your Social Security benefits. Utah, for example, uses a retirement tax credit that can significantly reduce what retirees owe.
- Sliding Scales: The percentage of benefits taxed might increase as your income rises, mirroring the progressive nature of many state income tax systems.
Let's consider a hypothetical scenario: Sarah lives in a state that taxes Social Security. She receives $20,000 in Social Security benefits annually. The state's tax law might state that the first $10,000 of Social Security benefits are exempt, and 50% of the benefits above that amount are taxable. In this case, only $5,000 (50% of $10,000) of her Social Security benefits would be added to her taxable income for state purposes, not the full $20,000. It's crucial to look at each state's specific guidelines, as these details can make a significant difference in your actual tax bill. Often, states provide tables or calculators on their Department of Revenue websites, or a tool like SmartAsset's retirement tax calculator can give you an initial estimate.
Important Considerations Beyond Just Social Security Tax
While understanding how your Social Security benefits are taxed at the state level is a huge piece of the retirement planning puzzle, it's far from the only factor. Focusing solely on this one aspect can lead to an incomplete and potentially misleading picture of your overall financial well-being in retirement. Savvy retirees know they need to look at the entire tax landscape and broader financial implications of their chosen location.
The Full Tax Picture: Sales, Property, and Other Levies
It's a common misconception that states with no income tax are always the cheapest places to live from a tax perspective. This simply isn't true. States need revenue to fund schools, infrastructure, public safety, and other services. If they don't get it from income tax, they'll often make it up elsewhere. This means a seemingly "tax-friendly" state might hit you hard in other areas.
Consider these common culprits:
- Property Taxes: States like Texas and Florida, which boast no state income tax, tend to have some of the highest property tax rates in the nation. If you own a home, especially a valuable one, these taxes can quickly erode any savings from not paying state income tax on your Social Security. For example, a retiree moving from a high-income-tax state with low property taxes, like California, to Texas might find their income tax savings eaten up by a substantially higher property tax bill. It's essential to research Property Tax Credits & Homestead Exemptions by State in any potential new home state.
- Sales Taxes: Many no-income-tax states, like Washington or Tennessee, rely heavily on sales tax. While you might not pay tax on your income, every purchase you make, from groceries to home goods, will incur a sales tax. This can disproportionately affect those on fixed incomes who spend a larger percentage of their income on consumer goods.
- Excise Taxes: These are taxes on specific goods, like gasoline, tobacco, or alcohol. While generally not as impactful as property or sales taxes for most retirees, they add to the overall cost of living.
- Estate or Inheritance Taxes: A few states still levy these taxes, which can impact your beneficiaries after you're gone. While not directly affecting your retirement income, they are part of the broader tax environment to consider for your estate planning.
The bottom line is that you need to calculate your effective overall tax burden – how much of your total income and assets are going towards state and local taxes, regardless of the category. A state might not tax Social Security, but if its property taxes are so high that they force you to downsize or struggle to afford your home, it's not truly tax-friendly for your situation.
Retirement Income Exclusions and Other Senior Benefits
Beyond Social Security, many states offer a variety of tax breaks specifically designed for seniors or those with retirement income. These can be just as significant, if not more so, than the Social Security exemption itself.
Common examples include:
- Pension and 401(k)/IRA Exclusions: Many states that do have an income tax choose to exempt or provide a large deduction for private or public pension income, as well as withdrawals from 401(k)s, IRAs, and other qualified retirement plans. For example, Pennsylvania not only exempts Social Security but also most other forms of retirement income, making it incredibly attractive. Similarly, states like Mississippi and Illinois offer broad exemptions for all retirement income. You can dive deeper into this topic with our guide on States That Don't Tax Pensions (2026).
- Age-Based Deductions or Credits: Some states provide an additional standard deduction or a specific tax credit simply for being over a certain age (e.g., 65 or 62). This reduces your taxable income, regardless of the source.
- Homestead Exemptions or Property Tax Relief: While not directly related to income tax, many states offer property tax breaks for seniors, disabled veterans, or those with low incomes. These can significantly reduce your property tax bill, making a state more affordable even if its baseline property tax rates are high.
- Other Specific Credits: Some states have unique credits for things like medical expenses, dependent care for seniors, or even credits for volunteers.
It's crucial to look at the full suite of tax benefits available. For instance, a state might tax a small portion of your Social Security but then give you a huge exclusion for your pension income and a substantial property tax break. To understand the complete picture of all the potential savings available, our Retirement Income Exclusions by State guide provides a detailed state-by-state breakdown. This comprehensive view is essential for making an informed decision about your ideal retirement location.
Strategizing Your Retirement Location: What Matters Most
Deciding where to spend your retirement years is a deeply personal choice, and it's one of the most significant financial and lifestyle decisions you'll ever make. While taxes play a crucial role, fixating on a single tax factor like Social Security taxation can lead you astray. A truly effective retirement strategy considers your entire financial profile, your lifestyle preferences, and the ever-changing economic landscape.
Evaluating Your Personal Financial Situation
Every retiree's financial situation is unique, and what works for one person might be disastrous for another. That's why a blanket recommendation for "the best state for retirees" is rarely accurate. You need to put your numbers into the equation.
Ask yourself:
- What are all your income sources? Beyond Social Security, do you have a private pension, a government pension, annuities, 401(k) or IRA distributions, rental income, or investment income? Each of these sources might be taxed differently by various states. A state that doesn't tax Social Security might still tax your pension or your IRA withdrawals. Our guide on States That Don't Tax 401(k) & IRA Withdrawals can help you understand these nuances.
- What is the distribution of your assets? Do you have significant real estate holdings that would be subject to property tax? Are you heavily invested in stocks that generate capital gains, which some states tax more aggressively than others?
- How much flexibility do you have? Are you able to make substantial changes to your spending habits, or are you on a very tight fixed income?
- What are your current and projected healthcare costs? Healthcare is a massive expense for many retirees, and while state taxes don't directly impact this, the cost of living in general can.
This holistic view is paramount. For instance, if Social Security makes up 80% of your income, then finding a state that doesn't tax it is a huge win. But if you have a massive private pension and your Social Security is a smaller portion, then a state that fully exempts all pension income might be more advantageous, even if it taxes a sliver of your Social Security. Using online tools, like those offered by SmartAsset, can help you plug in your specific numbers and get a personalized estimate of your total tax burden in different states. This kind of detailed analysis is what truly helps you pinpoint the Most Tax-Friendly States for Retirees 2027 for your specific circumstances.
The Role of Cost of Living and Lifestyle
Taxes are only one piece of the puzzle; the cost of living and your desired lifestyle are equally, if not more, important. What's the point of saving a few hundred dollars in state taxes if your housing costs are so exorbitant that you can't afford to live comfortably, or if the climate makes you miserable?
Think about these lifestyle factors:
- Housing Costs: This is often the single largest expense for retirees. A state with no income tax might have significantly higher home prices or property taxes that negate any income tax savings. Conversely, a state with a modest income tax might offer more affordable housing.
- Healthcare Access and Costs: As we age, access to quality healthcare becomes critical. Consider the availability of specialists, reputable hospitals, and the overall cost of healthcare services and insurance in a state.
- Proximity to Family and Friends: For many, being near loved ones is non-negotiable. If your entire family is in a state with higher taxes, the emotional cost of moving far away might outweigh any financial savings.
- Climate and Environment: Do you dream of warm beaches, snowy mountains, or a temperate climate with four distinct seasons? Your personal preferences for weather and outdoor activities should play a significant role.
- Amenities and Activities: What do you want to do in retirement? Do you need access to cultural institutions, golf courses, hiking trails, a vibrant downtown, or quiet rural living? The availability and cost of these amenities vary widely.
- Transportation: Will you rely on public transport, or do you need a car? How walkable are the communities? What are gas prices like?
Our guide on Cost of Living vs Taxes by State delves into how these elements intertwine. It emphasizes that a state with a low tax burden might have a high cost of living, making it less "affordable" overall than a state with slightly higher taxes but lower everyday expenses. For example, moving from New York to Florida might offer significant tax savings, but you need to compare everything from insurance rates to utility costs.
When a State Changes Its Tax Laws
One crucial aspect of long-term planning is understanding that tax laws are not static. They can, and do, change. What's true for 2026 might not be true for 2030 or 2035. Political climates shift, economic conditions evolve, and states are constantly evaluating their revenue needs and competitiveness.
We've seen this dynamic play out dramatically with Social Security taxation recently:
- Missouri and Nebraska have both completely repealed their state income tax on Social Security benefits in recent years, effective for 2024.
- West Virginia is currently phasing out its tax on Social Security and other retirement income, with a full exemption expected to be in place for 2026.
- Iowa also recently enacted legislation to fully eliminate its state income tax on retirement income, including Social Security.
These changes are great news for retirees in those states, but they also serve as a reminder that tax planning isn't a "set it and forget it" task. Staying informed about potential State Income Tax Cuts & Changes for 2026 or increases is an ongoing process. Subscribe to state Department of Revenue newsletters, follow reputable financial news sources, and consult with a tax professional regularly. A state that is ideal for you today might become less so in a decade, or vice versa, if laws change significantly.
Planning Your Move: Establishing Residency for Tax Benefits
If you're considering moving to a state with more favorable tax laws for retirees, simply packing your bags and driving across state lines isn't enough to magically change your tax residency. States, especially those with high income taxes like California or New York, are very diligent about ensuring you've truly cut ties before they stop trying to collect their share. Establishing genuine residency for tax purposes requires deliberate action and a clear demonstration of intent.
Domicile vs. Statutory Residency: Understanding the Nuances
Before you even start thinking about moving, you need to understand two critical terms in state tax law: "domicile" and "statutory residency." Many people conflate these, but they are distinct, and understanding the difference is key to avoiding costly tax mistakes.
- Domicile: This is your true, fixed, and permanent home – the place where you intend to return whenever you are absent. It's about your subjective intent to make a place your principal establishment. You can only have one domicile at a time. Your domicile is where you vote, register your car, get your driver's license, and maintain your primary social and financial ties. When you move, you must demonstrate a clear intent to abandon your old domicile and establish a new one. It's less about where you spend most of your time and more about where you intend to reside indefinitely.
- Statutory Residency: This is a more objective test based on physical presence. Even if you claim your domicile is in a no-income-tax state, you can still be deemed a "statutory resident" of another state if you spend enough time there. For many states, this means spending more than 183 days (roughly six months) within their borders and maintaining a "permanent place of abode" (like an apartment or a house you own or rent) in that state. If you meet the statutory residency test, that state can treat you as a resident for tax purposes, regardless of your stated domicile. This is particularly relevant for "snowbirds" who split their time between a northern home and a southern retreat.
The interplay between these two concepts is where it gets tricky. You might successfully establish a new domicile in Florida, but if you still spend more than 183 days a year at your old home in New York, New York might consider you a statutory resident and continue to tax your income. Our detailed guide, Domicile vs Statutory Residency, provides an in-depth explanation of these critical definitions.
Key Steps to Prove New Residency
To successfully change your state residency for tax purposes and avoid potential audits or double taxation, you need to take concrete steps that demonstrate your intent to abandon your old state and establish your primary home in the new one. The more "domicile tie-breakers" you establish in your new state, and the more you sever in your old state, the stronger your case will be.
Here's a checklist of actions to consider:
- Register to Vote: Register to vote in your new state and de-register in your old one.
- Driver's License and Vehicle Registration: Obtain a new driver's license in your new state and change your vehicle registration. This is a very strong indicator.
- Bank Accounts: Close accounts in your old state and open new primary bank accounts in your new state.
- Professional Licenses and Memberships: Change any professional licenses or memberships to your new state.
- Mail and Address Changes: File a change of address with the U.S. Post Office and update your address with all financial institutions, subscriptions, and important contacts.
- Estate Planning Documents: Update your will, trusts, and power of attorney to reflect your new state of residence and its laws.
- Medical and Dental Providers: Establish relationships with doctors, dentists, and other healthcare providers in your new state.
- Social and Religious Affiliations: Join clubs, religious organizations, or civic groups in your new state.
- Utilities: Transfer utility bills for your primary residence to your name in the new state.
- File a Declaration of Domicile: Some states, like Florida, have a specific "Declaration of Domicile" form you can file, which is a powerful statement of intent.
- Physical Presence: Crucially, spend more than half the year (at least 183 days) in your new state, and keep meticulous records (utility bills, credit card statements, travel logs) to prove it. Conversely, try to spend less than the statutory residency threshold in your old state.
States with high income taxes are notorious for conducting residency audits, especially if they suspect you've moved primarily to avoid taxes. They will look for any lingering ties to your old state. For instance, the California Franchise Tax Board (FTB) or the New York Department of Taxation and Finance can be very aggressive. The goal is to create an "overwhelming preponderance of evidence" that your new state is your true home. Our guide on How to Change Your State Residency for Taxes offers a step-by-step approach to navigate this complex process effectively.
State-by-State Social Security Tax Status (2026 Summary)
To provide a quick overview, here's a table summarizing the expected Social Security tax status for all U.S. states in 2026. Keep in mind that tax laws are dynamic, and while this reflects current projections and trends, it's always wise to verify with the specific state's tax department for the most up-to-the-minute information.
| State | Taxes Social Security (Yes/No) | Notes |
|---|---|---|
| Alabama | No | Fully exempts Social Security benefits. |
| Alaska | No | No state income tax. |
| Arizona | No | Fully exempts Social Security benefits. |
| Arkansas | No | Fully exempts Social Security benefits. |
| California | No | Fully exempts Social Security benefits. |
| Colorado | Yes (Partial) | Taxes Social Security, but offers a subtraction for some retirement income for those over age 55. |
| Connecticut | Yes (Partial) | Taxes Social Security for individuals/couples above certain income thresholds. |
| Delaware | No | Fully exempts Social Security benefits. |
| Florida | No | No state income tax. |
| Georgia | No | Provides a substantial exclusion for retirement income, including Social Security, for taxpayers over 62 or totally disabled. |
| Hawaii | No | Fully exempts Social Security benefits. |
| Idaho | No | Fully exempts Social Security benefits. |
| Illinois | No | Fully exempts all retirement income, including Social Security. |
| Indiana | No | Fully exempts Social Security benefits. |
| Iowa | No | Fully exempts all retirement income, including Social Security (effective 2023 tax year for 2024 returns, so also for 2026). |
| Kansas | No | Fully repealed tax on Social Security benefits (effective 2024). |
| Kentucky | No | Provides a significant exclusion for retirement income, which covers Social Security benefits. |
| Louisiana | No | Fully exempts Social Security benefits. |
| Maine | No | Provides a deduction for Social Security benefits. |
| Maryland | No | Offers an exclusion for a portion of retirement income, including Social Security, for taxpayers meeting age and income requirements. |
| Massachusetts | No | Fully exempts Social Security benefits. |
| Michigan | No | Generally exempts Social Security benefits, though some higher earners may see a portion taxed depending on age and total retirement income. |
| Minnesota | Yes (Partial) | Taxes Social Security benefits above certain income levels, mirroring federal rules. |
| Mississippi | No | Fully exempts all retirement income, including Social Security. |
| Missouri | No | Fully repealed tax on Social Security benefits (effective 2024). |
| Montana | Yes (Partial) | Taxes Social Security benefits similarly to the federal government, based on provisional income. |
| Nebraska | No | Fully phased out tax on Social Security benefits (effective 2024). |
| Nevada | No | No state income tax. |
| New Hampshire | No | No broad state income tax; interest & dividends tax phasing out (will be fully repealed by 2027). |
| New Jersey | No | Excludes Social Security benefits for many retirees, especially those whose total income falls below certain thresholds. |
| New Mexico | Yes (Partial) | Includes Social Security benefits in taxable income, but offers an exemption for low to middle-income seniors. |
| New York | No | Fully exempts Social Security benefits. |
| North Carolina | No | Fully exempts Social Security benefits. |
| North Dakota | No | Fully exempts Social Security benefits. |
| Ohio | No | Fully exempts Social Security benefits. |
| Oklahoma | No | Provides a deduction for Social Security benefits. |
| Oregon | No | Generally exempts Social Security benefits. |
| Pennsylvania | No | Fully exempts all retirement income, including Social Security. |
| Rhode Island | Yes (Partial) | Taxes Social Security benefits for those whose federal AGI exceeds certain thresholds. |
| South Carolina | No | Offers a significant deduction for retirement income that effectively exempts most Social Security benefits. |
| South Dakota | No | No state income tax. |
| Tennessee | No | No state income tax (Hall Income Tax on interest/dividends repealed). |
| Texas | No | No state income tax. |
| Utah | Yes (Partial) | Taxes Social Security benefits but offers a retirement tax credit to reduce the impact for many. |
| Vermont | Yes (Partial) | Fully taxes Social Security benefits for higher-income individuals, with a phased-in exemption for those below specific income thresholds. |
| Virginia | No | Offers a substantial subtraction for retirement income, which typically covers Social Security benefits for most retirees. |
| Washington | No | No state income tax (has a capital gains tax). |
| West Virginia | No (Phasing out) | Phasing out tax on Social Security and other retirement income; expected to be fully exempt by 2026. |
| Wisconsin | No | Fully exempts Social Security benefits. |
| Wyoming | No | No state income tax. |
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute tax or financial advice. Tax laws are complex and subject to change. It is highly recommended to consult with a qualified tax professional or financial advisor for personalized advice regarding your specific situation and retirement planning.