Best States for High Earners (Tax)
If you have finally reached that high-earner bracket after years of grinding, seeing a massive portion of your bonus or monthly commission disappear into state coffers can be a soul-crushing experience. This guide breaks down the complex landscape of state taxation specifically for high net worth individuals, identifying the most strategic locations to protect your hard-earned wealth and minimize your effective tax rate across the United States.
The Zero-Tax Havens for High Earners
When you are earning a significant income, the most immediate way to see a massive jump in your take-home pay is to relocate to a state that simply does not collect personal income tax. This isn't just about saving a few thousand dollars; for those in the seven-figure range, it can mean hundreds of thousands of dollars in annual savings. These states have become magnets for tech founders, executive leaders, and specialized professionals who are tired of the aggressive tax structures found in the Northeast or along the Pacific coast.
Analyzing the No-Income-Tax Giants
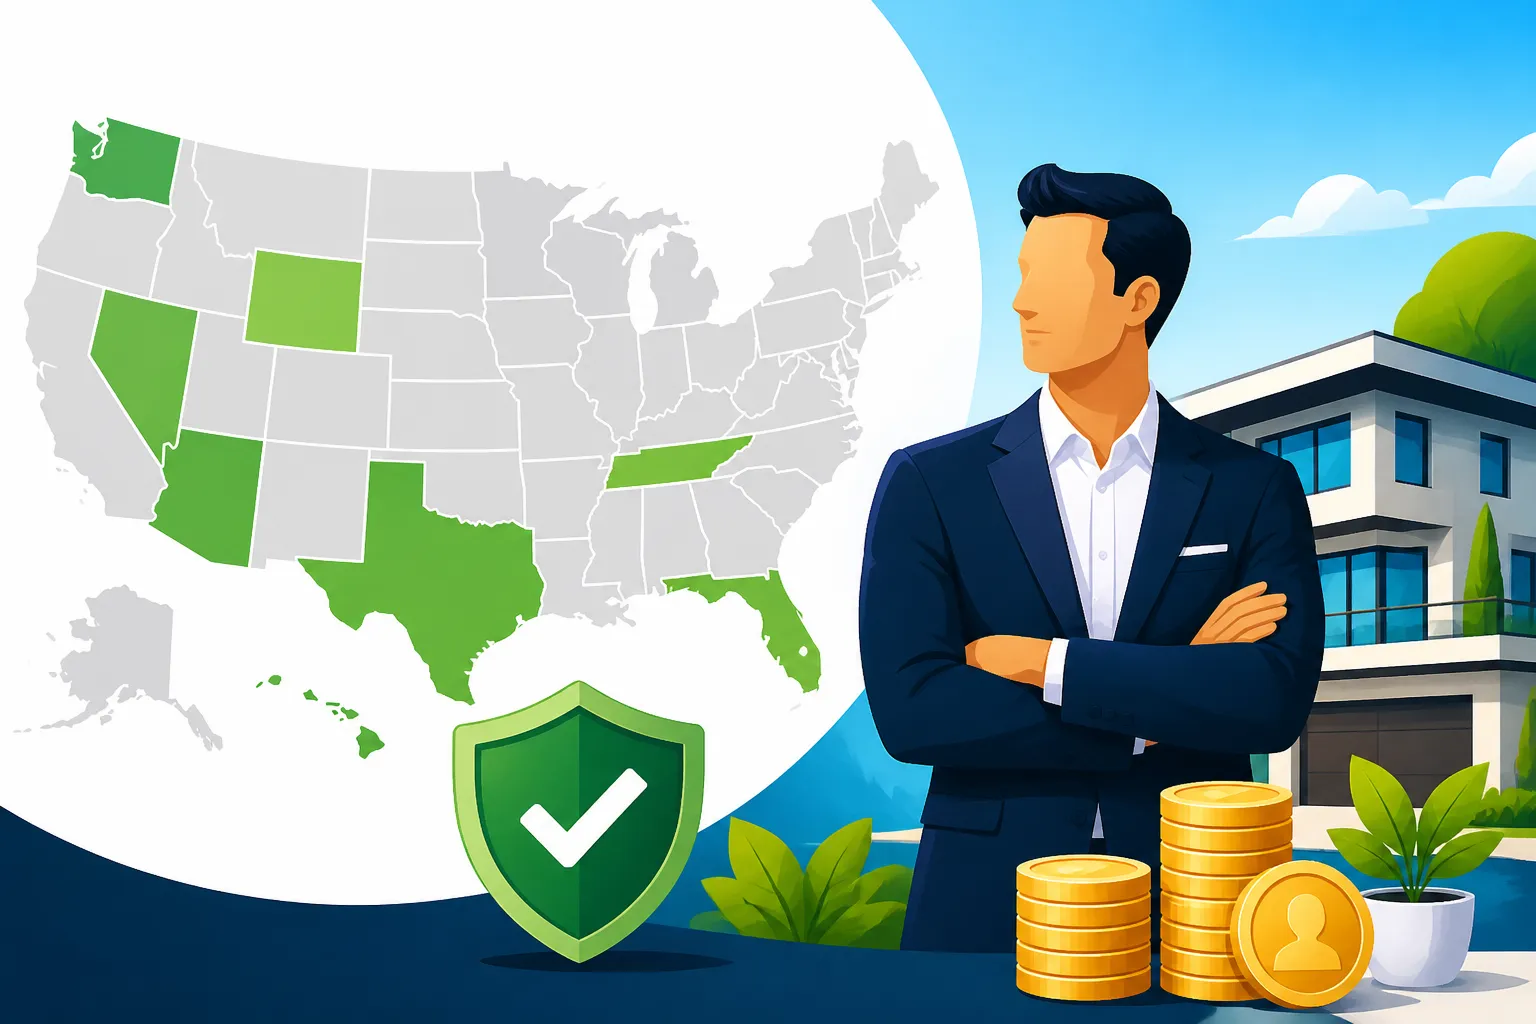
Florida, Texas, and Nevada are the "Big Three" when it comes to attracting high earners. Florida, in particular, has seen a massive influx of wealth into areas like Brickell and West Palm Beach, largely because the state constitution makes it incredibly difficult to ever implement an income tax. When you use a tool like SmartAsset to run the numbers, the difference between a $500,000 salary in Miami versus New York City is staggering. Beyond the base salary, Florida is also incredibly friendly toward investment income, which is a key factor for those who derive their wealth from capital gains or dividends.
Texas offers a similar allure, especially for those in the energy and tech sectors. While the state relies heavily on sales and property taxes, the lack of an income tax means your primary wealth-building tool—your salary—remains untouched at the state level. You can see more about the nuances of this in our guide on Is Texas Really Tax Free? The Full Picture. For high earners, the trade-off is often worth it, as property taxes can be managed by choosing more modest primary residences while letting the bulk of your income grow in tax-advantaged accounts or private investments.
The Hidden Costs and Trade-offs
It is vital to remember that "no income tax" does not mean "no taxes." These states have to fund their infrastructure somehow, and they usually do so through higher sales taxes or property taxes. For a high earner who spends a lot on luxury goods or owns a multi-million dollar estate in a place like Austin or Dallas, the property tax bill can be a shock. SmartAsset frequently ranks Florida highly because its property taxes are more moderate than Texas, making it often the superior choice for those with high-value real estate portfolios.
Furthermore, some states that lack an income tax on wages still find ways to tax other forms of wealth. For example, Washington state recently implemented a tax on high-value capital gains, which is a significant consideration for founders looking to exit their companies. You should look into the Washington Capital Gains Tax Explained (7% / 9.9%) to understand how this might affect a liquidating event. Always look at the States With No Income Tax (2026 Full List) to see the current landscape, as legislative changes can shift the "math" of a move quite quickly.
The Flat Tax Middle Ground
For those who don't want to live in the traditional no-tax hubs, the next best thing is often a flat-tax state. In these jurisdictions, every dollar you earn is taxed at the same rate, regardless of whether you make $50,000 or $5,000,000. This is a massive advantage for high earners who would otherwise be pushed into the 10% to 13% brackets in progressive states. A flat tax provides predictability and a "cap" on how much the state can take as your career trajectory continues upward.
Why Flat Taxes Benefit High Earners
States like Pennsylvania, Indiana, and Colorado have long embraced the flat tax model. If you are a high earner in Philadelphia, you are paying the same state rate as the person working the counter at a coffee shop. This lack of "success penalty" is why many wealth managers suggest these states for clients who want a traditional lifestyle in established metro areas without the predatory tax brackets of nearby states. You can explore how these systems function in our overview of How Many States Have a Flat Tax? to see if one of these environments fits your professional needs.
The shift toward flat taxes is a growing trend across the country. Several states are moving away from progressive brackets to stay competitive in the "war for talent." For instance, North Carolina has been aggressively lowering its flat rate, making it an incredibly attractive hub for banking and biotech executives. Detailed breakdowns found on SmartAsset's platform often show that as income exceeds the $250,000 mark, flat-tax states begin to vastly outperform progressive ones in terms of total tax efficiency.
Emerging Flat Tax Trends
One of the most exciting developments for high earners is the recent move by states like Georgia and Ohio to simplify their tax codes. Georgia, for instance, has moved toward a flat tax system that significantly lowers the burden on top-tier earners compared to its previous multi-bracket system. Check out the Georgia Flat Tax Rate 2026 to see how this transition has made the Atlanta metro area even more competitive for corporate relocations and high-income professionals.
Similarly, Ohio has been consolidating its brackets, effectively moving toward a flatter, more hospitable environment for business owners and high-salaried employees. These changes are often driven by a desire to stop the "brain drain" to no-tax states. For a high earner, getting in on a state that is actively cutting its rates can be a great long-term play for wealth preservation. You can see the impact of these legislative shifts in our report on State Income Tax Cuts & Changes for 2026.
Strategic Residency and the High-Earner Trap
If you are a high earner, simply "moving" isn't always enough to satisfy the tax authorities in the state you are leaving. States with high income taxes, like California and New York, are notoriously aggressive about chasing former residents for taxes, especially if they believe the move was a sham for tax purposes. If you maintain a "permanent place of abode" or spend too much time in your old state, you could end up being taxed by two states at once.
Domicile vs. Statutory Residency
Understanding the difference between where you live and where your "legal home" is can save you millions. Domicile is the place you intend to return to and consider your true, permanent home. Statutory residency, on the other hand, is often triggered simply by spending a specific number of days in a state. For many states, if you spend more than 183 days there, you are a resident for tax purposes, regardless of where your driver's license was issued.
For high earners with multiple homes, managing the calendar is a full-time job. New York and California auditors will look at everything from where your dog’s vet is located to where you keep your most prized family heirlooms. We recommend reading The 183-Day Rule for State Taxes to understand the hard limits you must follow. If you are moving from a place like Los Angeles to Las Vegas, you need to ensure you have truly cut ties, or you might find yourself still subject to the California Income Tax Brackets 2026 on your global income.
Avoiding Residency Audits
When a high earner leaves a high-tax state, it often triggers a "desk audit." The state doesn't want to lose that revenue and will look for any reason to claim you are still a resident. They might check your cell phone records to see where the majority of your calls are placed or look at your credit card swipes to see where you are buying your morning coffee. SmartAsset’s tax calculators can help you see the potential savings, but those savings only realize if you successfully navigate the residency transition.
To protect yourself, you need to build a "moving file." This includes changing your voter registration, updating your passport address, and ensuring your primary bank accounts are linked to your new home in a tax-friendly state. The stakes are incredibly high, as being found a resident of a state you thought you left can lead to massive back-tax bills and penalties. For more detail on what can tip off the authorities, see our guide on What Triggers a State Residency Audit?.
Total Tax Burden and Quality of Life
While state income tax is a massive factor, high earners must look at the State Tax Burden by State 2026 to get the full picture. A state might have zero income tax but such high property and sales taxes that the actual "savings" are much lower than anticipated. For example, Illinois has a flat tax, but its property taxes are among the highest in the nation, which can eat into the benefits for those owning luxury real estate in the Chicago suburbs.
Wealth Management and Estate Taxes
High earners aren't just thinking about their next paycheck; they are thinking about their legacy. Some states that are great for income tax are terrible for estate or inheritance taxes. If you plan to pass down significant wealth, moving to a state like Washington might be great for your annual income, but the state-level estate tax could take a huge bite out of your heirs' inheritance. Conversely, states like Florida and Tennessee have no estate or inheritance taxes, making them "double winners" for wealthy families.
This long-term perspective is why many high net worth individuals end up in the Southeast. Not only is the current Is Florida Tax Friendly for Workers? status high, but the long-term outlook for wealth transfer is equally positive. When planning your move, you should check the Most Tax-Friendly States for Retirees 2027 even if you are years away from retirement, as these laws often indicate the general fiscal philosophy of the state toward wealth.
Comparative Analysis of Top States
| State | Top Income Tax Rate | Property Tax Rank | Estate Tax? |
|---|---|---|---|
| Florida | 0% | Moderate | No |
| Texas | 0% | Very High | No |
| Nevada | 0% | Low | No |
| Tennessee | 0% | Very Low | No |
| Washington | 0% (Wages) | Moderate | Yes (High) |
| Pennsylvania | 3.07% (Flat) | High | No (But Inheritance Tax) |
This table illustrates that while all these states are "friendly" to high earners, they favor different types of wealth. A high earner with a modest home but a massive salary will thrive in Texas. A high earner who wants to build a massive family estate and eventually pass it on would likely prefer Florida or Nevada.
The Impact of Federal Policy on State Selection
The relationship between state and federal taxes changed dramatically with the implementation of the SALT (State and Local Tax) cap. Previously, high earners could deduct their state taxes from their federal return, which "cushioned" the blow of living in a high-tax state. Now, with the cap stuck at $10,000 for most (though check How the SALT Cap ($40,000) Affects State Taxes for potential 2026 updates or specific legislative quirks), you are essentially paying state taxes with after-tax dollars.
Strategic Deductions for High Earners
In response to the SALT cap, some states have created "workarounds," particularly for business owners who pay taxes through their personal returns (pass-through entities). If you are a high-earning consultant or law firm partner, some states allow you to pay the tax at the entity level, which then becomes a fully deductible business expense on your federal return. This can effectively bypass the SALT cap and save you tens of thousands of dollars.
You should always look for states that offer specialized credits or deductions that align with your lifestyle. For example, if you are a high earner who is also a heavy investor in 529 plans for your children, some states offer much more generous deductions than others. These "micro-wins" can add up over time, even in states that aren't at the top of the "zero-tax" list.
Choosing the Right Infrastructure
Finally, for the modern high earner, the "best" state is the one that offers the right balance of tax savings and professional infrastructure. A zero-tax state is no good if it doesn't have the airport connectivity, specialized legal services, or talent pool your business needs to thrive. This is why cities like Nashville, Austin, and Miami have become the dominant hubs; they offer the perfect trifecta of high growth, high lifestyle quality, and low state-level intervention.
When making your decision, remember that tax laws are not set in stone. Use a combination of SmartAsset’s real-time data and our internal guides on State Income Tax Rates 2026: All 50 States Ranked to keep a pulse on which states are trending toward more hospitality for high earners and which ones are becoming increasingly hostile to success. Protecting your wealth requires vigilance and a willingness to move when the math no longer supports your current location.
Disclaimer
This guide is provided for informational purposes only and does not constitute professional tax, legal, or financial advice. State tax laws are subject to frequent legislative changes, and individual circumstances vary significantly. Always consult with a qualified CPA or tax attorney before making residency changes or major financial decisions based on tax implications.