States That Don’t Tax 401(k) & IRA Withdrawals
It's a common worry for many nearing or in retirement: how much of your hard-earned savings will disappear into state taxes once you start taking withdrawals from your 401(k)s and IRAs? The thought of income earned over decades being taxed again can be incredibly frustrating, especially when you're trying to make your retirement nest egg last. This comprehensive guide is here to shed light on which states offer a more tax-friendly environment for your retirement distributions, helping you understand the nuances and plan your financial future with greater confidence.
Understanding Retirement Income Taxation
Before we dive into the states themselves, it's really important to get a handle on how retirement income generally gets taxed. It’s not always as straightforward as it seems, and states have wildly different approaches. Some states might be incredibly aggressive, treating every dollar of your 401(k) or IRA withdrawal like regular income, while others offer generous exemptions or simply don't have an income tax to begin with. Knowing the landscape is the first step in making informed decisions about where you might want to spend your golden years.
The Different Types of Retirement Accounts
When we talk about 401(k)s and IRAs, we're broadly referring to employer-sponsored plans and individual retirement arrangements that offer tax advantages. Traditional 401(k)s and IRAs are typically funded with pre-tax dollars, meaning your contributions reduced your taxable income in the years you made them. The money grows tax-deferred, and then, crucially, withdrawals in retirement are usually taxed as ordinary income. This is where state income taxes can really come into play.
On the flip side, you have Roth 401(k)s and Roth IRAs. These are funded with after-tax dollars, so your contributions don't give you an upfront tax deduction. However, the immense benefit here is that qualified withdrawals in retirement are entirely tax-free at the federal level, and usually at the state level too. Many states mirror federal rules for Roth accounts, meaning if it's tax-free federally, it's tax-free for the state. Our focus today, however, is primarily on the more common scenario of traditional retirement accounts where withdrawals are subject to income tax.
State vs. Federal Taxation: What's the Difference?
You might already be familiar with federal income tax rules, like those from the IRS, which dictate how your 401(k) and IRA withdrawals are treated nationwide. Generally, traditional distributions are taxable at your ordinary income tax rates once you reach age 59½ (or 70½ if you're taking Required Minimum Distributions, or RMDs, which changed to 73 in 2023, and will change to 75 in 2033 under SECURE 2.0). The crucial distinction here is that while federal rules are universal, state income tax rules are not. Each state gets to decide if and how it will tax these same distributions.
This is where things get really localized. A state could say, "We follow federal guidelines exactly," meaning if the IRS taxes it, they tax it. Or, a state could implement its own set of rules, offering deductions, exemptions, or simply choosing not to tax any form of retirement income at all. This divergence is why understanding the specific state rules is so vital for retirees. It's not enough to know your federal tax liability; you also need to know your potential state liability, which can vary wildly depending on where you reside. This complexity is why many people start researching "retirement income exclusions by state" long before they ever stop working.
The States That Completely Exempt 401(k) and IRA Withdrawals
The dream for many retirees is to live in a state where their hard-earned retirement savings, particularly those from 401(k)s and IRAs, are completely untouched by state income tax. This isn't just a fantasy; it's a reality in several parts of the country. These states fall into two main categories: those that don't have a broad state income tax to begin with, and a few others that, despite having an income tax, have specific provisions that exempt most or all retirement distributions.
States with No Income Tax
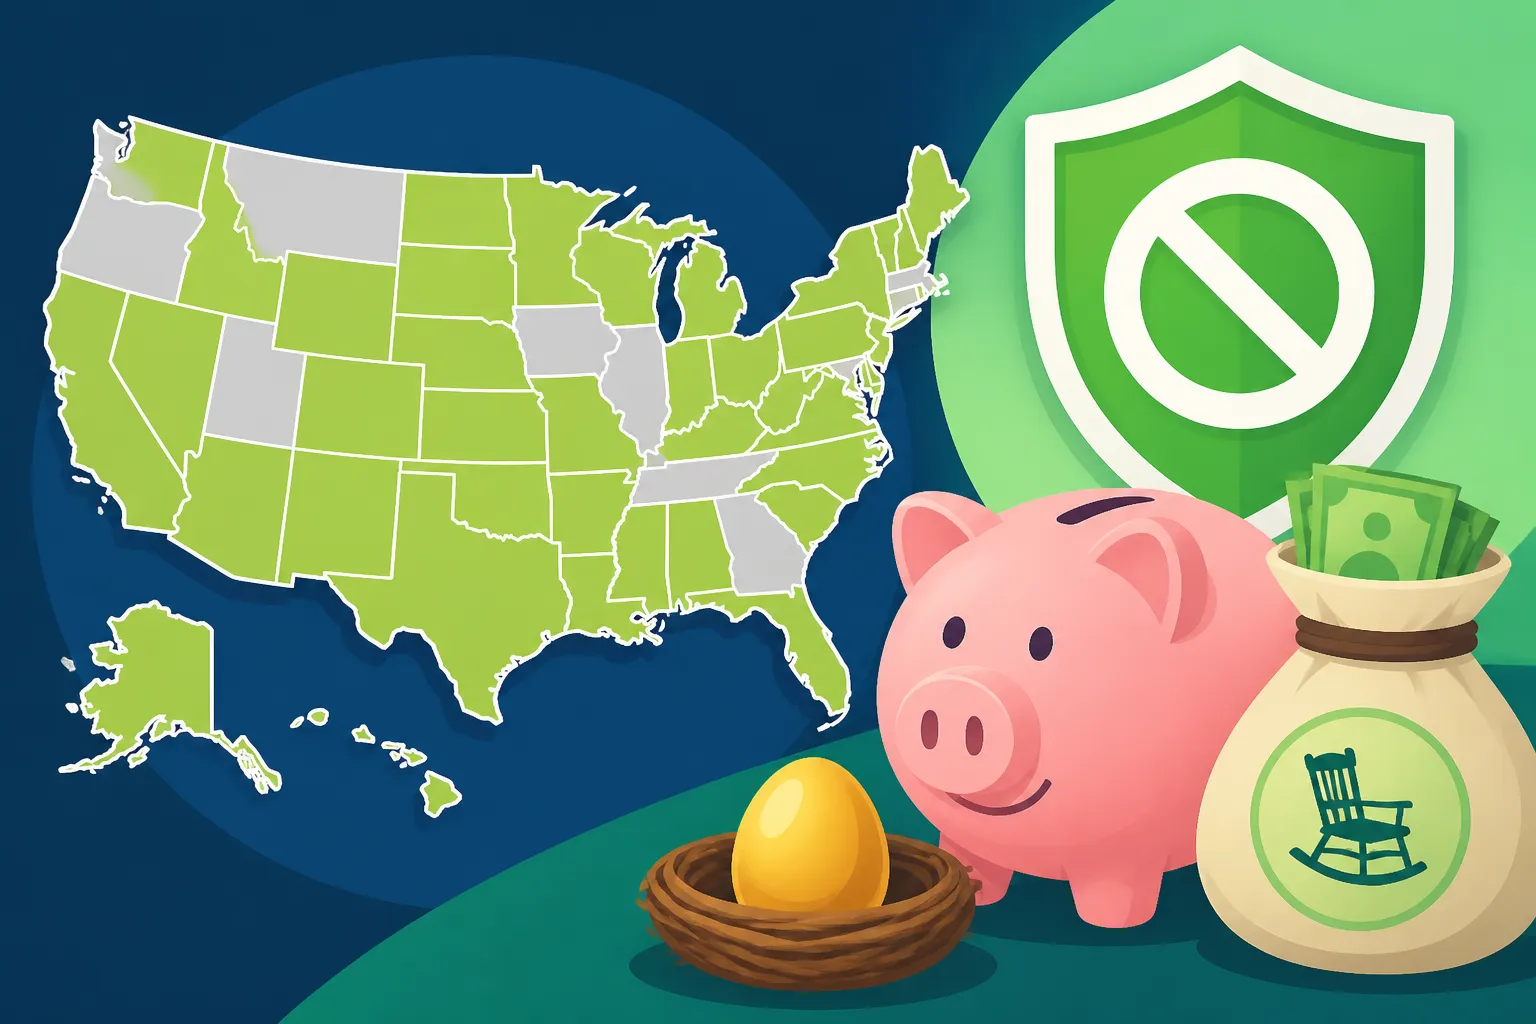
The most straightforward way to avoid state taxes on your 401(k) and IRA withdrawals is to live in a state that simply doesn't have a general state income tax. This means no tax on wages, salaries, investment income, or, pertinent to our discussion, retirement account distributions. These states are often considered the "holy grail" for tax-conscious retirees, offering a significant advantage by preserving more of your retirement income. Currently, there are nine such states, and they are:
- Alaska: Known for its vast wilderness and oil wealth, Alaska doesn't impose a state income tax. This makes it an incredibly attractive option for retirees looking to maximize their income, although the cost of living can be higher than in other areas, especially for certain goods and services.
- Florida: A perennial favorite for retirees, Florida boasts no state income tax, making it an excellent choice for those drawing from 401(k)s and IRAs. Combine this with its warm climate and abundant amenities, and it's easy to see why so many people look into How to Establish Florida Domicile for their retirement years.
- Nevada: Famous for its vibrant cities like Las Vegas, Nevada also offers a tax-free income environment. This can be particularly appealing for those who want entertainment options while keeping their retirement distributions intact.
- South Dakota: Offering wide-open spaces and a slower pace of life, South Dakota is another state that doesn't tax income, including retirement withdrawals. It provides a quiet, low-tax haven for many.
- Tennessee: While traditionally taxing interest and dividend income, Tennessee has fully phased out its Hall income tax. This means that as of 2021, Tennessee no longer taxes earned income, interest, or dividends, making it one of the states with no income tax for all practical purposes, including retirement distributions. Many find this an attractive feature when asking, for example, Does Tennessee Have State Income Tax?.
- Texas: The Lone Star State is another popular destination for retirees, in large part due to its lack of a state income tax. This means your 401(k) and IRA withdrawals are safe from state taxation here, a significant boon for anyone trying to stretch their retirement dollars further.
- Washington: While it recently introduced a capital gains tax, Washington state still does not have a general state income tax on wages or retirement distributions. For the vast majority of retirees relying on 401(k) and IRA withdrawals, this means their distributions are not subject to state income tax.
- Wyoming: With its rugged beauty and low population density, Wyoming is another no-income-tax state. It's a great option for retirees who value privacy, nature, and, of course, a tax-friendly environment for their retirement savings.
- New Hampshire: Historically known for only taxing interest and dividend income (the "Interest and Dividends Tax"), New Hampshire is now actively phasing out even this limited income tax. As of 2023, the tax rate was reduced, and it's slated for full repeal by 2027. This means for most traditional retirement income, like 401(k) and IRA withdrawals, New Hampshire is already effectively a no-income-tax state, solidifying its position among the States With No Income Tax (2026 Full List).
For anyone considering these states, it's always a good idea to consult resources like SmartAsset, which provides detailed analyses of tax burdens in different locations, helping you compare beyond just income tax.
States with Limited Income Tax that Exclude Retirement Distributions
Beyond the outright no-income-tax states, there are a few other states that, while they do have a state income tax, provide such broad exemptions or exclusions for retirement income that they effectively don't tax 401(k) and IRA withdrawals for most retirees. These states usually have provisions designed specifically to make them attractive to seniors.
- Pennsylvania: Pennsylvania is famously retirement-friendly when it comes to income taxes. It exempts most retirement income from taxation, including distributions from 401(k)s, IRAs, and private pensions, provided the taxpayer is considered a "retiree" and the distributions began after retirement. This broad exemption means that for the vast majority of retirees, their traditional retirement account withdrawals are completely untaxed by the state. This makes it a standout choice for those looking for Pension-Friendly States for Retirees.
- Illinois: Illinois is another state that does not tax distributions from 401(k) plans, IRAs, and other qualified retirement plans. While it has a flat income tax rate, this exemption for retirement income is a significant benefit for seniors. This means if you're pulling from your 401(k) or IRA, Illinois won't take a slice.
- Mississippi: Mississippi offers a complete exemption for all retirement income, including public and private pensions, annuities, 401(k)s, and IRA withdrawals, once you reach age 59½. This makes it a very attractive option for retirees looking to keep their distributions intact.
These states demonstrate that even with a state income tax, smart legislation can create a very favorable environment for retirees. It's not just about the raw tax rate; it's about what income sources are included or excluded from that tax base. For many, finding these "hidden gems" can be just as beneficial as moving to an outright no-income-tax state.
States Offering Partial Exemptions or Deductions
While a handful of states offer complete immunity for 401(k) and IRA withdrawals, many others that do tax retirement income still provide significant relief through partial exemptions, deductions, or credits. These provisions can substantially reduce your state tax burden, even if they don't eliminate it entirely. Understanding these nuances is key, as a state with a seemingly higher income tax rate might still be very retirement-friendly due to its generous exclusions.
Income Thresholds and Age-Based Exemptions
Many states offer specific exemptions or deductions for retirement income that are tied to age or income thresholds. These are designed to protect lower and middle-income retirees from bearing a heavy tax burden on their distributions. For example, some states might allow you to exclude a certain amount of your pension or retirement income if you are over a certain age, say 65 or 62.
- New Jersey: The Garden State offers a significant pension and retirement income exclusion. For 2023, married couples filing jointly could exclude up to $100,000 of retirement income if their gross income was below a certain threshold. This exclusion increases annually and applies to income from pensions, annuities, IRAs, and 401(k)s. This specific provision makes New Jersey much more retirement-friendly than its general income tax rates might suggest, particularly for those whose income falls within the exclusion limits. You can learn more about this through a guide on New Jersey Retirement Income Exclusion.
- Colorado: Colorado provides a retirement income subtraction for taxpayers aged 55 and older. The amount you can subtract depends on your age and the type of retirement income. For those 65 or older, a substantial portion of all retirement income, including 401(k) and IRA distributions, can be subtracted. For those between 55 and 64, the subtraction applies mainly to pension income. This is a great example of how a state uses age-based exemptions to soften the tax blow. More detailed information can be found in resources like Colorado Retirement Subtraction ($20k/$24k).
- Georgia: Georgia offers a generous exclusion for retirement income for individuals aged 65 or older, and a smaller exclusion for those between 62 and 64 (or those with permanent and total disability). For 2026, those 65 and older can exclude up to $65,000 per person in retirement income, which includes pensions, annuities, and IRA/401(k) distributions. This can significantly reduce the taxable portion of your withdrawals for many retirees in Georgia.
These state-specific rules are vital for retirees to research. A general tax rate doesn't tell the whole story; you need to dig into the exemptions and see how they apply to your specific situation. This is where detailed guides like How Each State Taxes Retirement Income (50-State Guide) become invaluable.
Pension and Retirement Income Deductions
Beyond outright exclusions, many states offer specific deductions that can reduce the amount of your 401(k) or IRA distributions subject to state income tax. These deductions often work similarly to how deductions reduce your taxable income at the federal level. They might be a fixed dollar amount, or they might allow you to deduct a portion of specific types of retirement income.
- Michigan: Michigan has undergone significant changes in how it taxes retirement income, specifically phasing out the taxation of pension and other retirement income. For older retirees, there are substantial exemptions for pension income, and even for 401(k) and IRA distributions, depending on birth year and the type of retirement plan. These changes are part of an effort to make Michigan more appealing to seniors and are worth investigating closely if you're considering the state for retirement. The Michigan Retirement Tax Phase-Out is a prime example of a state actively working to reduce its retirement tax burden.
- Virginia: Virginia allows for a deduction for up to $12,000 of pension and retirement income for those aged 65 and older, provided certain income limitations are met. While it doesn't exempt all 401(k) and IRA withdrawals, this deduction can significantly reduce the taxable amount for many retirees.
- Kentucky: Kentucky offers a pension income exclusion for up to $31,110 per person for 2023. This exclusion applies to income from pensions, annuities, and certain retirement accounts, including 401(k)s and IRAs. While it’s not a full exemption, it substantially reduces the taxable income for many retirees in the state.
When evaluating a state, it's not just about the rate, but also about the maximum deduction available. For instance, a state might have a 5% income tax, but if you can deduct $20,000 of your retirement income, your effective tax rate on those distributions could be much lower than it appears. This is why tools and resources from organizations like SmartAsset are so helpful, as they often compile these complex state-specific rules into digestible formats, helping you compare states more effectively.
How Other Taxes Impact Retirement Budgets
It's tempting to focus solely on income tax when planning for retirement, especially when you're thinking about 401(k) and IRA withdrawals. However, state income tax is just one piece of the puzzle. Other taxes – like property taxes, sales taxes, and even estate taxes – can significantly impact your overall financial well-being in retirement, sometimes outweighing the benefits of a low or no income tax. A truly tax-friendly state considers the full picture, not just one aspect.
The Role of Property Taxes
Property taxes are often the single largest tax burden for homeowners in retirement, especially if you've paid off your mortgage. These taxes are levied by local governments (counties, cities, school districts) and fund essential services. A state might not tax your 401(k) withdrawals, but if its property taxes are sky-high, you could end up paying more overall. For example, a state like New Hampshire has no income tax, but its property taxes are among the highest in the nation. Conversely, states like Alabama have very low property tax rates.
It's crucial to look beyond just the income tax rate. If you're planning to buy a home or stay in your current one, understanding the property tax landscape is paramount. Some states offer Property Tax Credits & Homestead Exemptions by State which can provide relief for seniors, veterans, or low-income households, so it's worth investigating those details. The actual amount you pay will depend heavily on the value of your home and your local municipality, making it a very personal calculation.
Sales Tax and Everyday Expenses
Sales taxes are another often-overlooked component of a state's tax burden. These are consumption taxes, meaning you pay them on goods and services you purchase. While they might seem minor on a single transaction, they can add up significantly over the course of a year, especially for retirees who might be more focused on leisure activities, home improvements, or simply daily necessities. States like Florida and Texas, which have no income tax, rely more heavily on sales tax and property tax to generate revenue.
Some states exempt certain necessities from sales tax, such as groceries or prescription medications, which can provide some relief for retirees on a fixed income. Others have very high sales tax rates, which can subtly erode your purchasing power. For instance, while Oregon has no state sales tax, it does have a state income tax. In contrast, California has a high income tax and a high sales tax. This interplay means that even if your 401(k) withdrawals aren't taxed, your everyday living expenses might still be significantly impacted.
Estate and Inheritance Taxes
While less common than income, property, and sales taxes, estate and inheritance taxes can also be a consideration for retirees with substantial assets. These taxes are levied on the transfer of wealth after death. The federal government imposes an estate tax, but only on very large estates. However, some states have their own estate taxes, and a few even have inheritance taxes (which are paid by the heirs, not the estate).
Currently, there are 12 states plus the District of Columbia that impose an estate tax, and six states that impose an inheritance tax. Maryland is unique in having both. For the average retiree, these taxes may not be a concern, but for those with significant wealth, moving to a state without an estate or inheritance tax could be a major factor in their financial planning and legacy. It's a critical component to consider when looking at the overall State Tax Burden by State 2026.
Factors Beyond Tax Rates for Retirees
While tax considerations, particularly how your 401(k) and IRA withdrawals are treated, are a huge piece of the retirement planning puzzle, they are certainly not the only piece. Many retirees find that other factors like the cost of living, access to healthcare, and proximity to family or desired amenities ultimately play a more significant role in their quality of life and overall satisfaction. Moving purely for tax benefits without considering these elements can lead to unforeseen frustrations.
Cost of Living Considerations
A state might boast no income tax on retirement withdrawals, but if the cost of living there is exorbitant, any tax savings could quickly be negated. Imagine moving to a state like Washington to save on income tax, only to find housing costs in Seattle or its suburbs are far higher than you anticipated. Conversely, a state with a modest income tax might have significantly lower housing, utility, and grocery costs, leading to a better overall financial outcome.
For example, while Florida has no state income tax, homeowners insurance rates have been skyrocketing in recent years, especially in coastal areas prone to hurricanes. Property taxes, even if not the highest in the nation, can still be substantial, particularly in desirable areas. A helpful way to look at this is comparing Cost of Living vs Taxes by State. It’s about finding that sweet spot where your income lasts longer not just because of lower taxes, but because your money genuinely buys more. Tools like SmartAsset's cost of living calculators can be incredibly useful in simulating what your expenses might look like in a new location, giving you a more realistic picture than just glancing at tax rates.
Access to Healthcare and Amenities
As we age, access to quality healthcare becomes increasingly important. When choosing a retirement destination, consider the availability of specialists, reputable hospitals, and the overall healthcare infrastructure. Even if a state is tax-friendly, if it lacks adequate medical facilities or if healthcare costs (even with insurance) are higher, it might not be the best fit. Think about proximity to major medical centers, the number of doctors per capita, and even the quality of elder care services if that's a potential future need.
Beyond healthcare, consider the amenities that will make your retirement enjoyable. Do you prefer a vibrant city life with cultural attractions, or a quiet rural setting close to nature? Do you want access to lifelong learning opportunities, golf courses, beaches, or hiking trails? The social and recreational aspects of retirement are just as crucial as the financial ones. A state might be great for your wallet, but if it doesn't offer the lifestyle you desire, it might not be the "best state to retire" for you.
Proximity to Family and Social Networks
This is often the most emotionally driven factor, and for good reason. For many, retirement is a time to spend more quality time with children, grandchildren, and lifelong friends. Moving across the country, even to a tax-friendly paradise, can mean sacrificing regular interactions with loved ones. The emotional cost of being far from your support network can sometimes outweigh any financial savings.
It's a personal decision, but it's one that deserves careful consideration. Could your family visit easily? Are there good transportation links? Could they potentially move closer to you in the future? Sometimes, staying in a state with slightly higher taxes, but where you have a strong social fabric and close family ties, can contribute more to overall happiness and well-being than maximizing every last dollar of your 401(k) withdrawal. Ultimately, choosing among the Most Tax-Friendly States for Retirees 2027 involves balancing financial benefits with personal preferences and familial considerations.
Navigating a Move for Tax Benefits
So, you've crunched the numbers, considered the lifestyle, and decided that moving to a state with more favorable tax treatment for your 401(k) and IRA withdrawals is the right move for you. That's fantastic! But simply packing your bags and leaving isn't enough to magically change your tax residency. States are very keen on determining who their residents are, especially when it comes to collecting taxes. You'll need to take concrete steps to establish domicile in your new state and potentially sever ties with your old one to truly reap those tax benefits.
Establishing Domicile for Tax Purposes
"Domicile" is a fancy legal term, but it’s critical for tax purposes. It refers to your true, fixed, and permanent home – the place to which you intend to return whenever you are absent. You can only have one domicile at a time, and it's where you generally pay state income taxes (if applicable). Simply owning property or spending some time in a new state isn't enough; you need to demonstrate a clear intent to make that state your permanent home. This process is often detailed in guides like How to Change Your State Residency for Taxes.
Here are some key actions you should take to establish domicile in your new, tax-friendly state:
- Register to vote: Update your voter registration to your new state and county. This is a clear indicator of intent.
- Obtain a new driver's license: Get a driver's license from your new state and surrender your old one.
- Register your vehicles: Transfer your vehicle registrations and titles to your new state.
- Change mailing address: Update your mailing address with the post office, banks, investment firms, and all other important contacts.
- Open bank accounts: Establish new bank accounts in your new state and close old ones.
- Join local organizations: Become involved in local clubs, religious organizations, or community groups.
- File a declaration of domicile: Some states, like Florida, even allow you to file a "Declaration of Domicile" with the county clerk, which is a powerful legal statement of your intent.
- Spend more than half the year there: While not the sole factor for domicile, physically spending more than 183 days a year in your new state can be important for proving statutory residency, especially if your old state has an "183-day rule for state taxes."
Remember, it's not about doing just one of these things; it's about building a consistent pattern of behavior that clearly shows your commitment to your new state. The more ties you create in your new state and sever from your old one, the stronger your case for a change in domicile.
Potential Pitfalls of Moving for Taxes
While the allure of lower taxes on your 401(k) and IRA withdrawals is strong, there are some potential pitfalls to be aware of when relocating primarily for tax benefits. States with high income taxes are increasingly aggressive in auditing former residents who claim to have moved, especially if they maintain significant ties to their old state. This is particularly true for states like California and New York, known for their rigorous residency audits. They want to ensure you've truly left before they stop collecting their share. Knowing the difference between Domicile vs Statutory Residency is critical here.
One common trap is maintaining a "permanent place of abode" in your old state. If you keep a house or apartment there, and continue to use it, your old state might argue that you still have significant residential ties, regardless of how much time you spend in your new state. This can lead to dual residency claims and the dreaded "double taxation" scenario where both states try to tax your income, including your retirement distributions. This is exactly why a proper guide on How to Avoid Double Taxation Between States is so valuable.
Before making a move, especially from a high-tax state, it's highly advisable to consult with a tax professional who specializes in multi-state taxation. They can help you understand the specific residency rules of both your old and new states, guide you through the process of establishing domicile, and help you sever ties effectively to minimize the risk of a costly audit. Remember, the goal is to save on taxes, not to invite a headache from the state tax department!
Comparing States for Retirement Income Tax
To help you visualize some of the differences we've discussed, here's a table summarizing how various states treat 401(k) and IRA withdrawals, along with notes on other key retirement income taxes. This isn't an exhaustive list but provides a good overview for comparison.
| State | State Income Tax? | Taxes 401(k)/IRA Withdrawals? | Taxes Pensions? | Taxes Social Security? | Key Notes |
|---|---|---|---|---|---|
| Alaska | No | No | No | No | No state income, sales, or inheritance tax. High cost of living in some areas. |
| Florida | No | No | No | No | No state income tax. High property taxes and rising homeowners insurance. |
| Illinois | Yes (Flat) | No (Exempt) | No (Exempt) | No | Flat income tax, but all qualified retirement income (pensions, 401ks, IRAs) is exempt. |
| Nevada | No | No | No | No | No state income tax. Higher sales tax in some areas. |
| New Hampshire | Limited (Phasing Out) | Effectively No | No | No | No tax on earned income. Interest & Dividends tax phasing out by 2027. High property taxes. |
| New Jersey | Yes (Progressive) | Often Exempt (High Exclusion) | Often Exempt (High Exclusion) | No | Significant pension/retirement income exclusion (up to $100k for joint filers in 2023, increasing annually) for those under certain income thresholds. |
| Pennsylvania | Yes (Flat) | No (Exempt) | No (Exempt) | No | Retirement-friendly; most qualified retirement income (pensions, 401ks, IRAs) is exempt for retirees. |
| South Dakota | No | No | No | No | No state income tax. Low cost of living. |
| Tennessee | No | No | No | No | Hall income tax on interest and dividends fully repealed as of 2021, making it a no-income-tax state. |
| Texas | No | No | No | No | No state income tax. High property taxes. |
| Washington | No | No | No | No | No state income tax (capital gains tax recently enacted, but not on 401k/IRA withdrawals). Higher sales tax. |
| Wyoming | No | No | No | No | No state income tax. Lower population density. |
| Colorado | Yes (Flat) | Partial Exemption | Partial Exemption | No | Significant retirement income subtraction for those 55 and older (higher for 65+). |
| Georgia | Yes (Flat) | Partial Exemption | Partial Exemption | No | Up to $65,000 per person exclusion for retirement income for those 65+ (2026), including 401k/IRA distributions. |
| Mississippi | Yes (Progressive) | No (Exempt) | No (Exempt) | No | All qualified retirement income (pensions, 401ks, IRAs) is exempt once you reach 59½. |
| Michigan | Yes (Flat) | Partial Exemption/Phase-Out | Partial Exemption/Phase-Out | No | Phasing out tax on pension and other retirement income, with significant exemptions depending on age and plan type. |
| Virginia | Yes (Progressive) | Partial Exemption | Partial Exemption | No | Deduction of up to $12,000 of pension/retirement income for those 65+ (income limits apply). |
This table provides a general overview and tax laws can change. Always verify current laws with a qualified tax professional or state tax authority.
This table highlights just how diverse the state tax landscape is. As you can see, states like Illinois, Pennsylvania, and Mississippi, despite having an income tax, are exceptionally generous when it comes to 401(k) and IRA withdrawals, effectively treating them the same as states with no income tax at all. Meanwhile, other states like New Jersey, Colorado, Georgia, Michigan, and Virginia offer significant partial exemptions or deductions that can greatly reduce your tax burden. For a deeper dive into how states tax pensions, you can check out guides on States That Don't Tax Pensions (2026), or to understand Social Security taxation, read about States That Don't Tax Social Security (2026). The goal here isn't to pick a "best" state, but to give you the tools to find the best state for your retirement and financial situation.
Final Thoughts on Your Retirement Tax Journey
Navigating the complexities of state income tax, especially concerning your hard-earned 401(k) and IRA withdrawals, can feel like a daunting task. It’s a significant decision, one that can impact how far your retirement savings stretch and, ultimately, your peace of mind. We've explored the states that offer the most relief, from those with no income tax whatsoever to those that provide generous exemptions and deductions for retirement distributions. We've also touched on the broader tax picture, reminding you that property, sales, and other taxes are equally important to consider, alongside critical lifestyle factors.
Remember, the "best" state for retirement isn't a universal answer; it's a deeply personal one. What works for one retiree might not be suitable for another. It's about finding that sweet spot where your financial goals align with your desired lifestyle, access to healthcare, and proximity to loved ones. Whether you're planning a move or simply trying to optimize your current situation, understanding these tax nuances is crucial. Tools from financial experts like SmartAsset, coupled with professional advice, can illuminate your path. Taking proactive steps to establish domicile if you move, and being aware of potential pitfalls, will safeguard your financial future. Your retirement should be a time of enjoyment and security, not constant tax anxiety. With careful planning and a clear understanding of the rules, you can ensure your 401(k) and IRA withdrawals work as hard for you in retirement as you did to save them. If you're looking for more ways to optimize your finances, remember to explore articles like How to Minimize State Taxes in Retirement to round out your strategy.
Disclaimer
Please note that tax laws are complex and subject to change frequently. The information provided in this guide is for informational purposes only and does not constitute tax, financial, or legal advice. Always consult with a qualified tax professional, financial advisor, or attorney to discuss your specific situation and ensure compliance with all applicable laws and regulations.