Which States Have No Tax on Pensions?
You worked hard for decades, setting aside income and earning a pension that was supposed to offer complete peace of mind in your golden years. But when you finally start drawing those monthly checks, watching a chunk of your fixed income disappear into state tax coffers can feel like a punch in the gut. Fortunately, your geographic address plays a massive role in how much of that hard-earned money stays in your pocket. This detailed guide breaks down which states refrain from taxing pension income, how partial pension exemptions work, and how you can strategically protect your retirement cash flow.
States With No Individual Income Tax At All
The simplest way to ensure your pension remains completely untouched by state tax authorities is to spend your retirement years in a state that does not levy an individual income tax. In these destinations, state agencies simply do not collect income tax on earned wages, investment returns, private corporate pensions, or government retirement distributions. For retirees relying heavily on a pension to cover daily living expenses, eliminating state-level tax filings altogether offers incredible financial predictability.
The Zero Tax Haven States
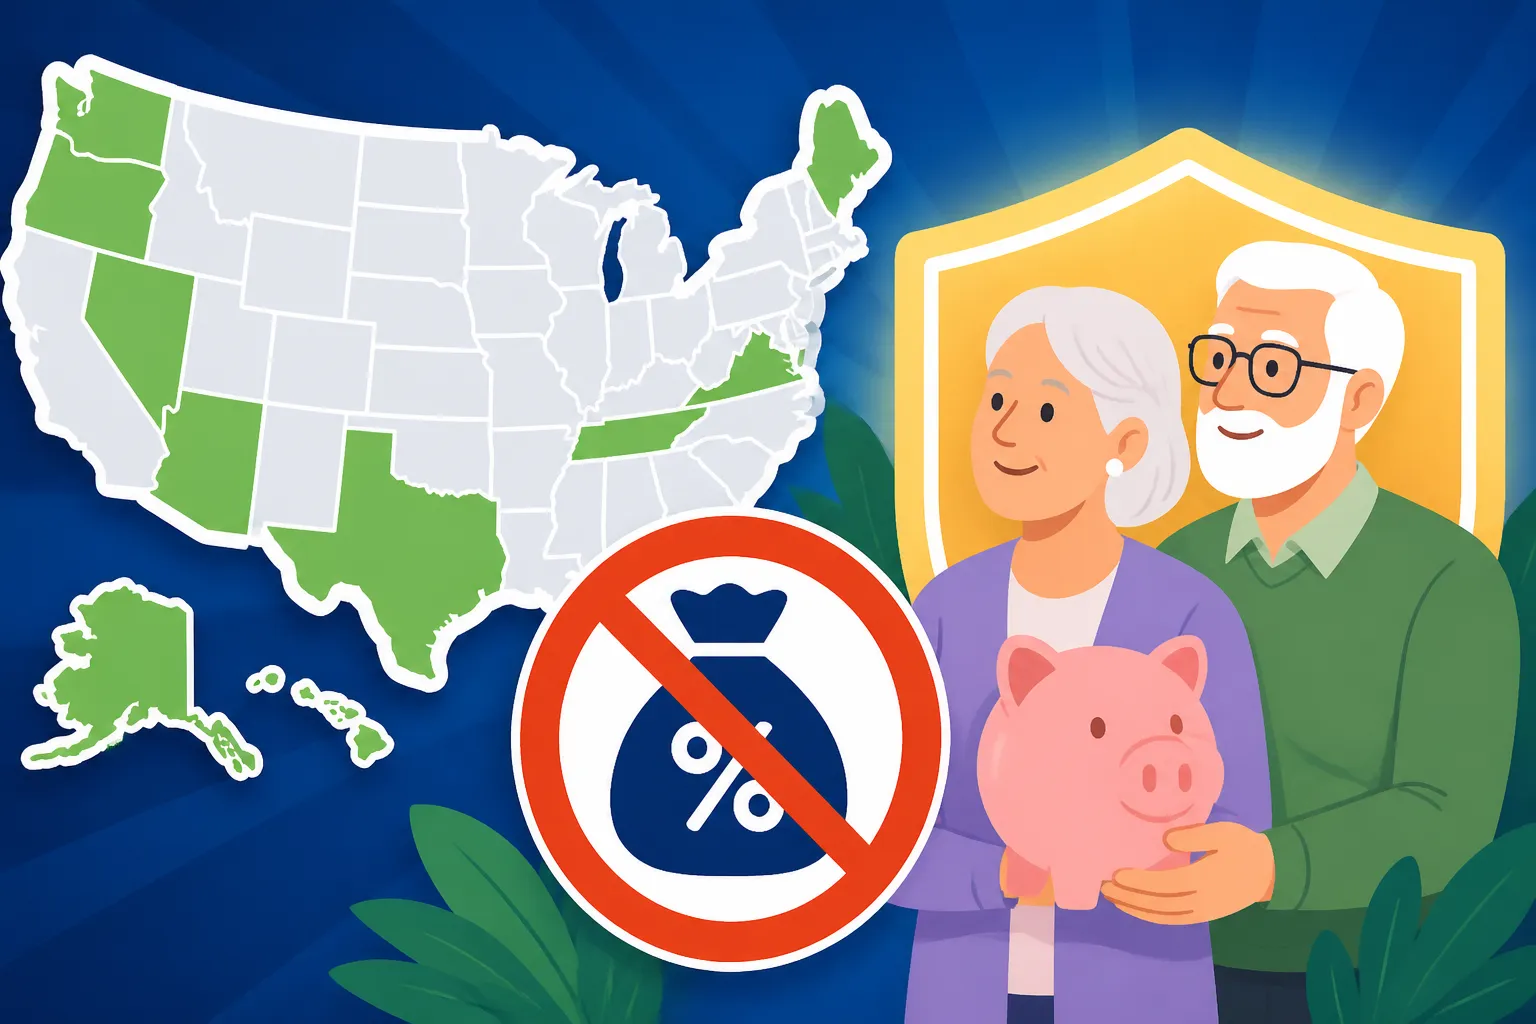
There are several states across the country that do not collect broad-based personal income taxes from their residents. Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming fall into this category. Additionally, New Hampshire does not tax earned wages or pension distributions, restricting its limited tax regime strictly to specific types of interest and dividend income before phasing out those collections entirely.
If you decide to settle in one of these states, your pension checks are delivered without a single cent deducted for state-income tax purposes. Whether you are receiving a municipal police pension, a state civil service annuity, or a corporate retirement payout from decades in the private sector, these states view your distribution as completely tax-exempt. You can read more about how these tax jurisdictions compare in our guide to States With No Income Tax (2026 Full List).
The Real Financial Picture Beyond Income Taxes
While living in a state without a personal income tax sounds like an automatic win for your retirement budget, it is critical to look at the total state tax structure before packing your moving boxes. State governments still require revenue to maintain public infrastructure, fund emergency services, and support local public schools. When a state gives up individual income taxes, it typically relies far more heavily on sales taxes, municipal property taxes, or corporate excise fees to balance its budget.
For instance, relocating to a state with zero income tax might leave you facing significantly higher real estate property tax bills on your home or steep local sales taxes on everyday purchases. A state might leave your monthly pension entirely alone, yet take a noticeable bite out of your spending power every time you visit the grocery store or pay your annual property tax bill. Before uprooting your lifestyle, using a comprehensive planning platform like SmartAsset can help you visualize how your specific pension payout changes under different state tax formulas. Comparing overall tax structures helps ensure that saving on pension taxes does not accidentally result in higher overall living expenses elsewhere.
States That Don’t Tax Pensions Despite Having An Income Tax
You do not necessarily have to move to a zero-income-tax state to keep your pension safe from state taxes. Several states enforce a standard personal income tax on traditional wages and business earnings, yet explicitly exempt public, private, or military pension distributions from their taxable income base. This creates a fantastic middle ground for retirees who want access to specific regional amenities or lower property taxes while keeping their pension income fully protected.
| State Category | Pension Tax Treatment | Example States | Key Considerations for Retirees |
|---|---|---|---|
| :— | :— | :— | :— |
| Zero-Income-Tax States | All pensions 100% exempt from state income tax | Florida, Texas, Nevada, Tennessee | May feature higher property or sales taxes to fund public services. |
| Full Pension Exemption States | Broad income tax exists, but qualifying pensions are exempt | Pennsylvania, Illinois, Mississippi, Iowa | Specific rules apply regarding qualified retirement accounts and age. |
| Partial / Threshold Exemption States | Pensions exempt up to specific dollar limits or age brackets | Georgia, Colorado, Michigan, South Carolina | Income caps, adjusted gross income limits, or age limits dictate savings. |
| Fully Taxed Pension States | Pensions taxed as standard income with minimal breaks | California, Vermont, Minnesota, Connecticut | High top marginal rates can significantly diminish net monthly checks. |
States Exempting Public and Private Pensions
A select group of states maintain a personal income tax system but offer broad exemptions for retirement distributions. States like Pennsylvania, Illinois, Mississippi, and Iowa stand out for their generous treatment of retiree benefits. In Pennsylvania and Mississippi, for example, payments received from an eligible corporate or government pension plan are entirely exempt from state income tax once you reach the qualifying retirement age.
Illinois similarly exempts qualified employee benefit plans, corporate pensions, and government annuities from its flat income tax framework. Iowa has also overhauled its tax treatment of retirement assets, exempting most qualified pension income, IRAs, and 401(k) distributions for residents who are sixty-five years of age or older. For a deeper breakdown of how these specific policies operate nationwide, explore our resource on States That Don’t Tax Pensions (2027).
States With Specific Public Pension Exemptions
Some states choose not to exempt private corporate pensions, but offer robust, targeted protections for public-sector retirees. If you spent your career in public service—working as a public school teacher, firefighter, police officer, or civil servant—you might find that your home state treats your pension far better than a private workplace retirement account.
States like Alabama and Hawaii, for instance, tax private pension benefits and traditional IRA withdrawals, but provide comprehensive tax exemptions for defined benefit public pensions. Similarly, many jurisdictions extend full tax exemptions exclusively to military retirement pay. If you served in the armed forces, reviewing our specialized overview on States That Don’t Tax Military Retirement will help you identify destinations that honor your service by leaving your military pension completely untaxed. You can also explore how different municipal and state systems compare in our report on Government & Teacher Pension Taxation by State.
How States Define Eligible Pension Plans
To qualify for state-level pension tax exemptions, your retirement income must meet specific definitions established by state departments of revenue. In most jurisdictions, a protected pension must originate from a qualified, employer-sponsored defined benefit plan, such as those governed by federal Section 401(a) rules or traditional government annuities.
Problems can arise when distributions come from non-qualified plans, executive deferred compensation programs, or early retirement buyout packages. If you receive an early pension payout before reaching a state’s defined retirement age, the state may treat those funds as ordinary wage income rather than exempt pension distributions. Always double-check your state revenue department’s exact definition of a qualified plan to avoid unexpected tax assessments on your monthly check.
Income Exclusions and Partial Pension Tax Exemptions
Not every state offers an all-or-nothing approach to pension taxes. A large portion of the country uses a nuanced system featuring income exclusions, age-based subtraction limits, or means-tested exemptions. In these states, you might pay zero tax on your pension up to a certain dollar threshold, while any income exceeding that cap is taxed at standard state marginal rates.
Age-Based Deduction Caps and Subtraction Rules
Age-based exclusions are incredibly common across the country. States frequently allow older residents to deduct a generous dollar amount of retirement income from their state tax return each year. As long as your total annual pension stays below that statutory limit, your effective state tax rate on that pension remains zero.
Georgia, for example, provides a very flexible exclusion program for seniors. Residents who meet the state’s age requirements can exclude up to a substantial amount of retirement income per person, which often covers an entire pension plus additional investment withdrawals. Details on these mechanics are covered in our dedicated guide to the Georgia $65,000 Retirement Exclusion (2026). Colorado offers a similar mechanism through its retirement subtraction rules, allowing older individuals to deduct a fixed block of pension or annuity income each year. You can learn how those specific limits work in our breakdown of the Colorado Retirement Subtraction ($20k/$24k).
Means-Testing and Adjusted Gross Income Thresholds
Other states implement income-sensitive policies to protect modest pensions while taxing higher-income retirees. Under a means-tested framework, your eligibility for a pension exemption depends entirely on your overall federal Adjusted Gross Income (AGI).
If your total income—combining your pension, Social Security, interest, and part-time earnings—remains under the state-mandated threshold, your pension remains tax-free. However, if your AGI crosses that line, the state may phase out your exemption or tax your pension income entirely. This policy structure requires careful distribution planning. If you draw down extra money from a traditional IRA in a single year, you could accidentally push your AGI past the threshold, triggering state income taxes on a pension that would have otherwise been exempt. You can examine various state-level deduction rules in our index on Retirement Income Exclusions by State.
Key Tax Planning Strategies for Pension Recipients Moving States
If you are considering moving to a state with no tax on pensions, executing your relocation properly is essential. State tax agencies in high-tax jurisdictions monitor departing residents closely, and failing to cleanly sever your tax ties could result in your former home state attempting to tax your pension long after you have unpacked your bags in a new town.
Domicile vs. Statutory Residency Challenges
A common misconception among retirees is that simply buying a condo or obtaining a driver’s license in a tax-friendly state instantly shields their pension from taxes. In reality, state tax authorities rely on complex legal tests surrounding domicile and statutory residency to determine where you owe taxes. Your domicile is your primary, permanent home—the place you intend to return to whenever you are away.
If you move away from a state that heavily taxes pensions, that state’s department of revenue may audit your transition to verify whether you actually abandoned your old domicile. They will look at real-world evidence: where you spend the majority of your calendar days, where your primary doctor and dentist practice, where your pets receive veterinary care, and where you hold active bank accounts. If you spend time in multiple states throughout the year, understanding State Tax Residency Rules Explained is crucial to ensure your pension is only audited by your intended tax-friendly destination.
Calculating Your Full Retirement Tax Burden
Protecting your pension from state income taxes is a major milestone, but it should never be the sole metric driving your retirement location decisions. A truly comprehensive financial strategy evaluates your entire household expenditure profile.
To get an accurate forecast of your post-retirement lifestyle, take time to model your prospective budget. Using a lifestyle research platform like SmartAsset allows you to plug in your pension amount, anticipated IRA withdrawals, home value, and estimated consumer spending to compare your overall cost of living across multiple states. You might discover that a state with a mild partial pension exemption and low property taxes actually leaves you with more disposable cash than a zero-income-tax state with extremely high cost-of-living metrics. If you choose to move, following the steps outlined in How to Change Your State Residency for Taxes will help ensure your transition is legally sound and tax-efficient.
Before taking action, review our rank-ordered guide on the Most Tax-Friendly States for Retirees 2027 to see how your preferred relocation targets compare across income taxes, property assessments, sales tax rates, and local fees. Evaluating the complete picture allows you to make an informed, confident move that protects your pension and secures your retirement lifestyle.
By taking advantage of online tools like SmartAsset to run real-world scenarios, you can build a clear roadmap of your prospective net take-home pay. Knowing exactly how each state treats your pension puts you in total control of your financial future, letting you enjoy your retirement years with clarity and confidence.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.