How Social Security Is Taxed in Retirement
Let's face it, one of the biggest anxieties many of us carry into retirement is wondering how our hard-earned Social Security benefits are going to be impacted by taxes. It feels unfair, doesn't it, to work all those years, contribute to the system, and then potentially have a chunk of your retirement income eaten away by Uncle Sam and even your state? You're not alone in feeling this way. This comprehensive guide is here to demystify the federal and state rules surrounding Social Security taxation in retirement, helping you understand what to expect and how to plan.
Understanding Federal Taxation of Social Security Benefits
It's a common misconception that Social Security benefits are entirely tax-free. While that would be a lovely thought, the reality is that for many retirees, a portion of their benefits can be subject to federal income tax. This isn't a new phenomenon; these rules have been in place for decades, primarily designed to ensure the Social Security trust fund remains solvent. But understanding how it works is key to managing your retirement finances.
The Provisional Income Calculation
The first step in determining if your Social Security benefits are taxable at the federal level involves a calculation known as "provisional income." This isn't just your Social Security check; it's a mix of different income sources. The IRS uses this figure to decide if you hit certain thresholds that trigger taxation. It’s essentially a measure of your total income for the year, including some non-taxable elements, which can feel a bit counterintuitive.
To calculate your provisional income, you need to add up a few things:
- Your modified adjusted gross income (MAGI): This is generally your adjusted gross income (AGI) from your tax return, plus any tax-exempt interest (like from municipal bonds) and certain other deductions that are usually allowed. It's important to look at line 2a of Form 1040 for tax-exempt interest, as this is often overlooked but can push you over the edge.
- 50% of your Social Security benefits: Yes, you read that right. Even if your benefits aren't ultimately taxed, half of them are initially included in this provisional income calculation. This is where many people get tripped up, thinking their Social Security is "tax-free" when, in fact, it's half-counted towards a threshold.
So, the formula is: Adjusted Gross Income + Tax-Exempt Interest + Other Exclusions + 50% of Social Security Benefits = Provisional Income. It's a bit of a mouthful, and it can certainly make you scratch your head trying to figure out if you’re going to owe.
When 50% or 85% of Benefits Are Included
Once you've calculated your provisional income, the IRS looks at specific thresholds to determine how much of your Social Security benefits will be subject to federal income tax. There are two main thresholds, and exceeding them triggers either 50% or 85% of your benefits being included as taxable income.
Let’s break down those federal thresholds:
- For single filers:
- If your provisional income is between $25,000 and $34,000, up to 50% of your Social Security benefits may be taxable.
- If your provisional income is more than $34,000, up to 85% of your Social Security benefits may be taxable.
- For those filing jointly (married filing jointly):
- If your provisional income is between $32,000 and $44,000, up to 50% of your Social Security benefits may be taxable.
- If your provisional income is more than $44,000, up to 85% of your Social Security benefits may be taxable.
- For married individuals filing separately: If you live with your spouse at any time during the tax year and file separately, up to 85% of your Social Security benefits may be taxable, regardless of your income. This is a big one to watch out for, as filing separately can have significant tax implications.
It's crucial to understand that "up to 50%" or "up to 85%" doesn't mean the entire amount is taxed at your marginal rate. It means that portion of your benefits is added to your other taxable income, and then your regular income tax rates apply to that total. This is why many financial advisors stress the importance of understanding your entire income picture, not just your Social Security checks, when planning for retirement. For a deeper dive into how your overall income impacts your tax bill, you might find our guide on What Income Is Taxable for Retirees by State? helpful.
State-Level Taxation of Social Security Benefits
Beyond federal taxes, one of the biggest wildcards for retirees is how their state will treat their Social Security benefits. This is where things can get truly complicated, as each state has its own set of rules, exemptions, and definitions. What might be completely tax-free in one state could be partially or even mostly taxed in another. This variability is a huge consideration for anyone thinking about where to spend their golden years, especially if you're considering a move.
Categorizing States Based on Social Security Taxation
When we talk about state taxes on Social Security, we can generally categorize states into three buckets:
- States that do not tax Social Security benefits at all: These are often called "tax-friendly" states for retirees. They simply don't have a mechanism to tax these benefits, regardless of your income level. This is a huge draw for many, as it removes one layer of tax complexity and potential liability.
- States that partially tax Social Security benefits: These states often offer significant exemptions or deductions based on age, income level, or other factors. For example, some might exempt benefits up to a certain income threshold, or only tax them if your income exceeds a certain amount, similar to the federal provisional income rules but with different figures.
- States that tax Social Security benefits to some extent, often mirroring federal rules: These are the states that essentially adopt the federal framework, or a similar one, for taxing Social Security. This means if your benefits are federally taxable, they'll likely be state taxable too, though there might be slight differences in thresholds or calculation methods.
Understanding which category your current state, or a potential future state, falls into is absolutely essential for retirement planning. Relying on outdated information or assumptions could lead to some unpleasant surprises come tax season. Many financial planning resources, such as SmartAsset, provide tools and guides to help retirees navigate these state-specific nuances, offering insights into How Is Social Security Taxed at the State Level? or other tax implications.
The Nuances of State Rules and Exemptions
Even within these categories, the devil is often in the details. A state that "partially" taxes benefits might have a very generous exemption that means most retirees won't actually pay anything, while another might have a lower threshold that ensnares more people. Some states might have age-based exemptions, where individuals over 65, for example, can exclude more of their income. Others might offer a general pension exclusion that includes Social Security benefits.
For instance, a state might say "we tax Social Security benefits" but then offer a significant income exclusion for all types of retirement income, effectively making it tax-free for a large portion of the population. This is why it’s never enough to just see a blanket statement. You need to dig into the specifics of that state's tax code, looking at the exact provisional income thresholds, age exemptions, and any other credits or deductions available to retirees. These details can drastically change your personal tax liability and make a significant difference in your retirement budget. This level of detail is critical when looking into Most Tax-Friendly States for Retirees 2027 to make an informed decision.
States That Don't Tax Social Security
If you're dreaming of a retirement where your Social Security check remains untouched by state income taxes, you'll be happy to know that many states offer this benefit. This can be a huge financial advantage, especially for those on fixed incomes or those with higher provisional incomes that would trigger federal taxation. The peace of mind alone, knowing that your state won't be taking a slice of your Social Security, can be invaluable.
The Growing List of No-Tax States
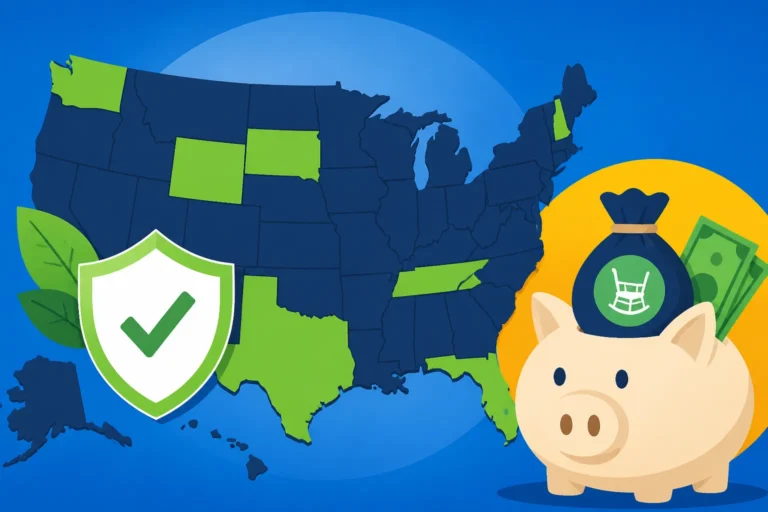
The good news is that the list of states that don't tax Social Security benefits is quite extensive and has even grown in recent years as some states have moved to repeal or phase out these taxes. Currently, the majority of U.S. states do not tax Social Security benefits. This includes the nine states that don't have a state income tax at all, naturally meaning they won't tax Social Security either. Those states are Alaska, Florida, Nevada, New Hampshire (only taxes interest and dividends, not earned income or Social Security), South Dakota, Tennessee, Texas, Washington, and Wyoming.
Beyond these states, many others that do have a state income tax choose to specifically exempt Social Security benefits from taxation. This creates a large group of tax-friendly states for retirees. For a full breakdown of these states, you can check out our detailed guide on States That Don't Tax Social Security (2026). This list is a fantastic starting point for anyone evaluating potential retirement destinations or simply trying to understand their current state's tax landscape.
What Else to Consider in No-Tax States
While a state not taxing Social Security is a big plus, it's really just one piece of the puzzle. It's easy to get fixated on this one tax advantage and overlook other significant costs that could impact your retirement budget. A state might not tax your Social Security, but it could have high property taxes, a hefty sales tax, or other fees that offset the benefit.
For example, while Florida famously doesn't have an income tax (and therefore no Social Security tax), property taxes in some areas can be substantial, and sales tax is a consistent part of daily spending. Similarly, Washington State, another no-income-tax haven, has a capital gains tax and relatively high sales taxes. When comparing states, it’s always wise to look at the overall tax burden, including property taxes, sales taxes, and how other forms of retirement income (like pensions or 401(k) withdrawals) are treated. Resources like SmartAsset often provide a "tax-friendliness" score for retirees that considers all these factors, helping you get a more holistic view. You might also want to explore our article on How Each State Taxes Retirement Income (50-State Guide) for a broader perspective.
The 8 States That Still Tax Social Security
While the trend leans towards states repealing or phasing out taxes on Social Security, there are still a handful of states where retirees need to be mindful of this potential tax. These states often have specific income thresholds or other criteria that determine if and how much of your Social Security benefits will be taxed. It's not a blanket tax for everyone in these states, but rather a targeted approach that often mirrors the federal provisional income rules.
Identifying the States and Their Specific Rules
As of recent changes and phase-outs, there are generally eight states that still tax Social Security benefits to some degree. These are:
- Colorado: Offers a generous income exclusion for all types of retirement income, including Social Security, for those aged 65 and older. The exclusion amounts vary based on age, meaning many retirees will not pay state tax on their Social Security.
- Connecticut: Provides a significant exemption for Social Security benefits, especially for taxpayers whose adjusted gross income falls below certain thresholds. For example, for 2026, the exemption thresholds are quite high, so only higher-income retirees would likely see their benefits taxed.
- Kansas: Historically taxed Social Security benefits, but only for those with higher adjusted gross incomes. However, it's worth noting that Kansas, along with Missouri and Nebraska, has recently repealed its Social Security tax for most residents, particularly for those below specific income thresholds, making it more tax-friendly for many.
- Minnesota: Taxes Social Security benefits based on a calculation similar to the federal provisional income method, though with its own unique thresholds and subtractions that can reduce the taxable amount.
- Montana: Includes Social Security benefits as part of adjusted gross income, but allows for a deduction that can reduce or eliminate the taxable portion for many retirees, especially those with lower incomes.
- New Mexico: Allows for a deduction for Social Security income, meaning only a portion, or none, might be taxed depending on your overall income and other deductions.
- Rhode Island: Exempts Social Security benefits for taxpayers whose federal AGI is below specific income thresholds. For those above the thresholds, benefits are taxable.
- Utah: Offers a retirement tax credit that can offset taxes on Social Security and other retirement income, effectively making Social Security tax-free for many.
It’s clear that even among these eight, there’s a wide range of approaches. What constitutes "taxable" in one state might be fully exempt in another due to specific credits or deductions. For the most up-to-date information on these states, you can refer to our detailed guide on The 8 States That Still Tax Social Security.
Recent Changes and Phase-Outs
The landscape of state taxation on Social Security is not static; it's constantly evolving. In recent years, we've seen a clear trend towards states reducing or eliminating these taxes, often in an effort to attract retirees and boost their economies. For instance, West Virginia has been phasing out its tax on Social Security benefits, and states like Nebraska and Missouri have made significant strides in repealing their taxes for many residents, often tied to income levels.
These changes highlight the importance of staying informed and not relying on outdated information, especially if you're close to retirement or considering a move. What might have been a tax-unfriendly state a few years ago could be much more favorable today. This dynamic environment means that revisiting your financial plan and understanding the current tax code is paramount. Consulting with a financial advisor or utilizing online tools from reputable sources like SmartAsset can help you stay current with these changes and assess their impact on your retirement income. Understanding these nuances is especially important if you are trying to minimize state taxes or want to ensure your RMDs are handled efficiently.
Strategies to Minimize Taxes on Social Security
Navigating the tax landscape for Social Security benefits can feel like a maze, but there are proactive steps you can take to potentially reduce the amount of your benefits subject to federal and, in some cases, state income tax. The key often lies in controlling your overall provisional income and making smart decisions about when and how you draw from other retirement accounts.
Managing Your Other Retirement Income Streams
Since federal (and some state) taxation of Social Security benefits is tied directly to your provisional income, one of the most effective strategies is to manage your other income streams. This primarily involves being strategic about withdrawals from your pre-tax retirement accounts, like traditional IRAs and 401(k)s, and thinking about capital gains from investments.
- Strategic IRA/401(k) Withdrawals: If you can defer taking large distributions from these accounts until later in retirement, or spread them out more evenly, you might be able to keep your provisional income below the federal taxation thresholds. This is especially relevant before you reach the age of 73 (or 75 for some individuals after 2033), when Required Minimum Distributions (RMDs) kick in. RMDs can significantly increase your taxable income and, by extension, your provisional income, pushing more of your Social Security benefits into the taxable realm. Our article on RMDs and State Taxes provides more detail on this.
- Tax-Efficient Investment Strategies: Be mindful of how your investments generate income. Tax-exempt municipal bonds, for example, can be a great way to generate income that doesn't count towards your AGI, although a portion of the interest does factor into provisional income. Long-term capital gains can also be managed through tax-loss harvesting or by carefully timing sales to avoid pushing your income over a threshold.
- Delaying Social Security: While not directly about reducing taxes on benefits, delaying claiming Social Security can increase your monthly benefit amount. If you have other income streams to cover expenses in the early years of retirement, delaying Social Security until age 70 can lead to a significantly larger benefit, which could make the eventual tax bite feel less impactful, even if a portion is taxed.
Leveraging Roth Conversions and Tax Planning
Another powerful strategy to reduce the taxability of your future Social Security benefits is through Roth conversions and robust tax planning throughout your retirement journey.
- Roth Conversions: Converting a portion of your traditional IRA or 401(k) to a Roth IRA involves paying taxes on the converted amount now. However, future qualified withdrawals from your Roth IRA are tax-free. This is incredibly valuable because Roth withdrawals do not count towards your provisional income. By strategically converting funds to Roth accounts in your pre-retirement years or early retirement when your income might be lower, you can create a source of tax-free income that won't trigger federal (or state) taxation of your Social Security benefits down the line. It's a "pay now, save later" approach that can be incredibly effective.
- Utilizing Tax Credits and Deductions: While less direct, maximizing any available tax credits and deductions can lower your AGI, which in turn reduces your provisional income. For retirees, this might include state-specific deductions for medical expenses, property tax credits, or other unique benefits offered by your state. Always check for any property tax credits or other unique benefits available in your state.
- Working with a Tax Professional: The intricacies of federal and state tax laws, especially when factoring in various retirement income streams and potential moves, can be overwhelming. Working with a qualified tax advisor who specializes in retirement planning can be invaluable. They can help you model different scenarios, optimize your withdrawal strategies, and ensure you're taking advantage of every possible tax break. Tools and guidance from services like SmartAsset can also complement this, offering comparisons and estimations that inform your decisions, especially when you are considering Moving to a Tax-Friendly State for Retirement.
Impact on Retirement Planning Decisions
Understanding how Social Security benefits are taxed isn't just an academic exercise; it's a critical component of informed retirement planning. The tax implications can significantly influence major life decisions, from where you choose to live to how you manage your savings and investments throughout your golden years. Ignoring these factors can lead to unforeseen financial strains, while proactive planning can create a more secure and enjoyable retirement.
Choosing Your Retirement Home Wisely
The decision of where to retire often conjures images of sunny beaches or quiet mountain towns. However, for many, the tax implications of a state are just as, if not more, important than the climate or scenery. As we've seen, states vary wildly in how they tax Social Security and other retirement income.
Moving to a state with no income tax, or one that specifically exempts Social Security benefits, can translate into substantial savings over a multi-decade retirement. Imagine the difference in your monthly budget if an additional 50% or 85% of your Social Security check remains in your pocket instead of going to state taxes. This isn't just about income tax, though. You also need to weigh property taxes that might apply in different locations. For example, Moving to Florida From New York: Taxes is a popular move for a reason, as Florida has no state income tax. Conversely, understanding What States Should Retirees Avoid for Taxes? is crucial before settling down. It’s about evaluating the total tax burden—property taxes, sales taxes, and taxes on pensions or 401(k) withdrawals—to find the truly tax-friendly states for your specific financial situation.
The Role of Tax Planning Throughout Retirement
Retirement isn't a static financial period; it's a dynamic phase that requires ongoing attention to tax planning. Your income sources, health expenses, and even tax laws can change year by year, necessitating adjustments to your strategy.
- Annual Review: Make it a habit to review your tax situation annually. This includes looking at your provisional income, anticipating RMDs, and assessing if any life changes (like a large inheritance or a significant investment gain) might push you into a higher tax bracket for your Social Security benefits.
- Flexible Withdrawal Strategies: Don't get locked into one withdrawal strategy for your retirement accounts. If one year you anticipate higher taxable income from a specific event, consider drawing more from Roth accounts or selling investments with minimal capital gains to keep your provisional income in check.
- Understanding Tax Law Changes: Tax laws, both federal and state, are subject to change. States continually evaluate their tax structures, and federal legislation can impact everything from RMDs to the basic thresholds for Social Security taxation. Staying informed through reliable financial news sources or your tax advisor ensures you're always operating with the most current information. Regularly checking for State Income Tax Cuts & Changes for 2026 can help you anticipate future impacts.
By treating tax planning as an ongoing, active part of your retirement strategy, you empower yourself to adapt, optimize, and ultimately, keep more of your hard-earned money.
Table: State Social Security Tax Status Overview (2026)
To give you a clearer picture, here's a table summarizing how each state generally treats Social Security benefits. Remember, specific thresholds and exemptions can apply, so always verify with your state's tax department or a professional.
| State | Social Security Tax Status (2026) | Notes & Key Considerations |
|---|---|---|
| Alabama | Not Taxed | Tax-friendly for retirees. |
| Alaska | Not Taxed | No state income tax. |
| Arizona | Not Taxed | Exempt for most residents. |
| Arkansas | Not Taxed | Exempt for most residents. |
| California | Not Taxed | Tax-friendly for SS. |
| Colorado | Partially Taxed | Exempt for lower/middle-income; age-based exemptions. |
| Connecticut | Partially Taxed | Exempt for lower/middle-income; AGI thresholds apply. |
| Delaware | Not Taxed | General pension exclusion includes SS. |
| Florida | Not Taxed | No state income tax. |
| Georgia | Not Taxed | General retirement income exclusion. |
| Hawaii | Not Taxed | Exempt. |
| Idaho | Not Taxed | Exempt. |
| Illinois | Not Taxed | Exempt for most retirement income. |
| Indiana | Not Taxed | Exempt. |
| Iowa | Not Taxed | Phasing out, fully exempt as of 2026. |
| Kansas | Partially Taxed | Exempt for lower/middle-income (recent changes). |
| Kentucky | Not Taxed | General pension exclusion includes SS. |
| Louisiana | Not Taxed | Exempt. |
| Maine | Not Taxed | Offers a pension income deduction that can include SS. |
| Maryland | Not Taxed | General pension exclusion includes SS. |
| Massachusetts | Not Taxed | Exempt. |
| Michigan | Not Taxed | Phasing out pension tax, SS exempt for most. |
| Minnesota | Partially Taxed | State-specific income thresholds for taxation. |
| Mississippi | Not Taxed | Exempt. |
| Missouri | Partially Taxed | Exempt for lower/middle-income (recent changes). |
| Montana | Partially Taxed | Deduction may reduce or eliminate tax for most. |
| Nebraska | Partially Taxed | Exempt for lower/middle-income (recent changes). |
| Nevada | Not Taxed | No state income tax. |
| New Hampshire | Not Taxed | No state income tax on earned income or SS. (Taxes interest/dividends) |
| New Jersey | Not Taxed | Pension exclusion can make SS tax-free for many. |
| New Mexico | Partially Taxed | Deduction available; income thresholds apply. |
| New York | Not Taxed | Exempt for most residents. |
| North Carolina | Not Taxed | Exempt. |
| North Dakota | Not Taxed | Exempt for most residents. |
| Ohio | Not Taxed | Offers a retirement income credit. |
| Oklahoma | Not Taxed | Exempt for most residents. |
| Oregon | Not Taxed | Exempt for most residents. |
| Pennsylvania | Not Taxed | Exempt for most retirement income. |
| Rhode Island | Partially Taxed | AGI thresholds apply for exemption. |
| South Carolina | Not Taxed | Retirement income deduction. |
| South Dakota | Not Taxed | No state income tax. |
| Tennessee | Not Taxed | No state income tax (only interest and dividends until 2021). |
| Texas | Not Taxed | No state income tax. |
| Utah | Partially Taxed | Retirement tax credit can offset/eliminate tax for many. |
| Vermont | Not Taxed | Exempt for lower/middle-income; AGI thresholds apply. |
| Virginia | Not Taxed | General pension exclusion includes SS. |
| Washington | Not Taxed | No state income tax (capital gains tax only). |
| West Virginia | Not Taxed | Phasing out tax on SS; fully exempt by 2026. |
| Wisconsin | Not Taxed | Exempt for most residents. |
| Wyoming | Not Taxed | No state income tax. |
Disclaimer: Tax laws are complex and subject to change. The information provided in this guide is for general informational purposes only and should not be considered tax or financial advice. Always consult with a qualified tax professional or financial advisor for personalized advice regarding your specific situation.