Do You Pay State Tax on Pension Income?
It's incredibly frustrating trying to make sense of your retirement income, especially when it comes to state taxes. Many people assume that once they retire, their pension income will be treated the same way across the board, only to find a bewildering patchwork of rules depending on where they live. This guide aims to clear up that confusion, diving deep into how different states tax pension income and what you can do to navigate these complexities.
The Complex Landscape of State Pension Taxation
When you're looking forward to retirement, the last thing you want is a surprise tax bill from your state government. The reality is, how your pension income is taxed can vary dramatically from one state to another, making careful planning absolutely essential. It's not a one-size-fits-all scenario, and what might be tax-free in Arizona could be fully taxable in a state like Vermont. This patchwork system can feel arbitrary, but understanding the underlying reasons and factors is the first step toward smart retirement planning.
Why State Rules Vary So Wildly
The main reason for the diversity in state pension taxation stems from each state's independent approach to generating revenue and attracting residents. Some states prioritize attracting retirees by offering generous tax exemptions, while others have broader tax bases that include various forms of retirement income. For instance, states that rely heavily on sales or property taxes might be more inclined to offer income tax breaks for retirees to encourage them to settle down and contribute to the local economy in other ways. Conversely, states with high income tax rates often apply these rates across a wider range of income sources, including pensions, to fund their public services.
Moreover, historical tax policies play a significant role. Some states have never taxed income, including pensions, while others have progressively introduced or modified taxes on retirement income over decades. These policies are often influenced by legislative priorities, economic conditions, and even voter referendums. It means that the rules aren't static; they can and do change, sometimes annually, so what was true last year might not be true for your next tax filing. This constant evolution is part of what makes it so challenging to keep up, especially when you're simply trying to enjoy your hard-earned retirement.
Key Factors Determining Your State Tax Liability
Beyond the state's general tax policy, several personal factors play a crucial role in determining how your pension is taxed. The most important of these is your domicile. This isn't just where you spend most of your time; it's your true, fixed, and permanent home, the place where you intend to return whenever you are absent. Establishing domicile in a state with favorable pension tax laws is a key strategy for many retirees. For more information on what constitutes your legal residence, check out our guide on State Tax Residency Rules Explained.
Another critical factor is the type of pension you receive. Some states differentiate between public (government, military, state employee) and private pensions. Military retirement income, for example, often receives special exemptions in many states. Furthermore, whether your pension comes from a defined benefit plan or a defined contribution plan (like a 401(k) or IRA) can also influence its taxability, although generally, states treat withdrawals from these retirement accounts similarly to pension income. It's not uncommon for states to have different rules for different categories, adding another layer of complexity that can make you feel like you need a tax attorney just to understand your own income.
States That Are Super Pension-Friendly (Tax Exemptions Galore!)
If you're planning your retirement move or simply evaluating your current situation, knowing which states are particularly generous with pension exemptions can be a huge relief. These states understand the appeal of tax-free retirement income and often leverage it to attract a robust senior population. For many, the financial relief offered by these states translates directly into a higher quality of life in retirement, allowing pension income to stretch further.
The "No Income Tax" States
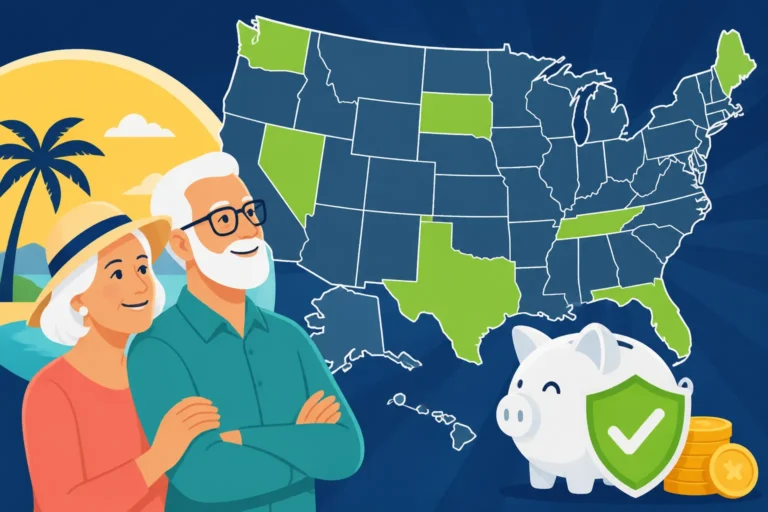
The easiest way to avoid state income tax on your pension is, quite simply, to live in a state that doesn't have a broad-based individual income tax at all. This means your pension income, along with any other earned income, capital gains, or interest, is not subject to state income taxation. This is a massive draw for retirees looking to maximize their post-retirement income. Currently, there are eight such states that are famously income-tax-free, and they make up the States With No Income Tax (2026 Full List).
These states include Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. While New Hampshire and now also Washington (with its capital gains tax) tax some forms of income, they still generally do not tax wages or pension income. For instance, New Hampshire only taxes interest and dividends, though that's also being phased out. Therefore, if you reside in one of these states, you can typically count on your pension income being completely exempt from state income taxes. This simplicity is often a huge relief for retirees who are tired of navigating complicated tax codes. Just remember that "no income tax" doesn't mean "no taxes at all"—these states often make up for it with higher property or sales taxes. For example, while Florida boasts no state income tax, establishing How to Establish Florida Domicile properly is key to enjoying those benefits.
States with Broad Pension Exclusions
Even beyond the states with no general income tax, there are a number of states that, despite having a state income tax, offer significant or even full exemptions for pension income. These states recognize the importance of providing a tax-friendly environment for their senior residents, often to retain their experienced population or attract new retirees. For many, moving to one of these states can mean a substantial increase in their disposable retirement income.
States like Illinois, Mississippi, and Pennsylvania are well-known for broadly exempting most or all qualified retirement income, including pensions, from state income tax. In Pennsylvania, for example, all qualified retirement income, including payments from pensions and IRAs, is exempt from state income tax, regardless of age or income level. This means if you're receiving a pension, it's generally free from state income tax there. Similarly, Illinois exempts most retirement income from state taxation. It’s always critical to verify what "qualified" means in each state's tax code, as there can be nuances, but generally, these states offer a very favorable environment for pensioners. For a more exhaustive breakdown of how different types of retirement income are treated, our Retirement Income Exclusions by State guide provides a detailed overview. SmartAsset often highlights these states in their "best states for retirees" rankings due to these generous exemptions.
States with Partial or Targeted Pension Exemptions
The middle ground in state pension taxation is where things get truly intricate. Many states levy an income tax but offer various carve-outs, exclusions, or deductions for specific types or amounts of pension income. This means your pension might be partially exempt, or fully exempt up to a certain dollar amount, or only exempt if it falls into a particular category. Understanding these nuances is key to accurately planning your retirement finances and avoiding unexpected tax liabilities.
Age-Based or Income-Based Exclusions
A common approach among states that tax pensions is to offer exclusions based on age or income level. For instance, a state might allow taxpayers over the age of 65 to exclude a certain amount of their pension income from taxation. The logic here is often to provide relief to seniors, especially those on fixed or lower incomes, who might struggle more with a full tax burden. This can be a significant benefit, effectively reducing the taxable portion of your pension.
Colorado, for example, offers a generous retirement income subtraction for those 65 and older, and a smaller one for those between 55 and 64, which applies to various types of retirement income, including pensions. Georgia offers an exclusion for taxpayers 62 and older for various types of retirement income, including pensions, up to a certain amount. These exclusions mean that while your entire pension might technically be "taxable," a significant chunk of it could be exempt, making these states more appealing than they might initially appear. It’s a bit like finding a hidden discount code on a big purchase – you just need to know where to look and if you qualify.
Public vs. Private Pension Differences
Another layer of complexity comes from how states often differentiate between public and private pensions. Public pensions typically refer to income from federal, state, or local government retirement plans, including teacher pensions, municipal worker pensions, and sometimes even Railroad Retirement Board benefits. Private pensions, on the other hand, come from employer-sponsored plans in the private sector. The distinction matters because many states offer more favorable tax treatment, or even full exemptions, for public pensions compared to private ones.
For example, states might fully exempt federal and state government pensions while only partially exempting or fully taxing private pensions. This is often due to historical agreements, constitutional provisions, or a desire to reward public service. New York, for instance, generally exempts federal, New York State, and local government pensions from state income tax, but private pensions might be subject to tax unless they fall under other exclusions. This means that two retirees living side-by-side, one a retired public school teacher and the other a retired corporate executive, could see vastly different state tax bills on their identical pension amounts.
Military Retirement Income Exemptions
A notable and often celebrated category of pension exemptions relates to military retirement income. Recognizing the service and sacrifice of veterans, many states offer full or partial exemptions for military pensions. This is a powerful incentive for retired military personnel to choose specific states for their post-service lives.
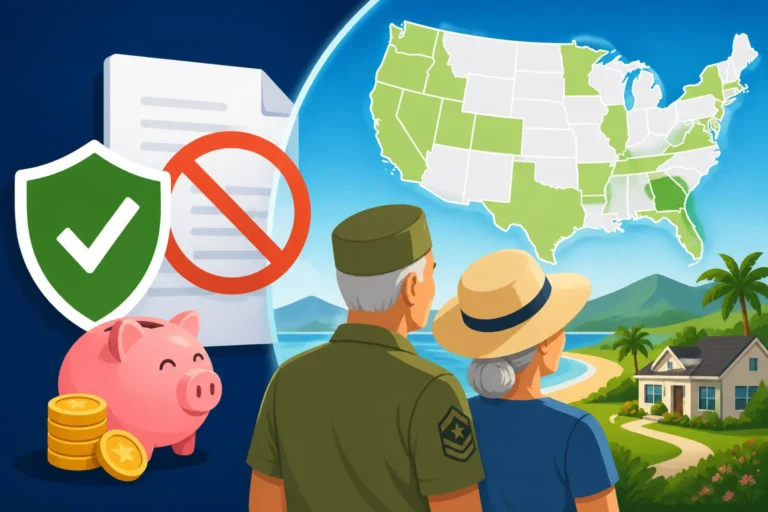
As of 2024, a significant majority of states fully exempt military retirement pay from state income taxes. This includes states like Alabama, Arizona, North Carolina, and Virginia, among many others. Some states, while not offering full exemption, provide a substantial exclusion amount. For retired military members, understanding these state-specific exemptions is crucial. For a comprehensive list, our guide on Military Retirement Tax by State (Full List) can be an invaluable resource. This specific exemption can sway relocation decisions, especially for those who have served and are looking for a state that truly honors their commitment through tangible tax benefits. SmartAsset’s tools can help compare these benefits across different states when evaluating retirement locations.
States Where Pension Income is Generally Taxable
While the idea of a tax-free or significantly exempt pension sounds wonderful, it's not the reality everywhere. A number of states generally consider pension income taxable, often treating it similarly to other forms of ordinary income. This doesn't necessarily mean these states are "bad" places to retire, but it does mean that pensioners need to be acutely aware of their potential state income tax liability and factor it into their financial planning.
States That Tax All or Most Retirement Income
Some states have a broader approach to income taxation, extending their reach to most forms of retirement income, including pensions, without offering extensive exemptions or large exclusions. These states typically have a comprehensive state income tax structure that applies to wages, investment income, and retirement distributions alike. For example, states like California and Oregon are known for their relatively high income tax rates, and generally, pension income is fully taxable in these states, subject to their progressive tax brackets.
In these states, your pension will be added to your other taxable income, and you'll pay tax based on the applicable rates. This can come as a shock to retirees moving from states with more generous exemptions. It means that a significant portion of your pension could be siphoned off by state taxes, potentially impacting your retirement budget. While there might be some minor deductions or credits available, they usually don't amount to the broad exemptions seen in other states. Therefore, thorough planning is essential, perhaps even considering if a move to a more tax-friendly state like those mentioned in Most Tax-Friendly States for Retirees 2027 could be beneficial.
Understanding Taxable Thresholds and Brackets
Even in states where pension income is generally taxable, the actual amount you pay will depend on the state's tax structure, particularly its income tax brackets and any standard deductions or personal exemptions available. Many states operate on a progressive income tax system, meaning higher income earners pay a higher percentage of their income in taxes. This also applies to pension income.
For instance, if your state has a progressive tax system, the first portion of your pension might be taxed at a lower rate, while subsequent portions fall into higher tax brackets. States often have a specific threshold below which income is not taxed, or a standard deduction that reduces your taxable income. Our guide on How State Tax Brackets Work: Marginal vs Effective can help clarify this for general income, and the principles often apply to pension income as well. You might also find a universal standard deduction or personal exemptions that could reduce your overall taxable income, even if there isn't a specific "pension exemption." It’s vital to look at the whole picture: the raw tax rate is just one piece of the puzzle; deductions, exemptions, and credits can significantly alter your final tax bill. SmartAsset provides good resources to estimate your tax burden in various states based on your income levels.
Navigating Multi-State Pension Taxation
The complexities really ramp up when your pension crosses state lines. Whether you earned your pension in one state and retired in another, or you're a "snowbird" splitting your time, understanding which state has the right to tax your pension income is crucial. This is where the concepts of domicile, residency, and source income truly come into play, often leading to confusion and, unfortunately, potential double taxation if not handled correctly.
When You Move After Retirement
One of the most common scenarios of multi-state taxation occurs when you earn a pension over years of working in one state, but then decide to retire and move your permanent residence (domicile) to a different state. The fundamental question becomes: which state has the right to tax that pension income? Generally, the state where you reside at the time you receive the pension payments is the primary state that will attempt to tax it. This is because pension income, for most states, is considered income of the current resident, not income sourced to the state where it was earned.
However, there are exceptions. Some states, particularly those known for aggressively pursuing former residents' income, might try to argue that a portion of your pension is "sourced" to their state because you performed the work there. California, for example, is notoriously diligent about its residency rules and can be challenging to leave from a tax perspective. For most states, though, if you've properly established a new domicile, your pension will be taxed by your new resident state, or not at all if you moved to a States With No Income Tax (2026 Full List). The key here is proving your intent to establish a new permanent home, which involves actions like changing your driver's license, registering to vote, moving personal belongings, and updating financial accounts. Our guide on How to Change Your State Residency for Taxes details the steps you need to take.
The Role of Reciprocity Agreements
While less common for pension income specifically, reciprocity agreements are a vital concept in multi-state taxation, primarily for wage income, and understanding them can shed light on why pensions are often treated differently. State reciprocity agreements are pacts between states that allow residents of one state who work in another to only pay income tax to their state of residence, rather than filing returns in both states. This simplifies things immensely for commuters. For instance, if you Live in PA Work in NJ: Reciprocity ensures you only pay tax to Pennsylvania on your wages.
However, these agreements typically apply to current wage income and rarely extend to pension income. Pension income is generally considered passive income or income derived from past employment, and thus, states don't usually have reciprocity agreements covering it. This means that if your current resident state taxes pensions, your pension will be subject to that state's tax, regardless of where you earned it or if that earning state has a reciprocity agreement with your current state. If your resident state does tax pensions, and your former working state also attempts to tax it, you might need to claim a Credit for Taxes Paid to Another State to avoid double taxation. It's a complex area, and one that highlights the differences between how states view and tax various types of income. For more on these arrangements, refer to our article on State Reciprocity Agreements Explained.
Here's a quick overview of how a few example states handle general pension income:
State General Approach to Pension Income Notes & Exclusions (simplified) My Pension, Your Taxes: States Where It's Taxed (or not!)
It’s no secret that thinking about retirement finances can be a real headache. After working for decades, you look forward to receiving that hard-earned pension, and the last thing you want is for a chunk of it to vanish into state income tax. The truth is, whether you pay state tax on pension income is one of the most variable and sometimes baffling aspects of retirement planning in the U.S. There's no universal rule, and what's tax-free for your friend in Florida might be fully taxable for you in New York. This guide will help you understand this complex landscape, state by state, so you can plan with confidence.
The Diverse Ways States Handle Pension Income
The sheer diversity in state tax laws is often the biggest surprise for people nearing retirement. Unlike federal taxes, where the rules are consistent across the nation, state governments have complete autonomy over their tax policies. This leads to a vibrant, albeit sometimes confusing, mix of approaches to taxing retirement income. Some states actively try to attract retirees with generous tax breaks, while others have broader tax bases that include pensions, sometimes with specific exemptions thrown into the mix.
No Income Tax States: The Golden Ticket
Let’s start with the states that make it easiest: those without a state income tax at all. If a state doesn't have an income tax, it naturally doesn't tax your pension income. This is often seen as the "golden ticket" for retirees looking to maximize their pension payouts. Currently, there are eight such states: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. These states fund their public services through other means, such as sales taxes, property taxes, or severance taxes on natural resources.
It’s a huge draw, and for many, the simplicity alone is worth considering a move. Imagine not having to worry about state income tax forms for your pension every year! However, it's crucial to remember that "no income tax" doesn't mean "no taxes at all." You'll still pay federal income tax, and these states often have higher property taxes or sales taxes to make up for the lack of income tax revenue. For example, while Florida has no state income tax, it does have robust property taxes. Understanding the full picture of the Cost of Living vs Taxes by State is essential before making any major moves.
States with Full or Near-Full Pension Exemptions
Beyond the no-income-tax states, there's another group of states that, despite having a general income tax, offer extremely generous exemptions for pension income. These states are often considered highly tax-friendly for retirees. They understand that a large retiree population can boost the local economy in other ways, such as through property and sales tax contributions, so they actively create an appealing tax environment for seniors.
States like Illinois, Mississippi, and Pennsylvania are prime examples of this approach. In Pennsylvania, all qualified retirement income, including payments from pensions and withdrawals from 401(k)s and IRAs, is entirely exempt from state income tax. This applies regardless of your age or income level, making it one of the most attractive states for pensioners. Similarly, Illinois exempts most retirement income from state taxation. These are significant benefits that can substantially increase your take-home pension amount. When looking at overall tax burdens for retirees, SmartAsset often highlights these states because of their pension-friendly policies. For a deeper dive into the specific exclusions, you might find our guide on Retirement Income Exclusions by State incredibly helpful.
The Nuances of Partial Pension Taxation
The waters get a bit murkier when we talk about states that partially tax pension income. This isn't a straightforward "yes" or "no" answer, but rather a "it depends." These states often have specific rules based on age, income level, or the type of pension you receive. It requires a closer look at their tax codes to understand your exact liability.
Age-Based and Income-Based Exclusions
Many states that tax pensions offer some form of relief based on your age or your total retirement income. This is a common way for states to provide a tax break to seniors, especially those on a fixed income, without completely eliminating pension taxation for everyone. The idea is to ease the financial burden on older residents.
For instance, Colorado allows taxpayers to subtract a certain amount of their retirement income, including pensions, from their taxable income. This subtraction is more generous for those aged 65 and older, and a smaller amount is available for those between 55 and 64. Georgia offers a significant exclusion for individuals aged 62 and older, allowing them to subtract up to $65,000 per person ($130,000 for a couple) from their retirement income, which covers pensions, annuities, interest, dividends, and capital gains. These age and income thresholds are crucial to understanding your tax picture. It’s like a tiered discount system – the more you know about the qualifications, the better you can save. These types of exclusions are important when trying to Minimize State Taxes in Retirement.
Differentiating Public, Private, and Military Pensions
The type of pension you receive can also play a huge role in its state taxability. States often distinguish between public pensions (from government employment), private pensions (from corporate employers), and military retirement pay, treating each category differently. This can be a significant factor for many retirees.
Generally, many states offer more favorable treatment, often full exemptions, for public pensions, particularly those from federal or state government service. For example, New York exempts federal, New York State, and local government pensions from state income tax. However, private pensions in New York might be taxable unless they fall under a general age-based exclusion. This means two retirees with similar income amounts but different pension sources could have vastly different state tax outcomes. Military retirement income is a particularly strong example of this differentiation, with a large number of states offering full exemptions as a way to honor veterans. For instance, Virginia, North Carolina, and Michigan are among the states that fully exempt military retirement pay. Our guide on Military Retirement Tax by State (Full List) details these specific exemptions and is an invaluable resource for military retirees.
States Where Pension Income is Generally Taxable
Now, let's talk about the states where pension income is more likely to be fully or largely taxable. This doesn't mean these states are inherently "bad" for retirees, but it does mean that state income tax on your pension needs to be a primary consideration in your financial planning. In these states, your pension will likely be treated as ordinary income, subject to the state's regular income tax rates.
States with Broader Income Tax Bases
Several states have comprehensive income tax systems that apply to most forms of income, including pensions, without offering the broad exemptions or large exclusions seen elsewhere. These states rely on a wider tax base to fund their public services, and retirement income is typically part of that base. California and Oregon are often cited as examples of states with relatively high income tax rates that generally tax pension income.
In these states, your pension payments will be combined with any other taxable income you receive, and the total will be subject to the state's progressive income tax rates. This can lead to a significant portion of your pension being paid in state taxes. For someone moving from a state with no income tax or broad pension exemptions, this can be a jarring change and a substantial hit to their retirement budget. It's not uncommon for retirees in such states to re-evaluate their financial strategy or even consider relocating if the tax burden becomes too high. For a deeper understanding of how these rates apply, exploring topics like California Income Tax Brackets 2026 or New York Income Tax Brackets 2026 can provide context for how your pension income would be treated.
Understanding Tax Brackets, Deductions, and Credits
Even in states that tax pension income, it's not simply a flat tax on every dollar. Most states use a graduated or progressive tax bracket system, similar to federal income tax, where different portions of your income are taxed at different rates. This means your pension might be taxed at a lower rate for the initial amounts and then at progressively higher rates as your income increases.
Furthermore, states often provide standard deductions or personal exemptions that can reduce your taxable income. While these might not be specific to pensions, they can lower your overall income subject to tax, including your pension. For example, if your state has a $10,000 standard deduction, and your pension is your only income, only the amount exceeding $10,000 would be taxable (assuming no other exemptions apply). Some states may also offer various tax credits for seniors, homeowners, or other specific groups that could offset your tax liability. It’s crucial to delve into the specific tax forms and instructions for your state to identify any such benefits. For a state-by-state comparison of general deductions, our article on State-by-State Standard Deductions 2026 can provide a good starting point. This holistic approach is why many financial experts, including those often quoted by SmartAsset, recommend looking at all available deductions and credits, not just the base tax rate, when assessing your retirement finances.
Strategizing Your State Residency for Pension Tax Benefits
When you're looking at retirement, where you choose to lay down roots can have a massive impact on your financial well-being, especially concerning pension taxes. It's not just about finding a nice climate or being close to family; it's about making a smart tax decision. Strategizing your state residency is one of the most powerful tools in a retiree's arsenal to manage their tax burden effectively.
Establishing Domicile: More Than Just a P.O. Box
The concept of "domicile" is absolutely critical for state tax purposes, and it’s much more than just where you receive your mail. Your domicile is your true, fixed, and permanent home, the place where you intend to return whenever you are absent. States with income tax are particularly interested in determining your domicile because it dictates where you owe state income taxes. Simply owning a vacation home or spending a few months in a no-income-tax state isn't enough to change your domicile in the eyes of tax authorities.
To effectively establish domicile in a pension-friendly state, you need to demonstrate a clear intent to make that state your permanent home. This involves a series of tangible actions: changing your driver's license and vehicle registration, registering to vote, filing a declaration of domicile (if the state offers one), updating your will and estate plan, changing your mailing address for all financial and legal documents, and physically moving your treasured possessions. For example, if you're trying to establish residency in Texas, which has no state income tax, you'd want to be meticulous about these steps. Without clear evidence of a change in domicile, your former state might still consider you a resident and continue to tax your pension. Our detailed guide on Domicile vs Statutory Residency explains these distinctions and the evidence states look for.
Avoiding Double Taxation and Multi-State Filing Headaches
One of the biggest anxieties for retirees with pensions, especially those who earned their pension in one state but now live in another, is the fear of being taxed twice on the same income. While it's rare to be legally taxed twice on the exact same dollar of pension income, navigating multi-state filing can certainly feel like a punishment. As mentioned earlier, most states consider pension income taxable by your state of residence, not by the state where it was earned.
However, if your former working state is aggressive and tries to tax your pension as "sourced income" while your new resident state also taxes pensions, you might end up filing in both states. In such cases, your resident state will typically offer a tax credit for taxes paid to another state on the same income. This credit prevents true double taxation but adds a layer of complexity to your filing. It's a key mechanism discussed in our guide on How to Avoid Double Taxation Between States. Carefully documenting your domicile change is your best defense against having your former state continue to claim a right to tax your pension. If you're a "snowbird" splitting your time between two states, understanding the Snowbird & Dual-Residency Taxes article will be critical to avoid inadvertently becoming a statutory resident in multiple states.
Practical Tips for Pensioners to Minimize State Tax Burden
Navigating state pension taxes might seem overwhelming, but with a bit of proactive planning and understanding, you can certainly minimize your tax burden. It's all about being informed and making strategic choices that align with your retirement goals. You've worked hard for this money, and you deserve to keep as much of it as possible.
Utilizing Available Deductions and Credits
Even if your state generally taxes pension income, there might be avenues to reduce your taxable amount through various deductions and credits. Many states offer standard deductions or personal exemptions that can lower your overall taxable income, regardless of the income source. For instance, if your state provides a substantial standard deduction for seniors, a significant portion of your pension might fall below that threshold and effectively be untaxed.
Beyond general deductions, some states offer specific credits for retirees, such as property tax credits, homestead exemptions, or credits for medical expenses. While not directly related to your pension, these can reduce your overall state tax bill, essentially freeing up more of your pension income. Always review your state's tax forms and instructions thoroughly, or consult with a tax professional, to ensure you're taking advantage of every applicable benefit. Sometimes, even small credits can add up, especially when compounded over many years of retirement. Our resource on State Tax Credits: Solar, College & Dependent Care might offer insights into other beneficial credits.
Consulting with a Qualified Tax Advisor
Given the intricate and ever-changing nature of state tax laws, one of the best investments you can make is consulting with a qualified tax advisor, especially one with expertise in multi-state taxation and retirement planning. While this guide provides general information, your personal situation—your specific pension type, other income sources, residency history, and future plans—will dictate the best strategy for you.
A tax professional can help you understand the nuances of your state's laws, identify all eligible deductions and credits, and advise you on the proper steps to establish domicile if you're considering a move. They can also help you prepare for potential challenges, such as residency audits from states like California or New York, which are known for their rigorous enforcement. Tools and advice from reputable financial platforms, such as SmartAsset, often emphasize the importance of professional advice for complex tax situations like these. Don't leave money on the table or inadvertently expose yourself to penalties simply because the rules are too complicated to figure out on your own. Investing in expert advice can lead to significant long-term savings and peace of mind.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. State tax laws are subject to change and vary significantly by jurisdiction. It is highly recommended to consult with a qualified tax professional or financial advisor for advice tailored to your specific situation.