Highest Income Tax States in 2026
You’ve worked hard all year, perhaps even landed a significant promotion or a year-end bonus, only to see your take-home pay slashed by a double-digit percentage before it even hits your bank account. Navigating the highest income tax states in 2026 can feel like an uphill battle against your own financial progress. This guide breaks down exactly which states take the biggest bite out of your earnings and how those complex tax structures actually impact your bottom line.
Understanding Progressive vs Flat Tax Systems in 2026
When you look at your pay stub, the number staring back at you in the state withholding column isn't just a random figure. It is the result of a specific philosophical approach to governance and revenue. The divide between progressive and flat tax systems has never been more pronounced. Progressive systems, which most of the high-tax states on our list utilize, operate on the principle that the more you earn, the higher the percentage you should pay. It sounds fair in theory, but in practice, it can lead to "bracket creep" where a modest cost-of-living raise actually pushes you into a much higher tax tier, leaving you with less real purchasing power than before.
The shift toward flat taxes has been a major trend in the mid-2020s, with several states moving away from complex brackets to simplify their codes. However, the states that consistently rank as the most expensive for high earners have doubled down on the progressive model. They argue that these higher rates are necessary to fund the robust social services, infrastructure, and education systems that residents in those regions expect. If you are trying to figure out how these numbers hit your specific wallet, using tools like the paycheck calculators provided by SmartAsset can help you visualize the difference between a 5% flat rate and a 10% progressive top tier.
The most important distinction to understand is the difference between How State Tax Brackets Work: Marginal vs Effective. Your marginal rate is the tax you pay on the very last dollar you earned—the "top" bracket. Your effective rate is the actual percentage of your total income that goes to the state after all brackets and deductions are accounted for. In high-tax states like California or New Jersey, the gap between these two numbers can be massive, especially if you are a high-income professional or a dual-income household.
The Top Tier States with the Highest Marginal Rates in 2026
California continues to hold the crown for the highest top marginal income tax rate in the country as we head forward. If you are a high earner in the Golden State, you aren't just looking at the base brackets; you also have to contend with the Mental Health Services Act tax, which adds an additional 1% surcharge on taxable income in excess of $1 million. For those at the very top of the ladder, the combined rate can exceed 13.3%. This is a staggering figure that significantly changes the calculus for entrepreneurs and C-suite executives deciding where to base their operations.
Moving to the East Coast, New York presents one of the most complex tax landscapes in the nation. While the state rates themselves are high, the real sting comes from the way the state treats different levels of income with a highly granular bracket system. In 2026, New York Income Tax Brackets 2026 remain some of the most aggressive, particularly for those earning over $25 million, who face a top rate that makes the Empire State a very expensive place to call home. When you combine this with the high cost of property and utilities, the "tax-friendly" label is nowhere to be found.
New Jersey and Massachusetts are also major players in the high-tax arena. New Jersey’s top rate for those earning over $1 million is consistently near the 10.75% mark. Meanwhile, Massachusetts made waves with its "Millionaire’s Tax," a 4% surtax on annual income above $1 million that was passed by voters. This shift has changed the state’s reputation from "Taxachusetts"—a nickname it was starting to shed—back into one of the more burdensome states for high-net-worth individuals. Using a resource like SmartAsset to compare these specific Northeast rates can be eye-opening for someone considering a move within the tri-state area.
Hidden Tax Burdens When High Rates Arent the Whole Story
A state's top income tax rate only tells a fraction of the story. You could live in a state with a seemingly moderate income tax but find yourself losing more money than someone in a "high tax" state due to Local & City Income Taxes in the US. Take Maryland, for example. While its top state rate might not look like the highest on a national chart, almost every county in Maryland imposes its own "piggyback" tax, which can add another 3.2% to your total bill. By the time you finish your return, you realize you are paying nearly 9% of your income to various levels of state and local government.
Ohio and Pennsylvania are other prime examples where local taxes can surprise you. In Pennsylvania, the state has a relatively low flat tax, but cities like Philadelphia impose a significant wage tax on anyone living or working within city limits. This can catch remote workers off guard if their employer is based in the city. You might think you've escaped the high-tax trap by living in a suburb, but the residency rules can be quite sticky. It’s always worth checking a State Tax Burden by State 2026 report to see the cumulative effect of sales, property, and local income taxes combined.
Then there is the interplay between income and property taxes. Some states that rank high for income tax actually offer relatively modest property taxes, or vice versa. New Jersey, unfortunately, often hits the "trifecta" of high income tax, high sales tax, and the highest property taxes in the nation. This creates a cumulative pressure that forces many residents to scrutinize their budget every April. If you're feeling the pinch, it might be time to look at Is California Tax Friendly? Full Breakdown just to see how the other side of the country compares, as you might find that "high tax" means different things depending on your specific assets.
The Impact of 2026 Tax Reforms and Legislative Shifts
The year 2026 is a pivotal one for state tax policy, as many pandemic-era surpluses have been spent, and states are looking for new ways to balance their books. While some states have been on a path toward cutting rates, the "highest tax" states have often taken the opposite approach, implementing "fair share" surcharges or increasing the number of brackets to capture more revenue from top earners. Minnesota, for instance, has introduced new taxes on net investment income for high earners, which has effectively pushed its total tax burden into the top tier of US states.
Inflation has also played a major role in how you experience these high rates. Some states have been slow to adjust their bracket thresholds for inflation, a phenomenon known as "tax bracket creep." This means that as your salary increases just to keep up with the cost of eggs and gas, you are being pushed into a tax bracket intended for "the wealthy" of five years ago. Staying informed on State Income Tax Cuts & Changes for 2026 is essential if you want to understand if your state legislature is offering any relief or if you should expect a larger bill next year.
We are also seeing a rise in "mansion taxes" and other indirect income taxes that target wealth rather than just traditional wages. Washington State, which famously has no personal income tax, now has a capital gains tax that functions very similarly for high-net-worth individuals. This move has blurred the lines between "no-tax" states and "high-tax" states. When evaluating your 2026 liabilities, look beyond the standard W-2 income and consider how your investments and property sales will be treated by the state.
Comparison Table of Highest Income Tax States in 2026
To give you a clearer picture of how these states stack up, the following table compares the top marginal rates and the income thresholds where those rates kick in. Keep in mind that these figures represent the state-level tax and do not include local or city surcharges, which can significantly increase the total.
| State | Top Marginal Rate (2026) | Income Threshold (Single Filer) | Notable Surcharges |
|---|---|---|---|
| California | 13.3% | Over $1,000,000 | Includes 1% Mental Health Tax |
| New York | 10.9% | Over $25,000,000 | NYC Income Tax Explained (2026 Rates) adds ~3.8% |
| New Jersey | 10.75% | Over $1,000,000 | High local property tax burden |
| District of Columbia | 10.75% | Over $1,000,000 | Functions as both city and state |
| Hawaii | 11.0% | Over $200,000 | Progresses quickly at lower levels |
| Minnesota | 9.85% | Over $193,240 | New 1% Investment Income Surcharge |
| Massachusetts | 9.0% | Over $1,000,000 | Includes 4% voter-approved surtax |
| Oregon | 9.9% | Over $125,000 | No state sales tax (the trade-off) |
Strategies for Residents of High Tax States
Living in one of the Highest Income Tax States in 2026 doesn't mean you are powerless. There are several legal strategies to mitigate the impact on your bank account. First and foremost is maximizing your "above-the-line" deductions. Contributions to traditional 401(k) or 403(b) plans are particularly valuable in high-tax states because they reduce your taxable income at your highest marginal rate. If you are in California’s 9.3% bracket, a $20,000 contribution effectively saves you $1,860 in state taxes alone, on top of your federal savings.
Another often-overlooked strategy is the use of Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs). These allow you to pay for healthcare and childcare with pre-tax dollars. In a state like New York, where every dollar is taxed heavily, these accounts provide a double benefit by lowering your state and federal taxable income. You should also look into state-specific credits, such as those for green energy improvements or education savings. Many of these states offer substantial 529 plan incentives to help offset the pain of their high income tax rates.
If you are a business owner or a freelancer, the way you structure your entity can have a massive impact. Some high-tax states have implemented "Pass-Through Entity Taxes" (PTET) as a workaround for the federal SALT cap. This allows the business to pay the state tax on behalf of the owner, effectively turning a non-deductible state tax into a deductible business expense for federal purposes. It’s a complex maneuver, but for those in the top brackets, it can save tens of thousands of dollars. Consulting a professional who uses data from SmartAsset or similar firms can help you model these scenarios.
Considering a Move Domicile vs Residency Rules
When the tax bill becomes too much to handle, the conversation inevitably turns to moving. We’ve seen a significant migration from high-tax states to States With No Income Tax (2026 Full List). However, simply packing your bags and renting an apartment in Florida isn't always enough to satisfy the tax authorities in the state you are leaving. States like New York and California are notorious for conducting residency audits. They will look at your "center of gravity"—where you vote, where your pets live, where you see your doctor, and how many days you spent in the state.
Understanding State Tax Residency Rules Explained is vital if you want to avoid being taxed by two states at once. Most states use the 183-day rule, but that is only part of the equation. If you still maintain a "permanent place of abode" in a high-tax state and spend even a small amount of time there, they may still claim you as a statutory resident. This is especially true for remote workers whose companies are based in New York, thanks to the "convenience of the employer" rule, which allows the state to tax you even if you never set foot in the office.
Before you make a move, you need to calculate the "all-in" cost. Sometimes, moving to a state with no income tax results in much higher sales taxes or a lack of public services that you then have to pay for out of pocket. For example, Highest Income Tax States in 2026 often have the best-funded public universities and hospitals. If you move, will your private costs exceed your tax savings? Always perform a comprehensive cost-of-living comparison before making a decision based solely on the top tax bracket.
Regional Analysis High Tax Pockets Across the US
High taxes aren't just a coastal phenomenon, though the West Coast and the Northeast certainly dominate the rankings. In the West, the "Blue Wall" of California, Oregon, and even parts of the Rockies maintains high rates to support environmental initiatives and expansive social safety nets. Oregon is a unique case; while it has one of the highest income tax rates in the country, it has zero sales tax. For a high-income earner who doesn't spend much on consumer goods, Oregon can actually be more affordable than it looks on paper.
In the Midwest, Minnesota stands out as a high-tax island. It has long maintained a highly progressive system that funds a standard of living often ranked among the best in the country. However, as neighboring states like Iowa and Wisconsin have aggressively cut their taxes or moved toward flat rates, the pressure on Minnesota to remain competitive has increased. Residents there often find themselves weighing the high-quality infrastructure against the nearly 10% of their income going to the state house in St. Paul.
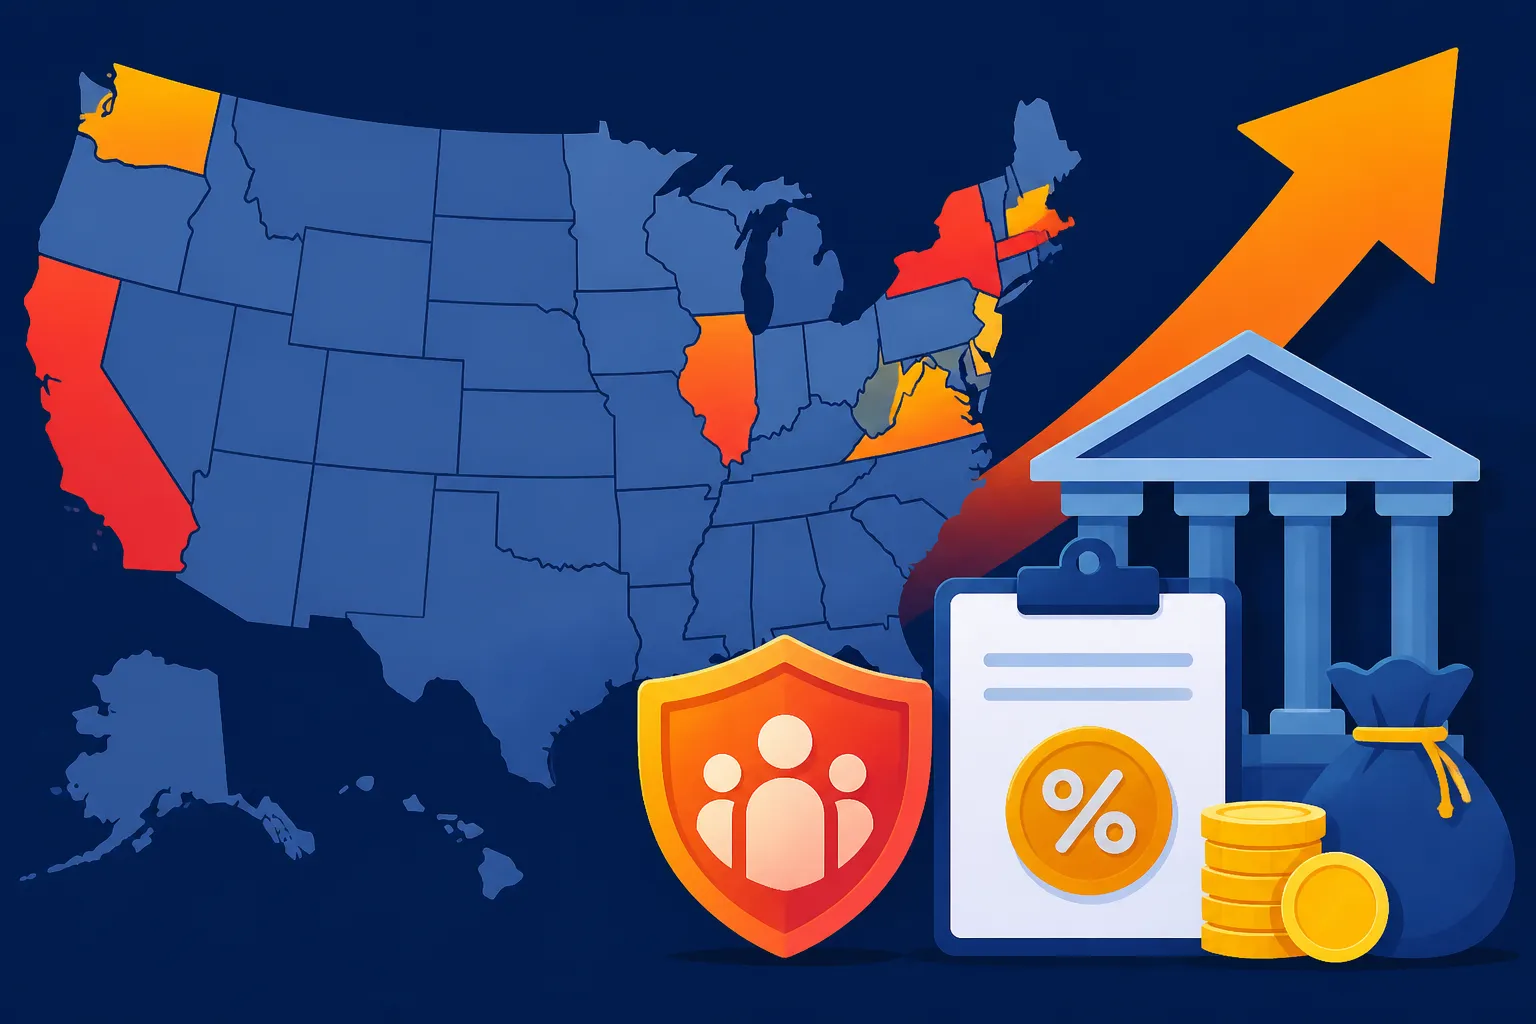
The Northeast remains the most concentrated area of high-income taxes. From Maryland up through Maine, the density of high-earning professionals and the high cost of maintaining aging infrastructure creates a perpetual need for high tax revenue. Even states that were once considered moderate are seeing their effective rates rise as they implement new payroll taxes for family leave and other social programs. If you live in this corridor, staying ahead of Highest Income Tax States in 2026 trends is a necessary part of long-term financial planning.
State Income Tax Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute professional tax, legal, or financial advice. Tax laws, including brackets, rates, and residency rules, are subject to frequent change at both the state and local levels. The data presented reflects projected and current 2026 information, but individual circumstances can significantly alter your actual tax liability. Always consult with a qualified tax professional or Certified Public Accountant (CPA) before making significant financial decisions, changing your state of residency, or filing your tax returns. We do not guarantee the accuracy of any third-party data or tools mentioned herein.