Which States Don’t Tax Social Security or Pensions?
Transitioning into retirement is such a monumental life change, full of exciting possibilities. But let's be real, a huge cloud of worry often hangs over it: how much of your hard-earned Social Security and pension income will disappear to state taxes? It's a common and completely valid concern that can make you second-guess your golden years. This comprehensive guide aims to clear up that confusion, diving deep into which states truly let you keep more of your retirement nest egg.
States That Are Truly Tax-Free for Social Security and Pensions
When you're looking at states that won't touch your Social Security or pension income, there are generally two big categories to consider: those that simply don't have a state income tax at all, and those that have one but offer specific, generous exemptions for retirement benefits. It's a critical distinction because "no income tax" often gets conflated with "no retirement income tax," and while the former implies the latter, it's not the only path to a tax-friendly retirement.
The Nine States with No Income Tax at All
Let's start with the clearest winners for avoiding state income tax on all your earnings, including retirement benefits. These states simply do not levy a broad-based tax on wages, salaries, or other forms of income. This means your Social Security checks and pension distributions sail through untouched by a state income tax bill.
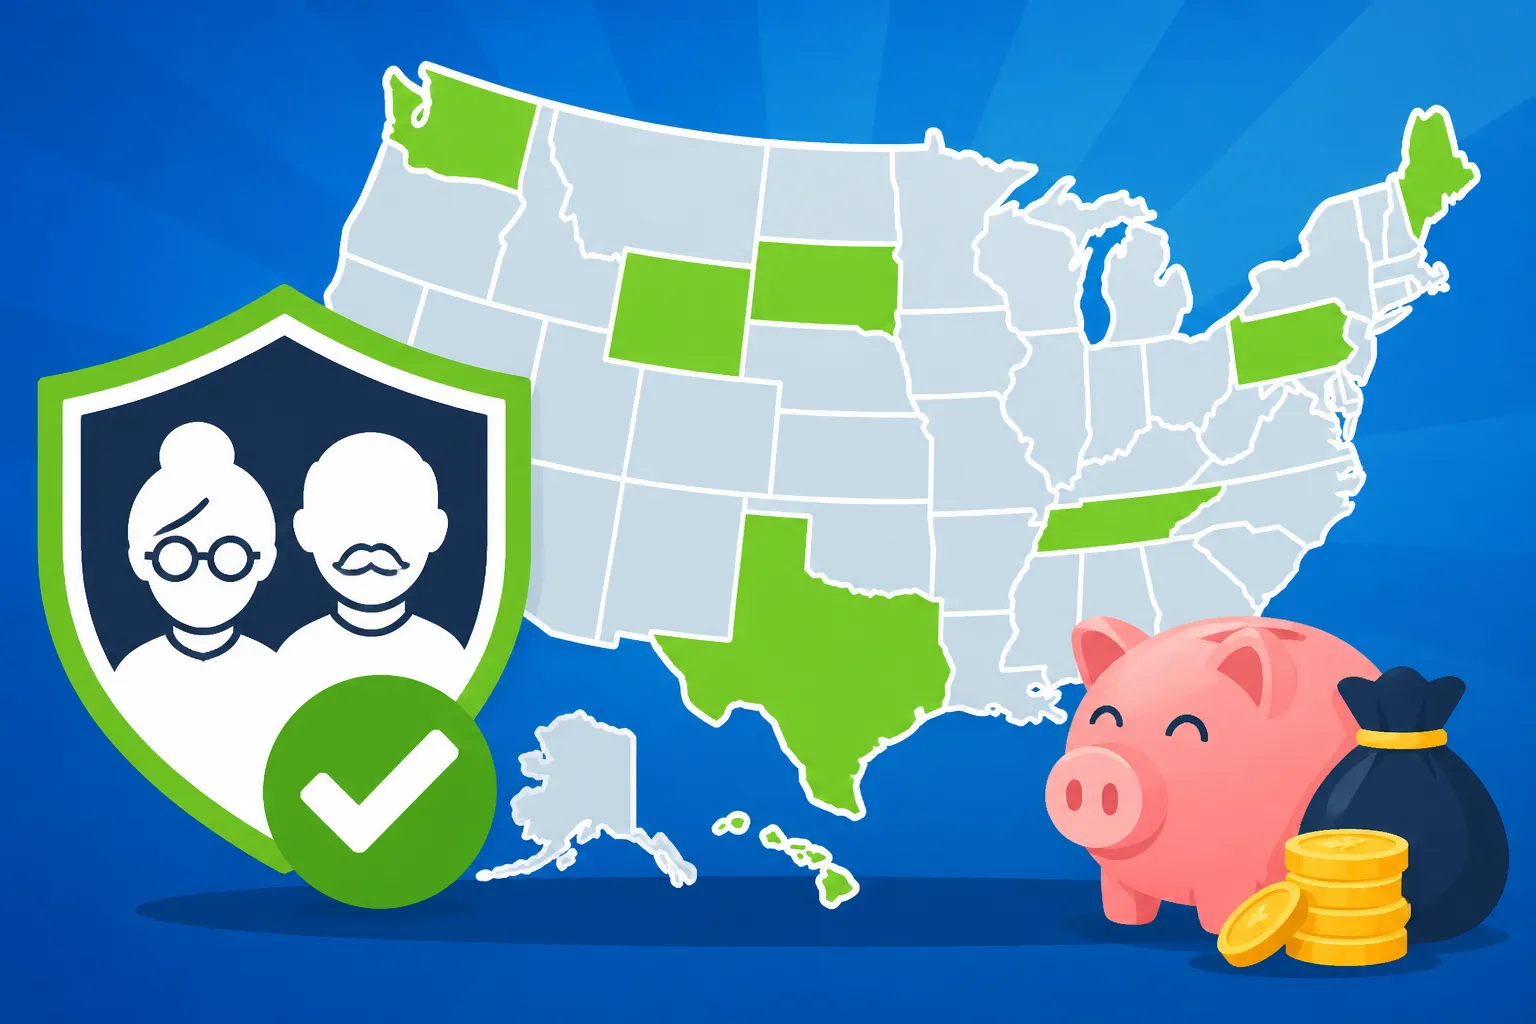
The nine states that historically haven't imposed a general state income tax are:
- Alaska: Known for its vast wilderness, it also boasts no state income or sales tax. However, local sales taxes can apply in some areas.
- Florida: A perennial favorite for retirees, the Sunshine State lives up to its name with no state income tax.
- Nevada: A desert oasis that's also an income tax oasis. You won't find state income taxes here.
- South Dakota: Another state that keeps your income tax-free, offering wide-open spaces and financial freedom.
- Tennessee: The Volunteer State doesn't tax earned income. While it once taxed interest and dividends, that tax has been fully phased out, making it completely income tax-free.
- Texas: The Lone Star State is a massive draw for those seeking no state income tax, though other taxes might be higher.
- Washington: From rainforests to bustling tech hubs, Washington keeps your income tax-free. Note, however, that Washington does have a capital gains tax, but this doesn't apply to Social Security or pension income.
- Wyoming: The Cowboy State offers majestic landscapes and no state income tax.
- New Hampshire: Often grouped with the "no income tax" states, New Hampshire historically taxed interest and dividend income, but not wages. However, the state is phasing out this interest and dividends tax by 2027, further solidifying its status as an income tax haven for retirement. You can learn more about the New Hampshire Interest & Dividends Tax Repeal as it progresses.
For anyone looking to maximize their retirement income, starting your search with these states is often the first step. You'll find a more extensive list and details about these states in our guide on States With No Income Tax (2026 Full List).
States with Income Tax but Full Exemptions for Both Social Security and Pensions
Now, this is where it gets interesting! Several states do have a state income tax on regular earnings, but they've made a deliberate choice to exempt both Social Security benefits and most qualified pension income entirely. This is fantastic news for retirees who might find other aspects of these states appealing, such as a lower cost of living or proximity to family, without having to sacrifice their retirement income to state taxes.
Let's look at some key examples:
- Illinois: The Prairie State has a flat income tax rate, but it stands out because it fully exempts all retirement income, including Social Security benefits and distributions from IRAs, 401(k)s, and public and private pensions. This makes Illinois surprisingly tax-friendly for retirees, even with its general income tax.
- Mississippi: Often overlooked, Mississippi is incredibly generous to retirees. It does have an income tax, but it completely exempts Social Security benefits and all qualified retirement income, including pensions, annuities, and IRA withdrawals.
- Pennsylvania: The Commonwealth of Pennsylvania has a flat income tax, but it provides a broad exemption for most types of retirement income. This includes Social Security benefits, public and private pensions, and withdrawals from retirement accounts like 401(k)s and IRAs, provided certain conditions are met (typically, if distributions begin after age 59½). This makes Pennsylvania a very attractive option for those drawing on diverse retirement income sources.
These states demonstrate that you don't necessarily have to move to a "no income tax" state to keep your Social Security and pension intact. It's about understanding the specific exemptions each state offers. Our detailed States That Don't Tax Pensions (2026) and States That Don't Tax Social Security (2026) guides offer more specifics on these exemptions.
Navigating Partial Exemptions and Income Thresholds
While the states listed above offer full exemption from income tax on Social Security and pensions, many other states have a more nuanced approach. They might tax a portion of your retirement income, offer exemptions up to a certain dollar amount, or only tax Social Security if your income crosses a specific threshold. This makes planning a bit more complex, but it's still crucial to understand.
Social Security Taxation: Federal Rules and State Variations
Even on a federal level, Social Security benefits can be taxable if your "provisional income" exceeds certain limits. Provisional income generally includes your adjusted gross income (AGI) plus non-taxable interest and half of your Social Security benefits. Many states that do tax Social Security often follow these federal guidelines or have their own similar thresholds.
Currently, beyond the states that fully exempt Social Security (either by having no income tax or by specific exemption), there are a handful of states that still tax Social Security benefits to some degree:
- Colorado: Offers a significant retirement income exclusion that can cover most or all Social Security benefits, especially for lower and middle-income retirees. For example, older retirees can exclude up to $24,000 in retirement income, which includes Social Security.
- Connecticut: Follows federal guidelines regarding the taxation of Social Security benefits but offers a substantial income threshold before benefits become taxable. For 2026, many retirees will find their Social Security benefits exempt.
- Kansas: Historically taxed Social Security but has moved to fully exempt it as of the 2024 tax year. This is a big win for retirees there.
- Minnesota: Taxes Social Security benefits using a deduction that limits the taxable amount based on income thresholds, similar to federal rules but with its own state-specific figures.
- Montana: Taxes Social Security to some extent, generally following federal guidelines.
- New Mexico: Taxes a portion of Social Security benefits, but offers a broad income exclusion for various types of retirement income, including Social Security, depending on age and income.
- Rhode Island: Exempts Social Security benefits for taxpayers whose federal adjusted gross income (AGI) falls below a certain amount ($100,000 for single filers, $125,000 for joint filers in some recent tax years).
- Utah: Offers a retirement tax credit that can offset the tax on Social Security and other retirement income, effectively reducing or eliminating the state tax burden for many retirees.
- Vermont: Taxes Social Security income for higher-income retirees, following federal guidelines and offering a deduction for lower and moderate incomes.
- West Virginia: Has been phasing out its tax on Social Security benefits. For 2026, most Social Security income is expected to be exempt.
This list can change, so it's always smart to check the latest rules. You can dive into more specifics in our guide Does My State Tax Social Security Benefits?.
Pension and Retirement Account Taxation: A Mixed Bag
When it comes to pensions and distributions from retirement accounts like 401(k)s and IRAs, states' approaches vary wildly. Some states fully exempt these types of income, as we've already discussed with Illinois, Mississippi, and Pennsylvania. Others offer partial exemptions, exclusions, or credits, and still others tax them just like any other income.
- States with Generous Exclusions: Beyond the completely "no income tax" states, some states with income tax offer significant exclusions for retirement income. For instance, New Jersey provides a substantial exclusion for pension and retirement income for eligible taxpayers, particularly for those with lower to moderate incomes. Georgia offers a generous exclusion for retirement income for those 65 and older, which can shield a significant portion of pensions and other retirement distributions from state tax. You can find more details in our Retirement Income Exclusions by State article.
- States with Partial Exemptions or Deductions: Many states will allow you to deduct a certain amount of your pension or retirement income from your taxable income. For example, Colorado allows a retirement income subtraction for eligible taxpayers, reducing their taxable income. The amount depends on age and the type of retirement income.
- States That Tax Most Retirement Income: Other states, such as California and New York, generally tax pension income and distributions from 401(k)s and IRAs at their regular income tax rates, without specific broad exemptions for general retirement income (though specific types of pensions, like military pensions, may have exemptions in some states). If you're considering moving to one of these states, or if you already live there, it’s vital to understand the California Income Tax Brackets 2026 or New York Income Tax Brackets 2026 and how they might affect your retirement distributions.
Understanding these nuances is key. A financial planning tool like those from SmartAsset can be incredibly helpful in modeling these different tax scenarios, allowing you to compare your options and see the real impact on your bottom line.
The Bigger Picture: Beyond Just Income Tax for Retirees
It's easy to get laser-focused on income tax, especially when Social Security and pensions are on the line. But here’s the tough reality: a state with no income tax might still be expensive for retirees if other taxes are high. When planning your retirement relocation, you absolutely must look at the full picture of your tax burden.
Property Taxes: The Often Overlooked Burden
States that forgo income tax often make up for that revenue in other ways, and property taxes are a huge one. For retirees who own their homes, this can be a significant annual expense that dwarfs any income tax savings.
- High Property Tax States: States like Texas, which has no state income tax, are known for their relatively high property tax rates. While you might not pay income tax, your property tax bill could be substantial, especially in desirable areas like Austin or Dallas. Similarly, New Hampshire, another no-income-tax state, often has some of the highest property taxes in the nation.
- Homestead Exemptions and Senior Relief: The good news is that many states, including some with higher property taxes, offer relief for seniors and homeowners through homestead exemptions or circuit breaker programs. For instance, Florida has a generous homestead exemption that reduces the taxable value of your primary residence, providing significant savings. In Georgia, senior homeowners can often qualify for additional property tax exemptions. When researching, always ask about these specific breaks; they can make a huge difference in your annual housing costs. Our guide on Property Tax Credits & Homestead Exemptions by State can provide more state-specific details.
It’s not just about the rate; it's about the assessed value and available exemptions. So, if a state looks good on income tax, always double-check the local property tax situation.
Sales and Other Taxes: The Daily Impact on Your Budget
Beyond property taxes, states collect revenue through sales taxes, excise taxes (on things like gas and alcohol), and often local sales taxes. These can eat into your retirement budget, especially if you plan on spending more on goods and services.
- Sales Tax Rates: States like Tennessee and Washington, both with no state income tax, tend to have higher combined state and local sales tax rates. Every time you buy groceries (though some states exempt food), clothing, or make a larger purchase, a piece of that money goes to the state.
- Everyday Spending: Consider your lifestyle. If you plan to travel extensively, dine out frequently, or make many purchases, higher sales taxes can add up quickly over the course of a year. Conversely, a state with a higher income tax might have lower sales taxes, making your daily purchases more affordable.
This holistic view is why resources like SmartAsset's retirement tax friendliness comparison tools are so valuable. They often take into account all these factors – income, sales, and property taxes – to give you a more accurate picture of your overall tax burden. This helps retirees understand the State Tax Burden by State 2026 and make more informed decisions.
Strategic Planning for a Tax-Efficient Retirement
Choosing where to retire based on taxes is a big decision, and it’s one that requires careful thought and planning. It's not just about picking a state; it's about making a strategic move that aligns with your financial goals and lifestyle.
Establishing Domicile: Proving Your New Home
If you're making a move specifically to reduce your state tax burden, particularly from a high-tax state like California or New York to a low-tax haven like Florida or Texas, simply buying property isn't enough. You need to officially establish domicile. Domicile is your true, fixed, and permanent home—the place where you intend to return whenever you are absent. States, especially those with aggressive tax auditors, will look for concrete proof of your intent to reside permanently.
This means more than just changing your mailing address. You should:
- Obtain a new driver's license in your new state.
- Register your vehicles there.
- Register to vote.
- Close bank accounts in your old state and open new ones in your new domicile.
- Update your will, trusts, and other legal documents to reflect your new residency.
- Spend more than 183 days (the common threshold for statutory residency) in your new state, and generally avoid maintaining a permanent place of abode or strong ties in your old state.
Failing to properly establish domicile can lead to a dreaded residency audit, where your former state claims you still owe them taxes. Our guide on How to Change Your State Residency for Taxes goes into much greater detail, as does our article explaining the nuances of Domicile vs Statutory Residency.
A Comprehensive Financial Planning Approach
Ultimately, a truly tax-efficient retirement isn't just about avoiding income tax on Social Security and pensions. It's about optimizing your entire financial picture.
- Consider All Income Sources: Factor in all your retirement income streams—Social Security, pensions, 401(k) or IRA distributions, investment income, part-time work, rental income—and understand how each will be treated by your chosen state.
- Lifestyle and Spending Habits: Your personal spending will dictate how much impact sales tax has. Your housing preferences (renting vs. owning, property value) will determine your property tax burden.
- Healthcare Costs: While not a tax, healthcare is a massive retirement expense. Research healthcare costs and access in your potential new state.
- Consult Professionals: This is perhaps the most crucial advice. Tax laws are complex and change frequently. What's true for 2026 might shift in 2027. It's always best to consult with a qualified financial advisor or tax professional who specializes in retirement planning and multi-state taxation. They can help you create a personalized plan and evaluate the true Cost of Living vs Taxes by State for your unique situation. Tools from services like SmartAsset can give you a great starting point, but individual advice tailored to your specific assets and income is invaluable.
By taking a holistic and proactive approach, you can strategically choose a state that truly supports your financial well-being throughout your retirement years, allowing you to enjoy your golden years with less worry about your tax bill. To truly get a comprehensive overview, explore our How Each State Taxes Retirement Income (50-State Guide) and Most Tax-Friendly States for Retirees 2027.
States That Don't Tax Social Security or Pensions: At a Glance
To give you a quick reference point, here's a table summarizing the states that currently do not tax both Social Security and most qualified pension income. Remember, "no income tax" states inherently fit this criteria.
| State | State Income Tax? | Taxes Social Security? | Taxes Most Pensions? | Notes |
|---|---|---|---|---|
| Alaska | No | No | No | No state income tax or statewide sales tax. |
| Florida | No | No | No | A very popular retirement destination with no state income tax. |
| Illinois | Yes | No | No | Has a flat income tax, but fully exempts all qualified retirement income (SS, pensions, 401(k), IRA). |
| Mississippi | Yes | No | No | Taxes general income but provides full exemption for SS and most qualified retirement income. |
| Nevada | No | No | No | No state income tax. |
| New Hampshire | Yes (I&D only) | No | No | Taxes interest & dividends, but not earned income, Social Security, or pensions. I&D tax is phasing out by 2027. |
| Pennsylvania | Yes | No | No | Has a flat income tax but exempts most qualified retirement income (SS, pensions, 401(k), IRA withdrawals after age 59½). |
| South Dakota | No | No | No | No state income tax. |
| Tennessee | No | No | No | No state income tax on wages or investment income (I&D tax fully repealed). |
| Texas | No | No | No | No state income tax, but often higher property taxes. |
| Washington | No | No | No | No state income tax on wages. Note a capital gains tax exists but does not apply to SS or pensions. |
| Wyoming | No | No | No | No state income tax. |
Disclaimer
Please remember that tax laws are incredibly complex and can change frequently. This information is intended for general guidance only and should not be considered professional tax or financial advice. We strongly recommend consulting with a qualified tax advisor or financial planner to discuss your specific situation and to ensure you are making decisions based on the most current and accurate information.