States That Don’t Tax Pensions (2027)
Retirement is a time many of us look forward to, a chance to relax and enjoy the fruits of our labor. But the thought of state income taxes chipping away at your hard-earned pension can be a real headache, especially when you've planned diligently for years. Understanding which states are truly friendly to your pension income can make a monumental difference in your financial well-being during those golden years. This guide is here to shed light on the states that won't tax your pension in 2026, helping you navigate the complexities and make informed decisions about where to spend your retirement.
Understanding Pension Income and State Taxation
When we talk about pensions, we're usually referring to the income you receive from a defined-benefit plan, often provided by a former employer, union, or government entity. This steady stream of income is a cornerstone of many retirees' financial security, but how much of it you actually get to keep depends heavily on where you call home. States have vastly different approaches to taxing retirement income, and these differences can be substantial.
What Exactly Counts as a "Pension"?
It's easy to use the term "pension" broadly, but for tax purposes, it often refers specifically to distributions from a qualified defined-benefit plan. These are plans where your employer guarantees a specific payout amount upon retirement, usually based on your salary and years of service. Think of it as a traditional monthly check you receive after leaving your job.
However, many people also lump other forms of retirement income into this category, such as distributions from 401(k)s, 403(b)s, IRAs, and annuities. While these are all sources of retirement income, states can sometimes treat them differently. For the purpose of this discussion, when we say "pension," we're primarily focusing on those traditional defined-benefit plan payments. It's also worth noting that not all "pension-like" payments are taxable. For example, certain disability pensions or benefits related to specific military service might be exempt from taxation at both federal and state levels. Always verify the specific nature of your income and its taxability.
How Do States Typically Tax Retirement Income?
The way states handle retirement income, including pensions, varies dramatically across the country. There isn't a one-size-fits-all rule, which is why it can be so confusing! Generally, states fall into a few categories:
Some states have no income tax at all, so naturally, they won't tax your pension. This is the simplest scenario. Other states have a general income tax but choose to offer specific exemptions or deductions for retirement income, including pensions, to attract retirees. These exemptions might be full, meaning all pension income is untaxed, or partial, where only a certain amount or specific types of pensions are exempt. Finally, some states tax pension income just like any other form of income, often applying their standard income tax rates and brackets. This means your pension could be subject to progressive tax rates, where higher incomes are taxed at higher percentages, or a flat tax rate, where everyone pays the same percentage, regardless of income level. It’s also crucial to remember that some states, even if they exempt most pensions, might still tax certain types, like private pensions, while exempting public ones. It’s a patchwork system, making careful research essential for every retiree.
The States That Offer Full Pension Exemption (2026)
If you're dreaming of a retirement where your pension income isn't subject to state income tax, you have some excellent options across the U.S. These states either don't have a broad state income tax to begin with, or they've specifically legislated full exemptions for pension income, recognizing the value of attracting and retaining retirees.
No Income Tax States: The Easiest Wins
The most straightforward way to avoid state taxes on your pension is to live in a state that doesn't levy an income tax on its residents at all. In these states, your pension, along with most other forms of earned income, simply isn't a taxable event at the state level. This simplifies your tax planning significantly, as you don't have to worry about specific pension exemptions or deductions.
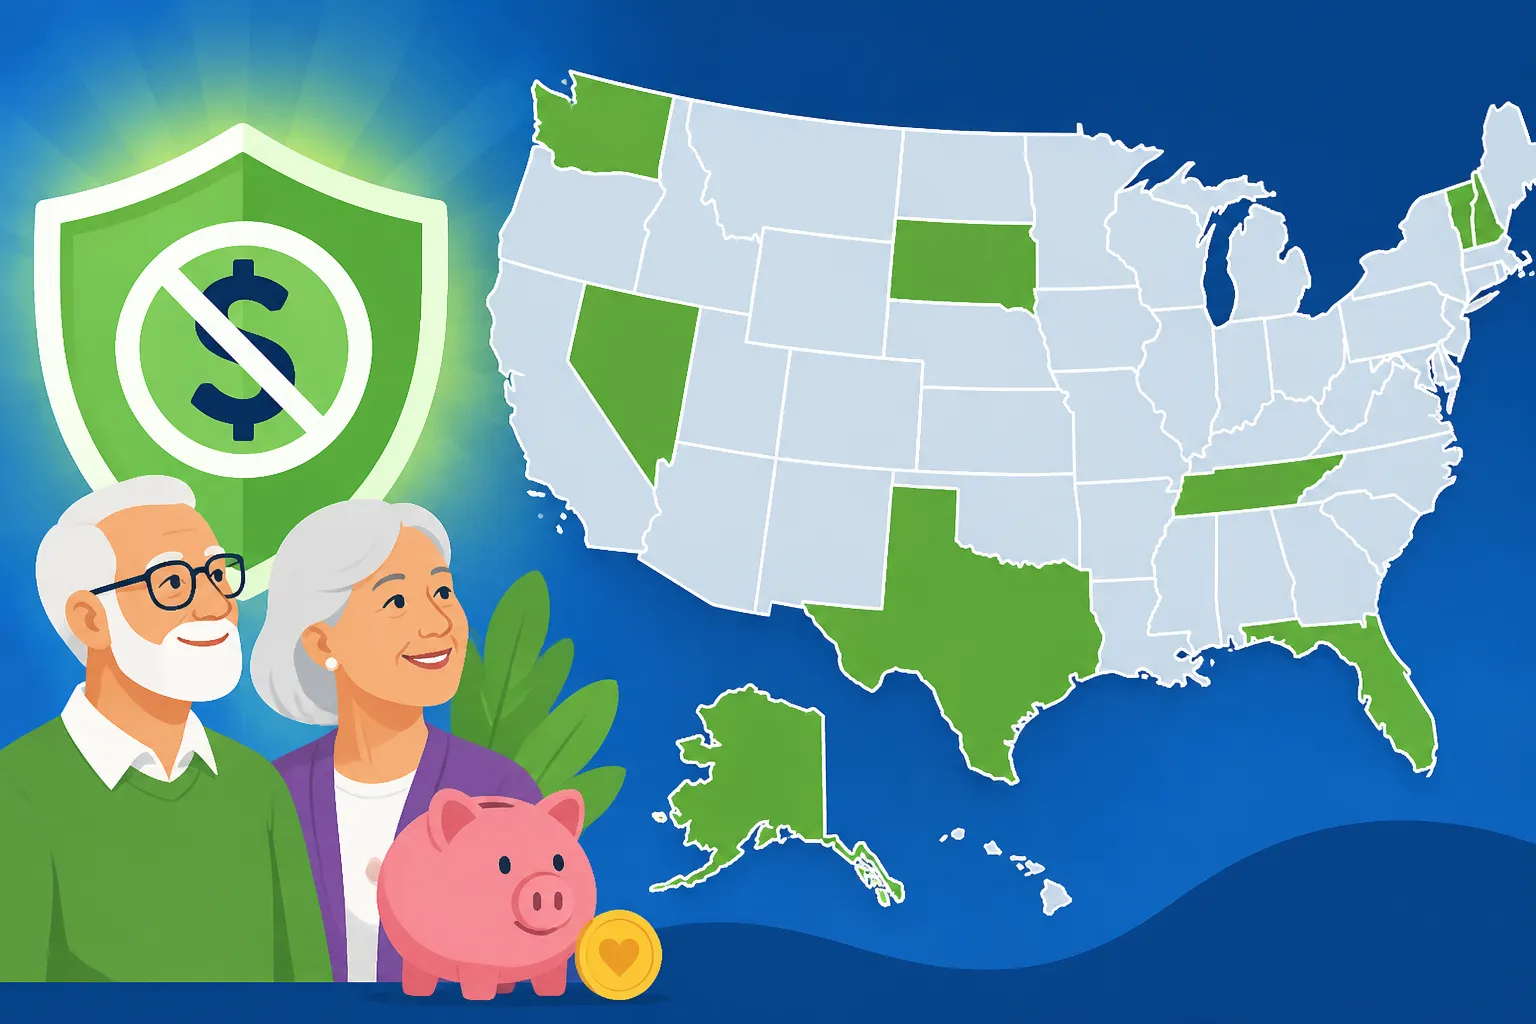
For 2026, the states that impose no broad state income tax are:
- Alaska: Known for its vast wilderness and oil wealth, Alaska residents enjoy no state income tax, sales tax, or inheritance tax. This means your pension income is entirely safe from state-level taxation.
- Florida: A perennial favorite for retirees, Florida boasts warm weather and no state income tax. This makes it a popular destination for those looking to maximize their retirement income. If you're considering a move, establishing How to Establish Florida Domicile is key.
- Nevada: With its desert landscapes and vibrant cities, Nevada also skips the state income tax, making it an attractive spot for many retirees.
- South Dakota: Often overlooked, South Dakota offers a peaceful environment with no state income tax, providing a tax-friendly home for your pension.
- Tennessee: Famous for its music and southern charm, Tennessee does not tax earned income. While it previously taxed interest and dividends, that tax has been fully phased out, meaning it's now a true no-income-tax state for most purposes. You can learn more about this in Does Tennessee Have State Income Tax?.
- Texas: The Lone Star State is another giant that offers no state income tax, making it a powerful magnet for retirees from higher-tax states. If you're curious about the full picture, check out Is Texas Really Tax Free? The Full Picture.
- Washington: In the Pacific Northwest, Washington also has no state income tax. While it recently introduced a capital gains tax, this typically doesn't impact traditional pension income. You can find more details on Does Washington Have State Income Tax?.
- Wyoming: The Cowboy State completes the list, offering beautiful scenery and no state income tax.
It's important to remember that while these states offer freedom from income tax, they often rely on other forms of taxation, like property taxes or sales taxes, to fund state and local services. So, always look at the full tax picture before making a move.
Income Tax States with Full Pension Exemptions
Beyond the states that don't have a general income tax, there are a select few that do have a state income tax but offer a complete exemption for all pension income. This is a crucial distinction, as it means you'll still file a state income tax return, but your pension payments won't be included in your taxable income calculation. These states are particularly attractive if you appreciate other aspects of living there and have substantial pension income.
For 2026, the primary states known for offering this full pension income exemption are:
- Illinois: The Land of Lincoln has a flat income tax rate, but it stands out by explicitly exempting all retirement income, including income from qualified employee pension plans, IRAs, and 401(k)s, from state income tax. This is a significant boon for retirees in Illinois, allowing them to keep more of their pension payouts.
- Mississippi: Down in the Magnolia State, Mississippi also provides a full exemption for all retirement income, including public and private pensions, annuities, and IRA/401(k) distributions. This comprehensive exemption makes Mississippi a very tax-friendly state for many retirees living on a pension.
- Pennsylvania: The Keystone State is another fantastic option for pensioned retirees. Pennsylvania completely exempts all eligible retirement income, including payments from retirement plans such as pensions, 401(k)s, and IRAs, provided the taxpayer meets certain age or disability requirements and the plan has been in place for a certain period. This long-standing policy makes Pennsylvania incredibly attractive to those with significant pension income, even though the state has an income tax.
These states demonstrate that even if a state has an income tax, it can still be exceptionally friendly to your retirement income, especially if a large portion comes from a pension. Always check the specific eligibility requirements, as tax laws can evolve, but these three have historically been steadfast in their full pension exemptions.
States with Partial Pension Exemptions or Special Rules
While some states offer complete exemption from pension taxes, many others take a more nuanced approach. They might tax some pension income while exempting others, or offer exemptions based on age, income level, or the type of pension you receive. This requires a bit more digging but can still result in significant tax savings for retirees.
Age-Based and Income-Based Exemptions
Many states understand that retirees often live on fixed incomes and offer some relief through age-based or income-based exemptions. These rules aim to protect lower and middle-income retirees from bearing a heavy tax burden on their pensions.
For example, a common approach is to allow taxpayers over a certain age, often 65, to subtract a portion of their retirement income from their taxable income. This isn't a full exemption, but it significantly reduces the amount of pension income subject to state tax. Colorado is a prime example, offering a substantial retirement income subtraction that varies by age. For those 65 or older, a larger amount of qualifying pension and annuity income can be excluded from state taxable income. Similarly, states like Georgia offer a generous exclusion for retirement income once you reach a certain age, typically 62 or 65, up to a specified dollar limit (for example, a significant exclusion for individuals 65 and older). New Jersey also allows for a sizable exclusion of pension and annuity income, which is particularly beneficial for lower and middle-income retirees, with the exclusion amount often increasing for those above a certain income threshold. These exemptions can be a lifesaver, but they often come with income limits, meaning if your total income exceeds a certain threshold, the exemption might be reduced or phased out entirely. It’s always critical to understand these specific limits, which can be found in a resource like Retirement Income Exclusions by State.
Type of Pension Exemptions: Military, Government, Private
Beyond age and income, the source or type of your pension can also dictate its taxability in many states. This is where things can get a bit more intricate, as states often prioritize certain groups for tax relief.
A widespread exemption across the U.S. is for military retirement pay. Most states offer some level of exemption for military pensions, with many providing a full exemption. This is a way for states to honor veterans and attract retired military personnel. For instance, states like North Carolina, South Carolina, and Virginia, all popular with military retirees, offer full or significant exemptions for military retirement income. You can dive deeper into this topic by exploring States That Don't Tax Military Retirement. Similarly, public employee pensions (from state or local government jobs) often receive more favorable tax treatment than private sector pensions in many states. Some states fully exempt public pensions but tax private pensions, while others may offer a larger exclusion for public pensions. This distinction is important for those who have spent their careers in public service. For example, Ohio, while it generally taxes pensions, provides a credit for certain retirement income and more favorable treatment for public pensions. Lastly, private pensions, which are typically defined-benefit plans from non-government employers, are the most commonly taxed. If a state doesn't offer a general retirement income exemption, private pensions are usually subject to the standard state income tax rates.
Tax Credits and Deductions in Lieu of Exemptions
Sometimes, a state might not offer a direct exemption for your pension income but will provide other tax breaks that can effectively reduce your tax burden. These often come in the form of tax credits or deductions.
A tax credit directly reduces the amount of tax you owe, dollar for dollar, which can be incredibly valuable. A deduction, on the other hand, reduces your taxable income, which then reduces your overall tax liability. While less common for direct pension income specifically, some states might have general credits for seniors or retirement income that indirectly benefit pension recipients. For instance, some states offer tax credits for property taxes paid by seniors, which can free up more of your pension income for other expenses. Another example might be a specific deduction for medical expenses or long-term care, which disproportionately benefits older adults and effectively lowers their overall taxable income, even if the pension itself isn't directly exempt. It's crucial to explore all available credits and deductions when planning your retirement taxes, as these can collectively make a state more tax-friendly than it initially appears. Tools from financial analysis platforms like SmartAsset can often help model these scenarios to see the net impact on your retirement finances.
Key Factors Beyond Pension Tax to Consider for Retirement
Focusing solely on whether a state taxes your pension, while incredibly important, is only one piece of the puzzle. A truly tax-smart retirement plan requires a holistic view of all your income sources, expenses, and the broader tax landscape of a potential new home. What you save on income tax might be offset by other costs if you're not careful.
Holistic View: Beyond Just Pensions
It's a common mistake to chase a "no income tax" state without fully understanding how other forms of taxation will impact your financial situation. Your pension is likely just one component of your retirement income. Many retirees also rely on Social Security benefits, distributions from 401(k)s and IRAs, and potentially income from investments or part-time work.
You need to ask: Does the state tax Social Security? What about your 401(k) or IRA withdrawals? Some states that are very friendly to pensions might still tax other retirement accounts, or vice-versa. For a comprehensive overview, checking out How Each State Taxes Retirement Income (50-State Guide) can be incredibly helpful. Then there are property taxes. States with no income tax often have higher property taxes to compensate for lost revenue. For instance, while Texas has no income tax, its property taxes are among the highest in the nation. Conversely, states like New Hampshire, while not taxing earned income, have high property taxes. Sales taxes are another significant factor; you'll pay these on almost everything you buy, from groceries to larger purchases. High sales taxes can quickly erode the savings from not paying income tax. Finally, don't overlook estate and inheritance taxes, which can impact your beneficiaries if you plan to leave a legacy.
Overall Tax Burden and Cost of Living
Beyond specific tax types, it's vital to consider the overall tax burden of a state and, crucially, the cost of living. A state might have incredibly low income taxes, but if property values are sky-high, sales taxes are hefty, and utility costs are exorbitant, you might end up spending more overall than in a state with a moderate income tax.
The actual cost of living includes everything from housing (rent or mortgage, property taxes, insurance) to groceries, transportation, healthcare, and entertainment. A state like Hawaii, for example, might offer some tax breaks for seniors, but its cost of living, particularly for housing, is among the highest in the nation. On the other hand, a state like Alabama might have a moderate income tax, but its overall cost of living and property taxes are significantly lower, potentially making your retirement dollars stretch further. Financial tools from reputable sites like SmartAsset often provide comparisons of the overall tax burden and cost of living by state, giving you a more realistic picture. It's often more beneficial to live in a state where your entire budget, not just your tax liability, is optimized. Consider diving into articles like State Tax Burden by State 2026 and Cost of Living vs Taxes by State to get a clearer understanding of these dynamics.
Navigating Residency: How to Make a Tax-Smart Move
Deciding where to retire is a monumental decision, and if you’re moving states specifically to take advantage of favorable tax laws for your pension, understanding and properly executing a change in residency is paramount. States, especially those losing high-net-worth individuals, can be quite aggressive in challenging residency claims. Getting this wrong could lead to paying taxes in two states, which is exactly what you’re trying to avoid!
Establishing Domicile vs. Statutory Residency
This is arguably the most critical distinction to grasp when planning a move for tax purposes. Many people assume that simply spending less than 183 days in their old state automatically severs their tax ties. Unfortunately, it's rarely that simple.
Your domicile is your true, fixed, and permanent home – the place where you intend to return whenever you are absent. It's about your intent. This is the hardest thing to change because it requires demonstrating a genuine shift in your life. States will look for a preponderance of evidence to prove you’ve truly abandoned your old domicile and established a new one. On the other hand, statutory residency is often determined by the number of days you spend in a state, combined with maintaining a "permanent place of abode" there. Even if your domicile is elsewhere, if you meet a state’s statutory residency tests (e.g., spending more than 183 days in a state and having a place available for your use), that state can still tax you as a resident. This is particularly relevant for "snowbirds" who spend winters in a warm state and summers elsewhere. For a deeper understanding, check out Domicile vs Statutory Residency. States like New York and California are notorious for their aggressive residency audits, making it crucial to understand the nuances. The 183-day rule, while common, is not a magic bullet; it's one factor among many.
Practical Steps for Changing State Residency
Changing your state residency for tax purposes isn't just about packing boxes; it's about meticulously severing ties with your old state and establishing new ones with your chosen retirement haven. This process needs to be intentional and well-documented to withstand potential scrutiny from tax authorities.
Here are concrete steps you should take:
- Change Your Driver's License and Vehicle Registration: This is a foundational step. Do this as soon as possible after moving to your new state.
- Register to Vote: Register in your new state and cancel your registration in the old one. This is a clear indicator of intent.
- Update Bank Accounts and Mailing Address: Move your primary checking and savings accounts to banks in your new state, and ensure all important mail, including financial statements, goes to your new address.
- Change Healthcare Providers: Establish relationships with doctors, dentists, and other healthcare professionals in your new state.
- Relocate Valuables and Sentimental Items: Move significant personal property, such as artwork, family heirlooms, and important documents, to your new home.
- Update Estate Planning Documents: Revise your will, trusts, and power of attorney to reflect your new state's laws and your new domicile.
- Join Local Organizations: Become involved in clubs, churches, and community groups in your new state. This helps demonstrate your social ties.
- Spend Time: While not the only factor, make sure you physically spend the majority of your time (more than The 183-Day Rule for State Taxes) in your new state and significantly less in your old state. Keep a detailed log of your travel.
- Sell or Lease Your Old Home (if applicable): If you retain your old home, it can be a strong tie to the old state. Selling it or demonstrably making it unavailable for your use strengthens your residency claim in the new state.
The more evidence you have that you've truly "moved your life" to the new state, the stronger your case will be. It's about building a consistent narrative of intent. Consulting with a tax professional experienced in multi-state residency rules is highly recommended, especially if you're moving from a state known for aggressive audits. You can find more comprehensive guidance in resources like How to Change Your State Residency for Taxes.
Planning Your Retirement: Tools and Resources
Retirement planning is a marathon, not a sprint, and optimizing your tax situation, especially concerning your pension, is a critical part of the long-term strategy. You don't have to navigate this complex landscape alone; there's a wealth of expertise and tools available to help you make the best decisions for your financial future.
The Importance of Comprehensive Financial Planning
While this guide focuses on pension taxation, a truly effective retirement plan encompasses all aspects of your financial life. You need to consider not just your pension, but also your Social Security benefits, distributions from 401(k)s, IRAs, other investment income, and any potential part-time earnings. Each of these income streams can be taxed differently at the state level, creating a unique challenge that demands a holistic approach.
Working with a qualified financial advisor who specializes in retirement planning and tax optimization can be invaluable. They can help you model different scenarios, taking into account your specific income sources, assets, and spending habits, to determine the most tax-efficient state for your retirement. They'll look at your entire financial picture, helping you understand how various state tax laws interact with your personal circumstances. This isn't just about saving money in the short term; it's about crafting a sustainable financial strategy that maximizes your wealth throughout your retirement years. They can also provide insights into things like Required Minimum Distributions (RMDs) and how they are taxed by states, which is something many retirees overlook.
Leveraging Online Tools and Tax Professionals
In today's digital age, there are many excellent online tools that can help you get a clearer picture of your retirement tax situation in different states. Websites like SmartAsset, for instance, offer tax calculators and guides that allow you to compare tax burdens, including how states treat pensions and other retirement income, side-by-side. These tools can provide a good starting point for your research, allowing you to quickly filter down to states that align with your tax preferences.
However, online tools are general in nature and cannot account for all your unique circumstances. That's where a tax professional, such as a Certified Public Accountant (CPA) or an enrolled agent, becomes indispensable. If you're planning a multi-state move, especially from a state known for its stringent residency rules like California or New York, hiring a professional who specializes in multi-state taxation and residency issues is highly recommended. They can guide you through the intricate process of establishing domicile, ensuring you have all the necessary documentation to support your claim, and help you file your final returns in your previous state and your first returns in your new one correctly. Don't underestimate the complexity of state tax laws; a small investment in professional advice can save you significant money and headaches down the road.
Common Misconceptions and Pitfalls
When planning for retirement and considering a move to a state with favorable pension tax laws, it's easy to fall prey to common misconceptions. The tax landscape is complex, and focusing on just one aspect, like pension tax, without considering the broader picture can lead to unexpected financial surprises down the road.
The "No Income Tax" Trap
One of the biggest pitfalls retirees encounter is assuming that a state with "no income tax" is automatically the most tax-friendly. While these states certainly don't tax your pension income, they have to generate revenue somehow, and they often do so through other, sometimes higher, taxes.
For example, while Florida and Texas have no state income tax, they often have higher-than-average property taxes. If you own a substantial home, your annual property tax bill could easily outweigh any income tax savings you would have realized in a state with a moderate income tax but lower property taxes. Similarly, states without an income tax might rely more heavily on sales taxes, which can significantly impact your daily spending, especially on larger purchases. If you're moving from a state like California, which has a high income tax but lower property taxes in many areas, to a state like Texas, you might find your property tax bill jumps considerably. This is why looking at the "tax burden" or State Tax Burden by State 2026 as a whole, rather than just one component, is so crucial. A state's overall tax friendliness depends heavily on your specific income mix, spending habits, and asset profile.
Forgetting About Local Taxes
Another overlooked aspect is the impact of local taxes. Even if your state doesn't tax pensions, your city or county might have its own taxes that could impact your retirement income or property. These local levies can sometimes add a surprising amount to your annual tax burden.
Many states, such as Pennsylvania (which exempts pensions at the state level), still allow local municipalities to levy their own earned income taxes or "local services taxes" on residents. While pension income is often exempt from these local income taxes as well, it's not universally true, and you need to verify the specific rules for your chosen city or county. Beyond local income taxes, property taxes are almost always levied at the local level (county, city, school district). These rates can vary dramatically even within the same state. For example, in Michigan, while the state has some retirement income exemptions, the property tax rates can vary widely by township and school district. Sales taxes, too, can have local add-ons. Overlooking these hyper-local taxes can lead to budgeting surprises. Always investigate the full local tax structure of a specific town or county before making a final decision.
| Category | States (Examples) | Key Tax Feature for Pensions |
|---|---|---|
| No State Income Tax | Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, Wyoming | No state income tax means no tax on pensions (or any other income). |
| Income Tax, Full Pension Exemption | Illinois, Mississippi, Pennsylvania | These states have a state income tax but explicitly exempt all qualified pension income. |
| Partial Pension Exemptions | Colorado, Georgia, New Jersey, Michigan, Ohio | May offer age-based or income-based exclusions/subtractions, or exemptions for specific types of pensions (e.g., military, public employee). |
| Generally Tax Pensions | California, Massachusetts, New York, Virginia | Tax pensions as ordinary income, though some minor deductions or credits might apply for certain situations. |
Note: This table provides general guidance and specific rules can vary. Always consult current state tax codes or a tax professional for precise information for your situation.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, tax, or legal advice. Tax laws are complex and subject to change by state legislatures. You should consult with a qualified financial advisor or tax professional to discuss your specific circumstances and to ensure compliance with all applicable tax laws and regulations for 2026 and beyond. We are not liable for any actions taken based on the information provided herein.