How Many States Tax Social Security in 2026?
Navigating the complexities of state income tax in retirement can feel like a daunting puzzle, especially when it comes to understanding if your hard-earned Social Security benefits will be taxed. Many retirees face anxiety over unexpected tax bills, unsure whether their state is one of the few that still levies a tax on these crucial benefits. This comprehensive guide aims to clear up that confusion, providing a definitive list of states that tax Social Security and offering insights into their specific rules.
Understanding How State Income Tax Impacts Social Security
It's a common misconception that once you're receiving Social Security, your benefits are entirely tax-free. While many states align with the federal approach, the truth is a bit more nuanced. For retirees, this often means delving into state-specific regulations that can significantly impact their financial well-being. The variations from one state to the next can be substantial, making careful planning essential.
The Federal Picture vs. State Variations
First, let's quickly touch on the federal side. The IRS can tax a portion of your Social Security benefits if your "combined income" (your adjusted gross income, plus any non-taxable interest, plus half of your Social Security benefits) exceeds certain thresholds. For 2026, these thresholds are likely to remain around $25,000 for individuals and $32,000 for those filing jointly. If your income is above these amounts, up to 85% of your Social Security benefits could be subject to federal income tax. This federal taxation is a baseline, but states have the autonomy to decide if they will follow suit, partially tax, or completely exempt these benefits.
The significant divergence comes at the state level. While a vast majority of states fully exempt Social Security benefits from state income tax, a handful choose to tax them to varying degrees. This creates a patchwork of rules that can be incredibly confusing, especially for those who move frequently or are considering relocating for retirement. What might be tax-free in one state could become a taxable event in another, altering your effective retirement income. Understanding these distinctions is crucial for smart financial planning, ensuring you're not caught off guard by an unexpected tax bill when every dollar counts.
Why Some States Tax Social Security
States impose taxes on Social Security benefits for a variety of reasons, primarily to generate revenue for state services. Unlike the federal government, which relies heavily on income tax, states often have a mix of revenue sources, including property taxes, sales taxes, and income taxes. For those states that do tax Social Security, it's typically part of a broader income tax structure. These states often have different motivations, ranging from maintaining overall fiscal health to specific budget requirements.
The ways in which states tax Social Security can also differ significantly. Some states may mirror the federal rules, using similar income thresholds to determine taxability. Others might have their own unique set of exemptions, deductions, or varying income limits. For instance, a state might offer a full exemption if a retiree's income falls below a certain level, or it might tax a flat percentage of benefits regardless of income, though this is less common. These nuances mean that simply knowing if a state taxes Social Security isn't enough; you need to understand how it taxes them to assess the true impact on your retirement income. It's not a one-size-fits-all situation, and delving into the specifics is key to navigating the landscape.
The Definitive List: States That Tax Social Security
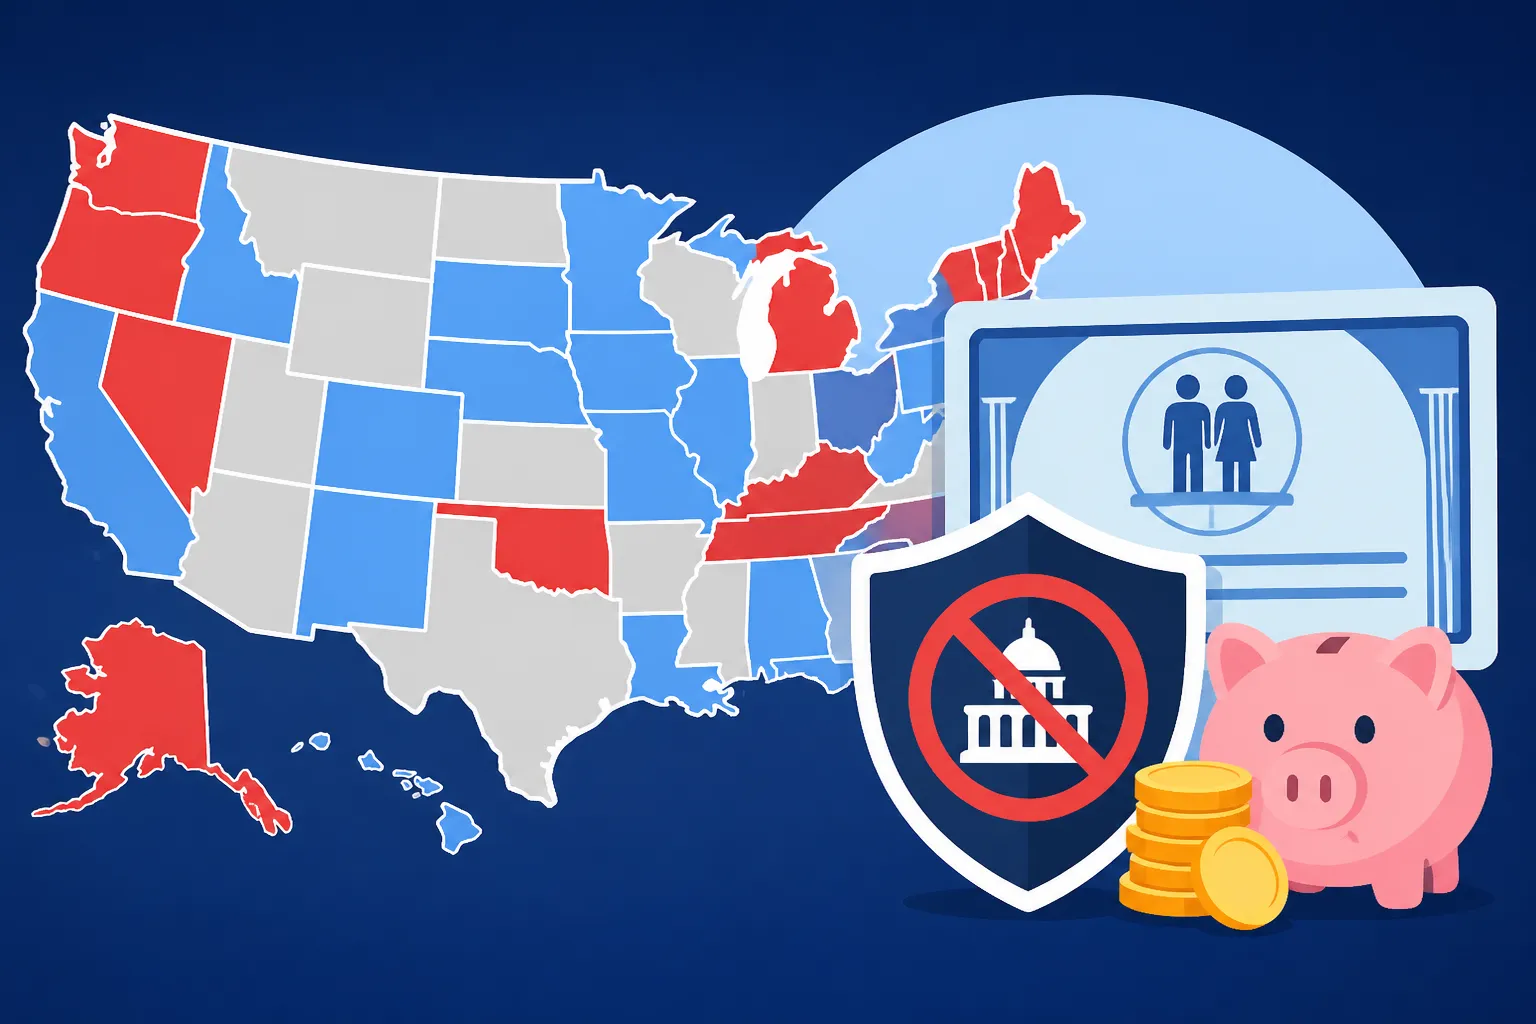
When planning your retirement, one of the most pressing questions is often about the tax burden, especially concerning your Social Security benefits. The good news is that most states will not tax your Social Security income. However, a select few still do, and it's essential to know who they are and how they approach it. As of current projections and legislative trends, there are generally eight states that tax Social Security benefits.
This number has actually decreased in recent years, which is a positive trend for retirees! States like Missouri, Iowa, Nebraska, and Kansas have all either fully repealed or significantly phased out their Social Security income taxes, making them more attractive for retirees. However, the remaining states on this list have specific rules that could affect your benefits.
A Closer Look at Each Taxing State
Let's dive into the specifics of the states that are expected to tax Social Security benefits in 2026:
- Colorado: This state allows a subtraction for pension and annuity income, which includes Social Security benefits, for taxpayers age 65 and older. The amount of the subtraction depends on your age and income. For those under 65, benefits are generally taxed if they're subject to federal tax. This can make how Colorado taxes retirement income a bit tricky to navigate.
- Connecticut: Connecticut taxes Social Security benefits for individuals whose federal adjusted gross income (AGI) exceeds certain thresholds. For the 2026 tax year, the income thresholds are generally expected to be around $75,000 for single filers and $100,000 for those filing jointly. If your AGI is below these amounts, your Social Security benefits are exempt.
- Minnesota: Minnesota aligns with federal taxability rules but also has its own subtraction for Social Security income. The amount of the subtraction depends on your income, age, and filing status. If your income exceeds specific thresholds, a portion of your Social Security benefits will be subject to state income tax.
- Montana: Montana also taxes Social Security benefits if your federal AGI exceeds certain thresholds, similar to the federal rules. While there is a standard exemption, most retirees with higher incomes will find a portion of their benefits subject to state tax.
- New Mexico: This state taxes Social Security benefits based on AGI. However, New Mexico does offer an exemption for low to middle-income taxpayers, which can significantly reduce or eliminate the state tax on Social Security for many retirees. The specific exemption amount and AGI limits vary and are adjusted periodically.
- Rhode Island: Similar to Connecticut, Rhode Island taxes Social Security benefits for individuals whose federal AGI exceeds certain thresholds. For 2026, these thresholds are projected to be around $95,800 for single filers and $119,750 for those filing jointly. If your income is below these amounts, your benefits are exempt.
- Utah: Utah allows a credit for Social Security benefits for taxpayers whose modified adjusted gross income (MAGI) is below a certain amount. If your income exceeds this threshold, your Social Security benefits will be taxed, subject to the credit. The credit amount helps to offset the tax for many.
- Vermont: Vermont fully taxes Social Security benefits if your adjusted gross income exceeds certain thresholds, mirroring the federal taxability rules quite closely. There are no state-specific subtractions or exemptions, making it one of the less tax-friendly states for Social Security if your income is above the federal thresholds.
Here’s a quick summary table for clarity:
| State | Taxes Social Security Benefits | How It Works (Briefly) |
|---|---|---|
| Colorado | Yes | Subtraction for pension/annuity income (including SS) based on age and income. |
| Connecticut | Yes | Taxed if federal AGI exceeds state-specific thresholds ($75k single/$100k joint est.). |
| Minnesota | Yes | State subtraction based on income, age, and filing status; parallels federal rules. |
| Montana | Yes | Taxed if federal AGI exceeds certain thresholds; similar to federal taxability. |
| New Mexico | Yes | Taxed based on AGI, with an exemption for low to middle-income taxpayers. |
| Rhode Island | Yes | Taxed if federal AGI exceeds state-specific thresholds ($95.8k single/$119.75k joint est.). |
| Utah | Yes | Credit allowed for SS benefits if MAGI is below a certain threshold. |
| Vermont | Yes | Fully taxes SS benefits if AGI exceeds federal thresholds; no state-specific exemptions. |
The States That Have Recently Repealed or Phased Out Taxes
It's worth noting that the landscape for taxing Social Security benefits is constantly evolving. In recent years, several states have either completely repealed their state income tax on Social Security benefits or are in the process of phasing them out. This is a significant trend for retirees looking to maximize their income.
For example, Missouri fully repealed its state income tax on Social Security benefits for tax years beginning on or after January 1, 2024. Similarly, Iowa has eliminated its tax on retirement income, including Social Security, for those 55 and older. Nebraska also completed its phase-out for Social Security income tax for the 2024 tax year and beyond. Kansas has also repealed its state income tax on Social Security benefits effective for tax year 2024, removing income thresholds that previously made benefits taxable for many.
Even West Virginia, which was once on this list, completed its phase-out of taxes on Social Security benefits for the 2022 tax year, meaning it does not tax them in 2026. This trend demonstrates a growing awareness among state legislatures to make their states more attractive for retirees, potentially leading to further changes in the future. If you're looking into States That Don't Tax Social Security (2026), you'll find a much longer list now than just a few years ago.
How These States Tax Social Security Benefits
Understanding that a state taxes Social Security is only half the battle. The real trick is knowing the specific mechanisms they employ, as this directly impacts how much of your hard-earned benefits you'll actually keep. It's not always a flat tax, and it's rarely simple. Each state on our list has its own set of rules, often involving complex calculations based on income levels and other factors.
Retirees often turn to financial resources like SmartAsset for tools and calculators that help them understand these nuances, providing estimates based on their specific situation. These tools can be incredibly helpful in projecting your tax liability and making informed decisions about where to spend your retirement years. It's not just about the tax rate; it's about the entire framework of how your income is assessed.
Income Thresholds and Exemptions
The most common approach for states that tax Social Security is through the use of income thresholds. Much like the federal government, these states determine taxability by looking at your total income, or a modified version of it, to see if it exceeds a certain dollar amount. If your income falls below these thresholds, your Social Security benefits might be partially or fully exempt from state tax.
For instance, in a state like Connecticut, if your federal AGI is below $75,000 for single filers or $100,000 for joint filers (estimated for 2026), your Social Security benefits are completely off the hook for state taxes. Exceed those amounts, and a portion becomes taxable. Other states, such as New Mexico, offer income-based exemptions that can reduce the taxable amount. These exemptions are often age-based too, meaning older retirees might qualify for higher exclusions. It's essential to check the precise thresholds and available exemptions for each specific state, as these figures are regularly adjusted and can be quite granular depending on your filing status and overall income. This is why a simple "yes" or "no" answer to "Does my state tax Social Security?" isn't sufficient for true financial planning.
Impact on Retirement Planning
The decision by some states to tax Social Security benefits has a tangible impact on retirement planning. For retirees living on a fixed income, even a small amount of additional tax can strain a budget. It's not just about the state income tax on Social Security itself; it's about how it interacts with other taxes, like property taxes, sales taxes, and How Each State Taxes Retirement Income (50-State Guide) in general. This comprehensive view is critical for painting an accurate picture of your financial future.
Many retirees consider moving to a state with a more favorable tax environment as they approach or enter retirement. For some, moving to one of the States With No Income Tax (2026 Full List) or a state that explicitly exempts all retirement income, including Social Security and pensions, can be a game-changer. This strategic relocation can potentially save thousands of dollars over the course of retirement. Financial tools from providers like SmartAsset can help individuals compare the overall tax burden across different states, including how Social Security is taxed, helping them choose the Most Tax-Friendly States for Retirees 2027. Ignoring these state-level taxes can lead to unexpected financial pressure, which is the last thing anyone wants in their golden years.
Strategies for Minimizing State Social Security Taxes
While it might seem like you have little control over state tax laws, there are indeed strategies you can employ to minimize the impact of state taxation on your Social Security benefits, especially if you live in one of the eight states that still tax them. Proactive planning and a deep understanding of the rules are your best defenses. Thinking strategically about your residency, income sources, and even the timing of certain financial decisions can make a considerable difference in your retirement bottom line.
Understanding Your State's Rules
The first and most crucial step is to gain a thorough understanding of your specific state's rules regarding Social Security taxation. As we've discussed, even among the states that tax these benefits, the methods and thresholds vary significantly. Simply knowing your state is on the "taxing list" isn't enough; you need to dig into the details. Look for information on specific income thresholds that trigger taxation, any age-based exemptions, or unique credits that might reduce your tax liability.
Your state's Department of Revenue or taxation website is often the best official resource for the most up-to-date information. They typically publish detailed guides and forms for retirees. If you find the legal jargon overwhelming, consider consulting a local tax professional who specializes in retirement taxes. They can help you navigate the nuances, especially concerning Retirement Income Exclusions by State that might apply to you. This individualized advice is invaluable, as a generic online article, while informative, can't account for every personal circumstance.
Residency Considerations and Financial Planning
One of the most impactful strategies for minimizing state Social Security taxes, particularly for those with higher incomes, is to consider residency in a state that doesn't tax these benefits at all. There are many states, including Florida, Texas, and Washington, that have no state income tax, which automatically means no tax on Social Security. Even among states with an income tax, most offer full exemptions for Social Security benefits, making them more attractive for retirees. This falls under the broader umbrella of Moving to a Tax-Friendly State for Retirement.
Beyond relocation, strategic financial planning within your current state can also help. If your state uses income thresholds to determine taxability, you might be able to manage other sources of retirement income (like 401(k) or IRA distributions, or even part-time work) to keep your overall AGI below the threshold. This might involve converting traditional IRA funds to Roth IRAs in lower-income years, or carefully timing significant withdrawals. Tools provided by financial analysis platforms like SmartAsset can help model these scenarios, showing you how different income strategies might affect your state tax liability on Social Security. Understanding How to Minimize State Taxes in Retirement requires a holistic approach to all your income streams, not just Social Security. For more detailed insights into various retirement income streams, you might want to read about States That Don't Tax Pensions (2026) or States That Don't Tax 401(k) & IRA Withdrawals.
Disclaimer
Please remember that tax laws are complex and subject to change. The information provided in this guide is for general informational purposes only and does not constitute professional tax advice. Always consult with a qualified tax advisor or financial planner to discuss your specific tax situation and ensure compliance with current state and federal regulations.