Do Teachers Pay State Tax on Their Pension?
It's incredibly frustrating trying to figure out how your hard-earned pension will be taxed, especially after years dedicated to teaching. Many teachers assume their public service pensions are entirely exempt from state income tax, but the reality is far more complex and varies wildly from state to state. This guide will walk you through the nitty-gritty of how teacher pensions are generally taxed across the United States, helping you understand what to expect as you plan for retirement.
Understanding State Taxation of Teacher Pensions
When it comes to retirement income, including pensions for public school teachers, states have a bewildering array of rules. Some states offer full exemptions, while others treat these pensions like any other form of income, and still others fall somewhere in the middle with partial exclusions or deductions. It's not a one-size-fits-all scenario, which is why planning ahead is crucial for educators.
General Rules for Retirement Income
Generally speaking, almost all income you receive in retirement is considered taxable by the federal government, with specific rules for Social Security benefits. However, state taxation is a different beast entirely. Some states, famously, don't tax income at all, while others have very generous provisions for retirement income, aiming to attract or retain retirees. The key often lies in whether a state has a broad income tax, and then whether it carves out specific exemptions for certain types of retirement income, such as public pensions. Many teachers might wonder, "Do I pay state tax on pension income?" and the answer really depends on where they taught and where they choose to live in retirement.
It's common for states to differentiate between different types of retirement income. For instance, a state might fully exempt public employee pensions, but tax private pensions, 401(k) withdrawals, or IRA distributions. This can be a huge advantage for teachers who typically rely on defined benefit plans from their state's public employee retirement system. These systems, like the California State Teachers' Retirement System (CalSTRS) or the New York State Teachers' Retirement System (NYSTRS), provide a predictable income stream, and knowing how it's taxed at the state level is essential for financial planning.
Why Teacher Pensions Can Be Different
Teacher pensions often receive special consideration at the state level because they are derived from public employment. State and local governments have a vested interest in attracting and retaining qualified educators, and offering tax-friendly retirement benefits can be a powerful incentive. These exemptions can act as a deferred compensation, making a state more appealing for teachers considering their long-term financial security.
However, the specific structure of these exemptions can vary significantly. Some states might offer a complete exclusion of all public pension income. Others might allow you to exclude a certain dollar amount of your pension income, or the exclusion might be tied to your age or total adjusted gross income. For instance, a state might say that the first $20,000 of pension income is exempt, or that if you're over 65, you can exclude up to $X amount. These nuances mean that two teachers with identical pensions in different states could face vastly different state tax bills. It's always wise to delve into the specifics of your state's tax code or consult with a financial advisor to fully understand your situation.
States That Are Most Tax-Friendly for Teacher Pensions
When we talk about "tax-friendly" for teacher pensions, we're really looking at a spectrum. Some states don't have an income tax at all, making them inherently friendly. Others have an income tax but specifically exempt public pensions, and some offer substantial deductions or credits.
States With No State Income Tax
The most straightforward answer to "Do teachers pay state tax on their pension?" for many is a resounding "no" if they reside in one of the states without a broad state income tax. In these states, your teacher pension, along with most other forms of earned income, is simply not subject to state income tax. This means more of your hard-earned retirement dollars stay in your pocket.
Currently, there are nine states that do not impose a state income tax: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming. While Tennessee and New Hampshire historically taxed interest and dividends, they've been phasing those out. For teachers, this means a significant tax break compared to their counterparts in high-tax states. For example, a teacher retiring to Florida from a state like New York would likely see a substantial increase in their net pension income, as Florida does not tax any retirement income. This is a big reason why many retirees consider moving to a state with no income tax. If you're pondering a move, it's worth exploring if Is Florida Tax Friendly for Workers? or Is Texas Really Tax Free? The Full Picture aligns with your retirement goals.
States That Fully Exempt Teacher Pensions
Beyond the no-income-tax states, several other states with a general income tax make specific provisions to fully exempt public employee pensions, including those for teachers. This is a massive benefit for educators who have dedicated their careers to public service.
For instance, Illinois is well-known for fully exempting all retirement income, including teacher pensions, from state income tax. Pennsylvania also offers a full exemption for qualifying retirement income. Mississippi provides a full exemption for all public and private pension income. Even if you're not in one of the nine no-income-tax states, these full exemptions can make a particular state incredibly appealing for retired teachers. It’s definitely worth looking into the specific rules for States That Don't Tax Pensions (2027) if you're evaluating your options. This kind of full exemption means that your monthly pension check from your state's teacher retirement system won't see a dime taken out for state income tax. It's a significant financial advantage that can greatly enhance your quality of life in retirement.
States with Partial Exemptions or Deductions
Then you have the states that offer partial relief. These states might not give a full exemption, but they provide significant deductions or exclusions that can considerably reduce a teacher's state tax burden on their pension. This middle ground is where many states find themselves, trying to balance revenue needs with retiree incentives.
Consider states like New Jersey, which has an income exclusion for retirement income for those meeting certain income thresholds. Or Colorado, which offers a retirement income subtraction for seniors. Georgia provides a substantial exclusion for retirement income (up to $65,000 per person in 2026) for taxpayers aged 65 and older. These aren't full exemptions, but they can still amount to thousands of dollars in annual tax savings. It's not uncommon for these partial exemptions to be age-based, encouraging retirees to stay within the state. For example, a teacher in Michigan might benefit from the state's pension subtraction if they are over a certain age. These rules are part of the broader conversation about Retirement Income Exclusions by State and can make a big difference in how much discretionary income you have. Financial tools from companies like SmartAsset can often help individuals compare these specific state-level deductions to better plan their retirement finances.
States Where Teacher Pensions May Be Fully Taxed
While many states offer tax breaks for teacher pensions, it's a mistake to assume all do. In some states, teacher pensions are treated much like any other source of income, meaning they are fully taxable under the state's general income tax rules.
States Treating Pensions as Regular Income
In certain states, the income you receive from your teacher pension plan is considered ordinary income and is fully subject to the state's income tax rates, just like your salary was when you were working. There are no special exemptions or deductions specifically for public employee pensions in these jurisdictions.
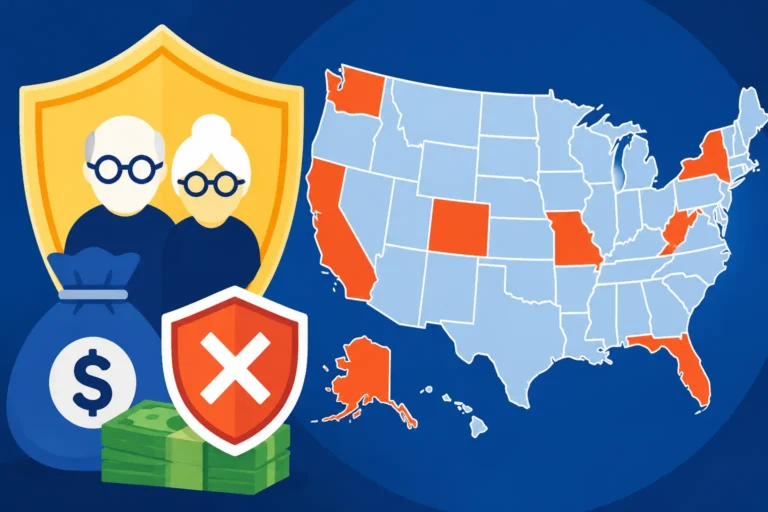
For example, California, despite its high income tax rates, does not offer a specific exemption for teacher pensions. While there might be other general deductions or credits available to all taxpayers, the pension itself is fully taxable. This means that a retired teacher in California will pay state income tax on their CalSTRS pension based on their overall income bracket. This can come as a surprise to many, especially if they're used to hearing about tax-friendly states for retirees. Understanding this distinction is vital for teachers planning their retirement in states like California, where the question of Is California Tax Friendly? Full Breakdown often comes with a nuanced answer, especially for those relying on pensions. It’s a key factor when you’re looking at Highest Income Tax States in 2026 and trying to map out your post-career finances.
The Impact of Progressive Tax Structures
States with progressive income tax structures, where higher incomes are taxed at higher rates, can particularly impact retired teachers whose pensions, combined with other retirement income sources, push them into higher tax brackets. If a state doesn't offer specific pension exemptions, that progressive structure means a larger portion of a higher pension could be claimed by the state.
For instance, New York, while offering some exclusions for specific types of retirement income (like up to $20,000 for pensions and annuities for those over 59.5), generally has a progressive income tax structure that can significantly impact retirees. A teacher with a substantial pension and other income might quickly exceed the exclusion limits and face higher tax rates. This is why understanding New York Income Tax Brackets 2026 is crucial for educators there. These states illustrate why it's so important to research How Each State Taxes Retirement Income (50-State Guide) and how different types of retirement income, including pensions, are treated. A resource like SmartAsset can be useful for comparing tax burdens across states, helping retirees visualize the real impact of these progressive rates on their total income.
State-by-State Overview of Teacher Pension Taxation
Let's break down the general landscape of how teacher pensions are taxed across various states. Keep in mind that tax laws can change, so it's always best to verify the latest information for your specific situation. This table provides a high-level overview.
| Category | Examples of States (Teacher Pensions) | Key Characteristic |
|---|---|---|
| No State Income Tax | Florida, Texas, Washington, Nevada, Alaska, South Dakota, Wyoming, Tennessee, New Hampshire (no broad income tax) | No state income tax is imposed on any income, including teacher pensions. |
| Fully Exempt | Illinois, Mississippi, Pennsylvania | States with an income tax, but all public and often private retirement income (including teacher pensions) is explicitly exempt. |
| Partially Exempt/Deductible | New York, Colorado, Georgia, New Jersey, Michigan, Ohio, Kentucky, Virginia | States with an income tax that offer specific exclusions, deductions, or credits for public pensions. This could be a dollar amount, based on age, or tied to income levels. For example, New York Taxes Pensions but offers a $20,000 exclusion. Georgia offers a significant exclusion for those 65+. |
| Fully Taxable | California, Nebraska, Montana, Rhode Island, Vermont, Utah | States with an income tax where teacher pensions are generally treated as ordinary income, with no specific exemptions for public retirement benefits beyond general deductions available to all taxpayers. |
Nuances of Specific State Laws
Delving deeper into specific state laws reveals just how varied the landscape is. For instance, even within categories, there can be subtle differences that impact your overall tax burden. This is where personalized research or professional advice becomes invaluable.
Take New York, for example. While it does tax income, it offers an exclusion of up to $20,000 for public and private pensions for individuals aged 59 1/2 or older. This means if a teacher's annual pension is $50,000, only $30,000 of it would be subject to New York state income tax. However, this exclusion typically doesn't apply to IRA distributions or 401(k) withdrawals unless converted to an annuity. This is a crucial detail for teachers who might also have other retirement accounts. For a comprehensive look at your options, you might want to compare The 8 States That Still Tax Social Security alongside those that are more generous with pensions. This helps paint a complete picture of your retirement income.
Similarly, states like Massachusetts and Connecticut, while having an income tax, often have specific rules that can make them more favorable for in-state public pensions. For instance, Massachusetts generally exempts pensions from its own state and local governments. This means a teacher who retired from a Massachusetts public school system would likely not pay state income tax on their Massachusetts teacher pension. However, a teacher receiving a pension from another state might find it taxable in Massachusetts. These intricacies highlight why it's so important to understand the specifics of How Each State Taxes Retirement Income (50-State Guide) and how it applies to your unique situation, especially if you're considering Moving to a Tax-Friendly State for Retirement.
The Importance of Domicile and Residency
Beyond the state where you earned your pension, your state of domicile in retirement plays a critical role in how your pension is taxed. Domicile is your true, fixed, and permanent home, the place where you intend to return whenever you are absent. You can only have one domicile.
If you earned your teacher pension in California but move and establish domicile in Florida (a no-income-tax state) before retiring, your California pension generally would not be subject to California state income tax. This is because non-residents typically only pay state income tax to California on income sourced from California, and pensions are generally considered income of the state of residence at the time of distribution. However, this is a complex area, and states with high income taxes, like California and New York, are notorious for scrutinizing changes in residency. Establishing a new domicile involves more than just buying a house; it often requires severing ties with the old state (e.g., changing driver's license, voter registration, bank accounts, medical providers). It's a significant undertaking, and understanding How to Change Your State Residency for Taxes is crucial if you plan to move to minimize your state tax burden in retirement. This can be a significant part of How to Minimize State Taxes in Retirement strategy.
Planning for Your Teacher Pension in Retirement
Navigating the tax landscape for your teacher pension can feel like a full-time job in itself. But with a bit of planning and understanding, you can make informed decisions that help you make the most of your retirement income.
Utilizing Tax-Advantaged Retirement Accounts
Beyond your defined benefit teacher pension, many teachers also contribute to other retirement vehicles, such as 403(b)s, 457(b)s, or personal IRAs. The taxation of withdrawals from these accounts at the state level can differ significantly from how your traditional pension is treated.
For example, while your teacher pension might be partially or fully exempt in a particular state, withdrawals from a traditional IRA or 403(b) might be fully taxable. Conversely, qualified distributions from Roth IRAs are generally tax-free at both federal and state levels, provided certain conditions are met. Understanding these differences is key to optimizing your retirement income strategy. It's not just about your pension; it's about the entire mosaic of your retirement assets. This is why resources that detail States That Don't Tax 401(k) & IRA Withdrawals are incredibly valuable for comprehensive retirement planning.
Seeking Professional Financial Advice
Given the complexities and state-specific nuances, one of the best steps any retiring teacher can take is to consult with a financial advisor specializing in retirement planning and state tax laws. They can help you understand your specific state's rules, compare options if you're considering a move, and develop a personalized strategy to minimize your tax burden.
A good advisor can help you project your income from all sources—pension, Social Security, 403(b)s, and other investments—and illustrate how that income will be taxed in your current state or a potential new state. They can also help you understand how different states treat Social Security Taxation: Federal + the 8 States, providing a holistic view of your retirement income. Tools and insights from financial planning services, including those offered by SmartAsset, can also be instrumental in helping you visualize and plan for these complex scenarios, ensuring you're making the most tax-efficient choices for your hard-earned retirement.
Disclaimer
Please remember that tax laws are complex and subject to change. The information provided in this guide is for informational purposes only and does not constitute professional tax or financial advice. You should consult with a qualified tax professional or financial advisor for advice tailored to your specific situation.